










KEC International Q2 FY27 Revenue Falls 10%, PAT Drops 82%
Key highlights
- KEC International reported Q2 FY27 consolidated revenue of ₹5,468 crore, down from ₹6,092 crore in Q2 FY26.
- KEC International’s Q2 FY27 PAT fell 81.5% year-on-year to about ₹30 crore from ₹161 crore.
- KEC International reported a 5.0% EBITDA margin in Q2 FY27, compared with 7.1% a year earlier.
- KEC International’s order book reached ₹39,946 crore, while year-to-date order intake exceeded ₹13,500 crore.
powered by IRIS
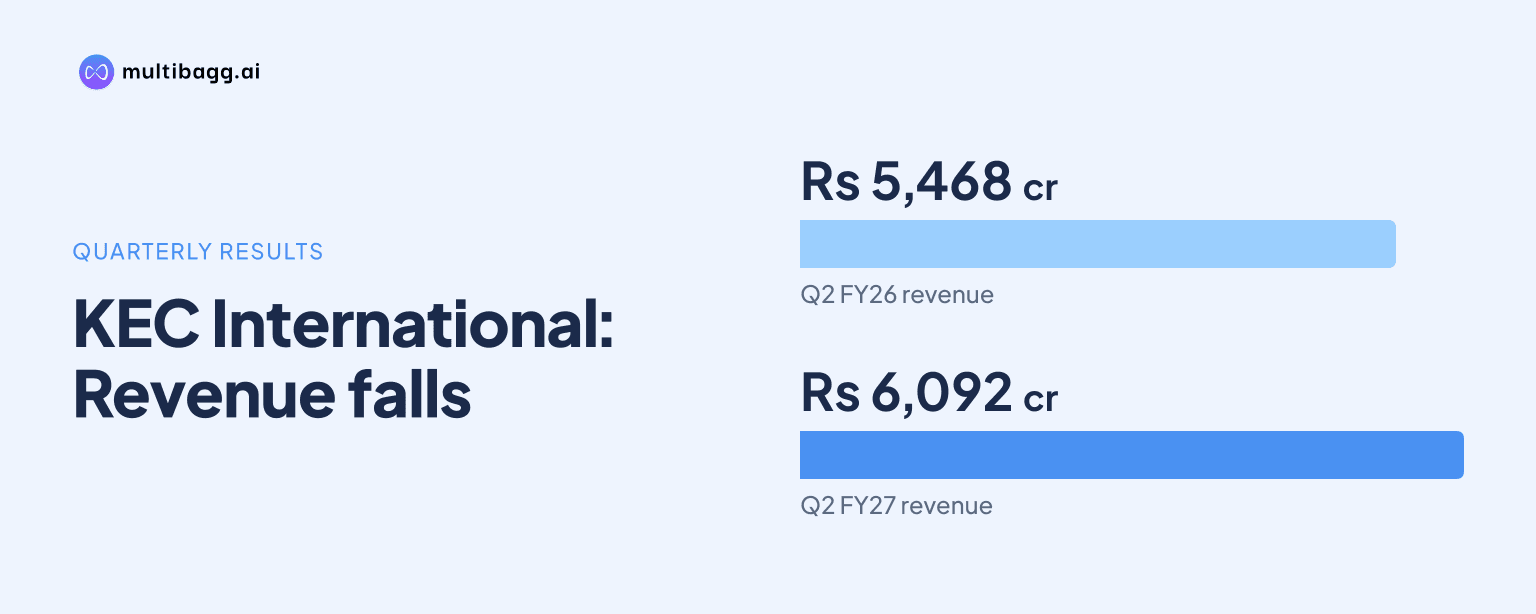
KEC International Ltd reported Q2 FY27 consolidated revenue of ₹5,468 crore, down from ₹6,092 crore a year earlier, while profit after tax fell to ₹30 crore from ₹161 crore. The decline in revenue, profit and operating margin came even as the infrastructure EPC company reported record order-book levels and substantial Transmission & Distribution order intake.
Know KEC International inside out
Results, valuation, peers and who's buying, in one view.
What did KEC International report for Q2 FY27?
KEC International reported consolidated revenue of ₹5,468 crore for the quarter ended September 30, 2026, compared with ₹6,092 crore in Q2 FY26. This represents a year-on-year decline of about 10%. Consolidated profit after tax was ₹29.74 crore, or approximately ₹30 crore, against ₹160.75 crore in the corresponding quarter last year.
The reported PAT decline was 81.5% year-on-year. EBITDA stood at about ₹270 crore, with the EBITDA margin at 5.0%, compared with a 7.1% margin in Q2 FY26. The company’s results therefore showed pressure on both revenue and profitability during the September 2026 quarter.
On a standalone basis, revenue was ₹4,161 crore in Q2 FY27, compared with ₹4,949 crore a year earlier. Standalone PAT was ₹80 crore, against ₹106 crore in Q2 FY26. For the first half of FY27, standalone revenue stood at ₹8,059 crore, while standalone PAT was ₹81 crore.
How were the Q2 FY27 results approved and reviewed?
KEC International’s Board of Directors unanimously approved the consolidated and standalone unaudited financial results on November 2, 2026. The results cover the quarter and half year ended September 30, 2026 and were prepared under applicable accounting standards.
Price Waterhouse Chartered Accountants LLP conducted a limited review of the financial statements. According to the review report, nothing came to the auditors’ attention that indicated the statements were not prepared, in all material respects, in accordance with the prescribed accounting principles and regulations.
The company has made the detailed results and the limited review report available through its website. It has also scheduled an earnings conference call for November 3, 2026, at 10:00 a.m. IST, when Managing Director Vimal Kejriwal and CFO Rajeev Aggarwal are expected to discuss the quarter and half-year performance.
What is driving KEC International’s order book?
KEC International reported year-to-date order intake of more than ₹13,500 crore, including approximately ₹9,500 crore from its Transmission & Distribution, or T&D, business. Its order book reached a record ₹39,946 crore, while the combined order book and L1 pipeline stood at around ₹43,500 crore.
The company also secured fresh orders worth ₹6,195 crore during Q2 FY27. The announced orders included ₹1,303 crore on September 14, ₹1,014 crore on October 10, ₹1,006 crore on October 23 and ₹2,872 crore on October 24, 2026.
The ₹2,872 crore order from Power Grid Corporation of India Limited was described as KEC International’s largest single order in its India T&D business. The 765 kV transmission-line projects are intended to support evacuation of 8.5 GW of renewable energy from Gujarat. The company has also cited a tender pipeline exceeding ₹2 lakh crore.
Got a follow-up? Ask IRIS
What do the results indicate for KEC International’s operations?
The September-quarter numbers show that the company entered Q2 FY27 with a lower revenue base and materially weaker profitability than a year earlier. The EBITDA margin narrowed by 2.1 percentage points, which is relevant because margin movement has a direct effect on profit even when the business carries a substantial order backlog.
The order data points to continued activity in T&D, particularly in large domestic transmission projects. However, the announced order book and L1 position represent work available for execution and do not by themselves establish the timing of revenue recognition or future margins. Investors will assess execution and profitability trends through subsequent reported results.
KEC International’s cables and conductors business is also adding product capacity. Elastomeric cables and an electron-beam plant are slated to begin production in Q2 FY27, while the company has already shipped UL-certified cables to the United States. These developments open an export market that requires stringent product certification, although the disclosed results do not quantify their financial contribution.
How does the quarter compare with recent performance?
KEC International reported consolidated revenue of ₹5,024 crore in Q1 FY27, with net profit of ₹72.62 crore. Revenue in Q2 was higher sequentially, but Q2 PAT was lower than the Q1 level. The company’s Q1 revenue had been broadly flat year-on-year, while Q1 profit was reported to have declined 42%.
For comparison, the September 2025 quarter delivered ₹6,092 crore of revenue, ₹161 crore of PAT and a 7.1% EBITDA margin. The current quarter therefore had a high comparative base for revenue and profit. The company’s disclosed financial statements remain the primary reference for evaluating the trend across its consolidated and standalone businesses.
Conclusion
KEC International’s Q2 FY27 results combined lower consolidated revenue with a steep decline in PAT and a narrower EBITDA margin. At the same time, order intake of more than ₹13,500 crore and an order book of ₹39,946 crore show continued demand for its T&D capabilities and other EPC offerings.
The immediate item to watch is management’s November 3 earnings call, where investors may seek further detail on execution, margin performance, debt reduction and the conversion of the ₹43,500 crore order-book and L1 position into revenue. Progress in the stated tender pipeline and the planned Q2 FY27 start of new cable-production facilities will also remain relevant.