










Laurus Labs Limited Q2 Revenue Rises 33% to ₹2,206 Crore
Key highlights
- Laurus Labs Limited reported record Q2 FY27 revenue of ₹2,206 crore, up 33% year-on-year.
- Q2 FY27 EBITDA rose 78% to ₹762 crore and the EBITDA margin reached 34.5%.
- Small-molecule CDMO sales increased 86% to ₹875 crore in Q2 FY27.
- H1 FY27 revenue was ₹4,233 crore and EBITDA was ₹1,406 crore.
powered by IRIS
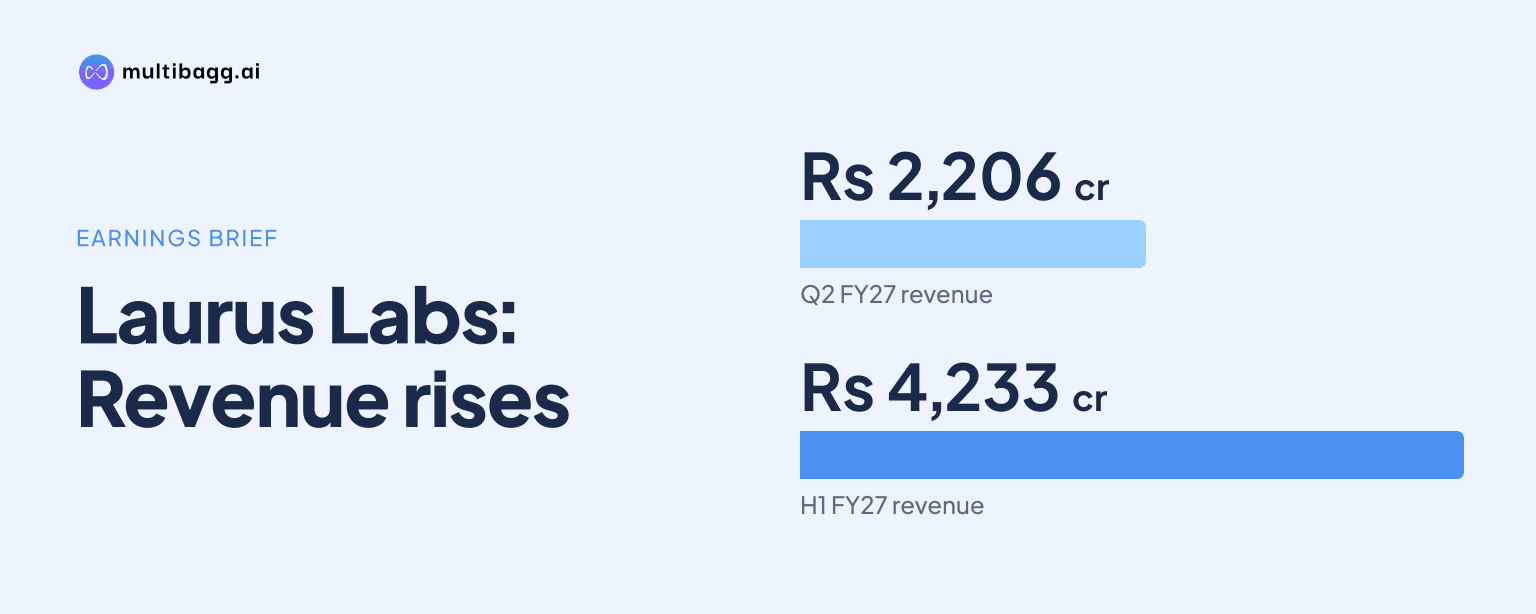
Laurus Labs Limited reported record Q2 FY27 revenue of ₹2,206 crore, up 33% year-on-year, while EBITDA increased 78% to ₹762 crore and the EBITDA margin reached 34.5%. The performance was supported by strong contract development and manufacturing organisation, or CDMO, execution, commercial-phase supplies and continued momentum in its Affordable Medicines portfolio.
Know Laurus Labs inside out
Results, valuation, peers and who's buying, in one view.
What did Laurus Labs report in Q2 FY27?
Laurus Labs reported its highest quarterly income from operations since inception at ₹2,206 crore for the quarter ended September 2026. Revenue grew 33% from the corresponding quarter of the previous year, according to the company’s Q2 FY27 results and earnings call disclosures. Net profit for the quarter was ₹441 crore, a 126% year-on-year increase.
Profitability improved along with revenue. EBITDA rose 78% year-on-year to ₹762 crore, translating into an EBITDA margin of 34.5%. The margin was 2.7 percentage points higher than the previous quarter, as cited in the company’s earnings commentary. Gross margin stood at 63.0%, compared with 59.9% a year earlier.
The company also reported consolidated profit after tax, including associate and joint-venture results, of ₹436.19 crore for the quarter, compared with ₹194.49 crore in the year-earlier period. Consolidated basic earnings per share was ₹8.17 in Q2 FY27.
Which businesses drove Laurus Labs' quarterly growth?
Laurus Labs said its CDMO platform was the main contributor to the quarter’s growth, supported by growing commercial-phase supplies. The company also cited ongoing momentum in Affordable Medicines as a contributor to the ₹2,206 crore quarterly revenue performance.
Within CDMO, the small-molecule business recorded sales of ₹875 crore in Q2 FY27, an 86% increase according to Krishna Chaitanya Chava, Executive Director and Head CDMO. For the first half of FY27, small-molecule CDMO sales were ₹1,710 crore. Management said the division continued to deliver operational execution during the quarter.
The company also referred to new peptide manufacturing capabilities in its results communication. The supplied disclosures do not provide revenue, capacity or commissioning details for these capabilities. They nevertheless form part of Laurus Labs’ stated focus on strengthening its CDMO platform.
Management attributed the gross-margin performance to a better product mix, division mix and improved operational efficiencies. It linked the EBITDA-margin expansion to product mix and operating leverage, indicating that the faster-growing businesses made a larger contribution to the quarter.
Got a follow-up? Ask IRIS
How did the first half of FY27 perform for Laurus Labs?
Laurus Labs reported H1 FY27 revenue from operations of ₹4,233 crore, up 31% year-on-year. The figure is also reported in the earnings summary as ₹4,232.68 crore, with the difference reflecting rounding. Management said first-half growth was led by continued CDMO execution and stable Affordable Medicines performance.
H1 EBITDA rose to ₹1,406 crore from ₹818 crore in the previous year’s first half, a 72% increase. The EBITDA margin was 33.2%, while gross margin expanded to 62.9% from 59.6% in H1 FY26. Net profit for the first half was ₹809 crore, up 126% year-on-year.
The H1 numbers show that the improvement was not confined to a single quarter. Revenue, gross margin and EBITDA margin all increased over the first six months, while small-molecule CDMO generated ₹1,710 crore in sales. Consolidated basic EPS for H1 FY27 was reported at ₹8.16.
Why do the higher margins matter to investors and operations?
The higher margins matter because Laurus Labs converted revenue growth into a faster increase in EBITDA and net profit. Q2 revenue increased 33% year-on-year, while EBITDA increased 78% and net profit increased 126%. The gap reflects the reported effect of product mix, division mix and operating leverage on profitability.
For investors, the key reported metrics are the 34.5% Q2 EBITDA margin, 63.0% gross margin and the 86% growth in small-molecule CDMO sales. These numbers indicate that CDMO had a meaningful role in the company’s quarterly performance. However, the available disclosure does not provide a segment-wise profit split, customer details, future guidance or capital-spending figures.
For industry operations, the results highlight the relevance of commercial-phase supplies and manufacturing execution within the CDMO business. Laurus Labs’ management specifically identified both factors when discussing its performance. The company’s reference to peptide manufacturing capabilities also signals an operational addition, although financial contributions from that capability were not disclosed.
The company hosted its Q2 FY27 earnings conference call on October 29, 2026, with DAM Capital Ltd as host. A regulatory filing said the audio recording was made available through the company’s website. The disclosed management remarks focused on delivered financial performance rather than future projections.
Conclusion
Laurus Labs delivered record Q2 FY27 revenue of ₹2,206 crore and expanded its EBITDA margin to 34.5%, with CDMO execution, commercial supplies and Affordable Medicines supporting growth. The first-half results reinforced the trend, as revenue rose 31% to ₹4,233 crore and EBITDA increased to ₹1,406 crore.
Investors will watch the progression of CDMO sales, particularly small-molecule business performance after its ₹1,710 crore H1 contribution, and the development of the company’s peptide manufacturing capabilities. The available Q2 disclosures do not specify revenue guidance, capacity targets or timelines for these operations.