










PG Electroplast Reports 42.5% Q2 Revenue Growth to ₹934 Crore
Key highlights
- PG Electroplast reported Q2 FY27 consolidated revenue of ₹933.88 crore, up 42.5% year-on-year.
- Q2 FY27 EBITDA rose 54.8% to ₹69.14 crore, and EBITDA margin improved to 7.4% from 6.8%.
- H1 FY27 consolidated revenue increased 37.4% year-on-year to a record ₹2,967.83 crore.
- PG Electroplast targets room AC deliveries of 2.1 million to 2.2 million units in FY27 versus 1.7 million units previously.
powered by IRIS
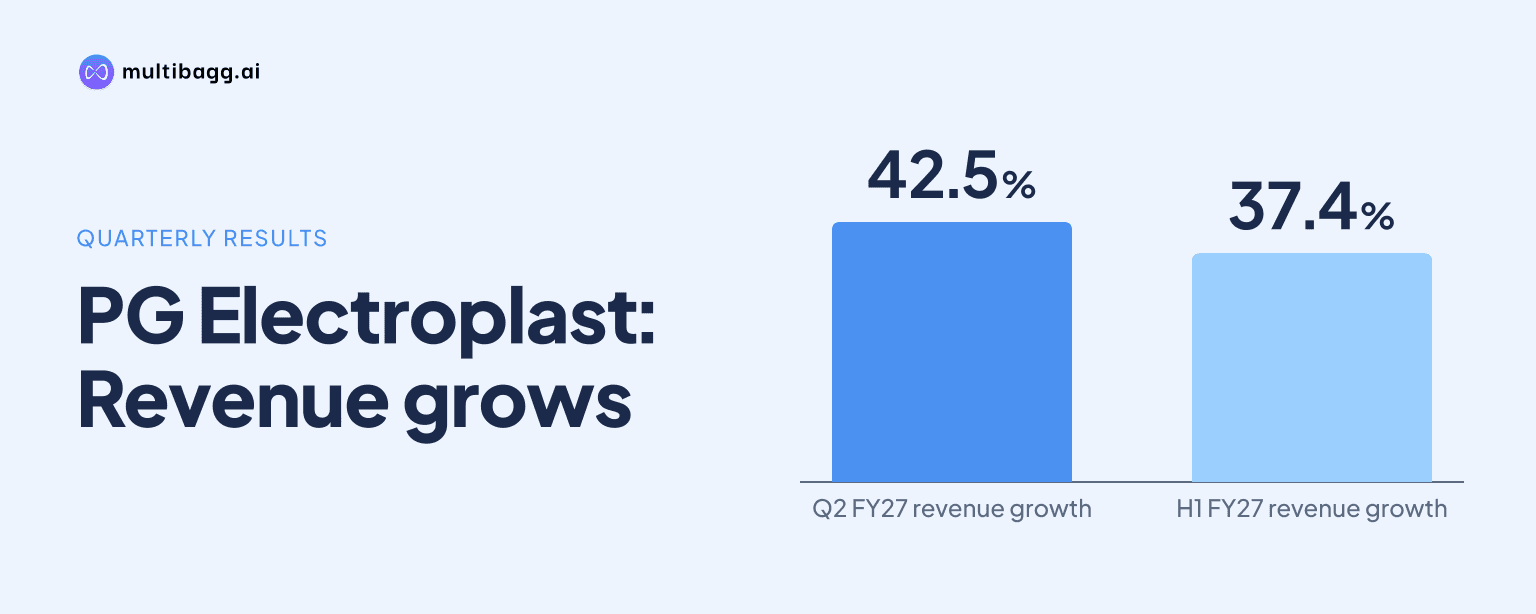
PG Electroplast Limited reported Q2 FY27 consolidated revenue of ₹933.88 crore, up 42.5% year-on-year, while EBITDA rose 54.8% to ₹69.14 crore and EBITDA margin improved to 7.4%. The performance added to a record first half, with management citing strong room air-conditioner secondary sales and a healthy order book.
Know PG Electroplast inside out
Results, valuation, peers and who's buying, in one view.
How did PG Electroplast perform in Q2 FY27?
PG Electroplast delivered higher revenue, operating profit and net income in Q2 FY27. Consolidated revenue was ₹933.88 crore, compared with the prior-year quarter's base implied by the reported 42.5% growth. EBITDA increased to ₹69.14 crore from ₹44.68 crore, while net income rose to ₹13.67 crore from ₹2.76 crore.
The operating margin improved to 7.4% from 6.8% a year earlier. This indicates that EBITDA grew faster than revenue during the quarter. The company reported these figures during its earnings call held after the Q2 FY27 results, with Managing Director Vishal Gupta, Chief Financial Officer Pramod Gupta and Managing Director, Operations Vikas Gupta participating.
What drove PG Electroplast's first-half revenue growth?
PG Electroplast's H1 FY27 consolidated revenue rose 37.4% year-on-year to ₹2,967.83 crore, its highest first-half revenue to date. The room AC and washing machine verticals recorded their highest-ever first-half sales, according to management.
Management said first-half growth came from a combination of higher volumes and prices. The product business accounted for 70.3% of sales revenue and grew 41.1% year-on-year. This shows that product-led operations were the principal contributor to the company's first-half expansion.
H1 FY27 EBITDA rose 22.4% to ₹225.37 crore, while net income increased 28.9% to ₹89.88 crore. The gap between the first-half EBITDA growth rate and the second-quarter rate reflects the reported stronger operating performance during Q2, although the company did not provide further quarter-wise factors for the difference.
What did management say about demand and order books?
PG Electroplast said room AC industry secondary sales were good in Q2, supporting a strong order book for the company. Vishal Gupta said primary sales were muted during the period, but channel inventory was much lower than in the previous year.
Primary sales refer to shipments into the distribution channel, while secondary sales reflect sales to end customers. Management's comments therefore point to demand at the retail level even as immediate channel stocking remained subdued. The company said its teams were preparing for stronger execution in the second half of FY27.
For FY27, PG Electroplast expects room AC volume growth of about 20%, with deliveries of 2.1 million to 2.2 million units against 1.7 million units in the prior year. Management also guided for 40% to 50% growth in washing machines, with sales approaching ₹1,000 crore. Its electronics sales target is ₹550 crore within a ₹500 crore to ₹600 crore range.
Got a follow-up? Ask IRIS
Which expansion projects are scheduled for commissioning?
PG Electroplast said its refrigerator plant at Sri City remains on track to begin commercial production in Q4 FY27. The compressor project at Supa is also progressing as scheduled, with mass production planned for January to February 2027.
These projects form part of the company's effort to expand its manufacturing base across appliance categories. Their operational ramp-up and profitability are priorities for management alongside meeting order-book requirements. The company did not disclose investment amounts, expected capacity, or revenue contribution from these facilities during the information provided.
The planned commissioning dates matter because they coincide with the company's focus on H2 FY27 execution. New manufacturing operations require a transition from project completion to stable commercial production, and management has identified ramp-up as a central execution area.
How do the results matter for investors and the appliance industry?
PG Electroplast's results show growth across revenue, EBITDA and net income, with the 54.8% rise in quarterly EBITDA exceeding the 42.5% increase in revenue. The margin improvement to 7.4% is also relevant because profitability, rather than sales growth alone, will determine the financial contribution of the expanding product business.
For investors, the disclosed operating targets provide measurable indicators for subsequent updates: room AC deliveries of 2.1 million to 2.2 million units, washing machine growth of 40% to 50%, and electronics sales in the ₹500 crore to ₹600 crore range. Management's reference to lower channel inventory and strong secondary sales also makes order conversion and second-half execution important areas to track.
For the wider appliance manufacturing chain, the company's expansion into refrigerator and compressor production indicates additional activity in domestic manufacturing operations. However, the company has not provided projections for capacity utilisation, customer additions, pricing, or the financial effect of the new plants, so those outcomes remain unquantified.
Conclusion
PG Electroplast recorded a stronger Q2 FY27, with consolidated revenue reaching ₹933.88 crore and EBITDA rising to ₹69.14 crore. Record first-half sales in room AC and washing machines, a 7.4% EBITDA margin, and higher net income underline the scale-up in its product operations.
The next disclosures to watch are second-half execution against room AC and washing machine growth targets, the Q4 FY27 commercial start at the Sri City refrigerator plant, and the January-February 2027 mass-production schedule for the Supa compressor project.