










State Bank of India Q2 FY27: NII Seen Rising 11-13%
Key highlights
- State Bank of India will consider Q2 FY27 results for the quarter ended September 30, 2026, on November 3, 2026.
- Brokerages estimate SBI's Q2 FY27 net interest income at ₹47,770 crore to ₹48,959 crore, implying 11-13.9% year-on-year growth.
- Profit after tax estimates range from ₹20,378 crore to ₹25,250 crore for the September quarter.
- SBI has guided for FY27 credit growth of 14-16% and net interest margin of around 3%.
powered by IRIS
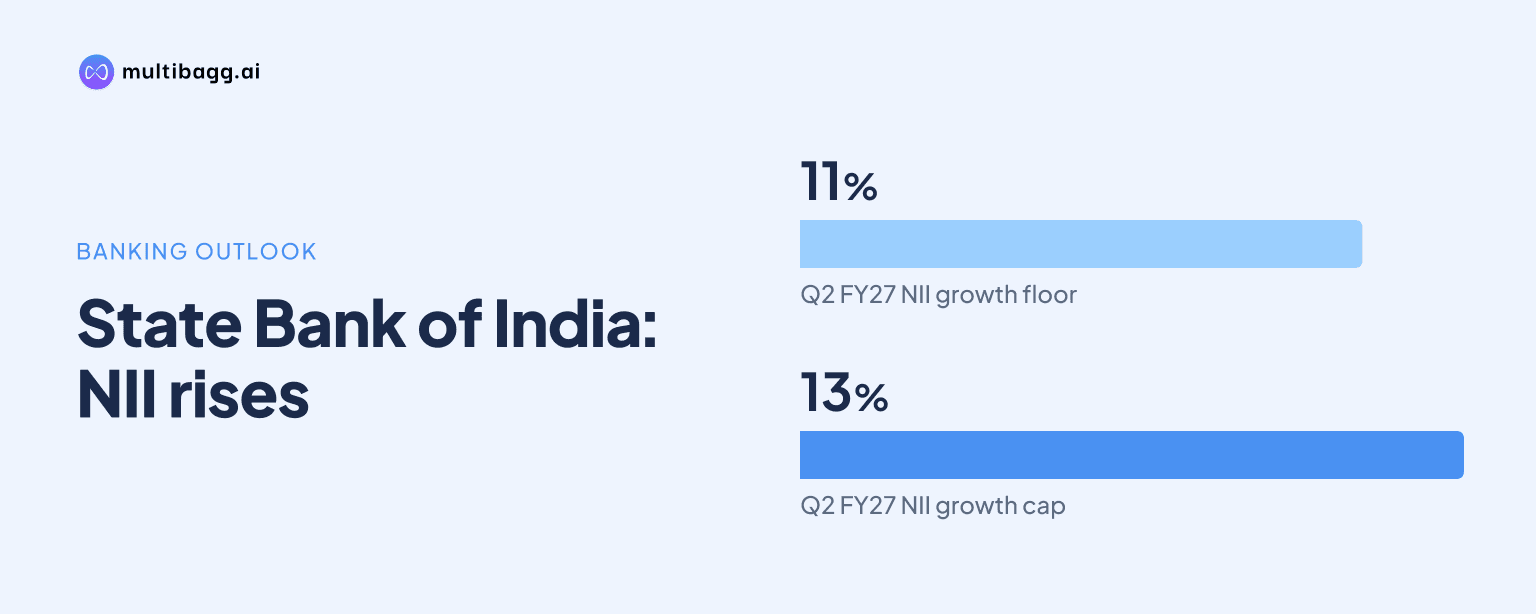
State Bank of India is scheduled to consider Q2 FY27 results on November 3, 2026, with brokerages estimating 11-13% year-on-year growth in net interest income. The September-quarter announcement will put the lender's credit growth, deposit mobilisation, margins, profitability and asset quality under close investor scrutiny.
Know State Bank of India inside out
Results, valuation, peers and who's buying, in one view.
When will State Bank of India announce Q2 FY27 results?
State Bank of India will announce its financial results for the quarter and half-year ended September 30, 2026, after its Central Board meeting on Tuesday, November 3, 2026. The reporting period covers July to September 2026 and forms the second quarter of FY 2026-27.
India's largest public sector lender has stated that the board meeting is being held to consider and approve the financial results for the period ended September 30. SBI is among several companies scheduled to report earnings on November 3, including National Stock Exchange of India, Bajaj Finserv, Lupin and Multi Commodity Exchange of India.
The results will follow SBI's June-quarter performance, when the bank reported total income of ₹1,43,819.15 crore and net profit of ₹21,121.22 crore. Comparisons with that quarter will help investors assess whether loan growth and funding costs are supporting sequential earnings momentum.
What are brokerages expecting from SBI's September-quarter earnings?
Brokerage estimates point to year-on-year NII growth of about 11-13% for SBI in Q2 FY27. Estimates for NII range from ₹47,770 crore to ₹48,959 crore, compared with a reported year-ago base of about ₹42,980 crore to ₹42,984 crore across the supplied estimates.
Profit projections show a wider range because assumptions differ on operating income, provisions and the comparison base. The broader estimates place profit after tax between ₹20,378 crore and ₹25,250 crore. ET Now Research estimates PAT at ₹22,619 crore, up 12.20% year-on-year and 7.09% sequentially from ₹21,121 crore in Q1 FY27.
Motilal Oswal expects net profit of ₹19,620 crore, down 2.7% year-on-year, noting that Q2 FY26 included an exceptional gain of ₹4,590 crore. In contrast, MOFSL estimates PAT of ₹25,250 crore, up 25.2% year-on-year, while CNBC-TV18's poll projects ₹22,589 crore, a 13% annual increase.
Got a follow-up? Ask IRIS
Which operating metrics will investors watch in SBI's results?
Investors will focus on advances, deposits, net interest margin and asset-quality trends in SBI's Q2 FY27 disclosures. These indicators will show whether the bank is expanding its loan book while maintaining funding discipline and controlling credit costs.
SBI has guided for FY27 credit growth of 14-16%, revised from its earlier 13-15% guidance. One set of estimates projects advances to grow 3.81% sequentially and 18.81% year-on-year, with growth expected across small and medium enterprises, corporate lending, agriculture and Xpress Credit.
Deposit growth is also a key area because it affects a bank's funding mix and margins. Estimates place deposits at ₹62.7 lakh crore, up 4.33% sequentially from ₹60.1 lakh crore and 12.16% from ₹55.9 lakh crore a year earlier.
On margins, ET Now Research expects whole-bank NIM to improve by 3 basis points sequentially to 2.89%, though this would remain 8 basis points below the 2.97% reported for Q2 FY26. Prabhudas Lilladher expects NIM of 2.8%, while SBI has maintained FY27 NIM guidance at around 3%.
How could asset quality and provisions affect SBI's profit?
Asset quality and provisions could materially influence SBI's reported profit because credit-cost assumptions vary across brokerage forecasts. While interest income and operating-profit expectations are generally positive, provisions are a major reason for the spread in PAT estimates.
ET Now Research estimates provisions of ₹5,558 crore for Q2 FY27, up 2.93% year-on-year and 10.12% quarter-on-quarter. The estimate is relevant because a higher provisioning charge can reduce net profit even if NII and non-interest income increase.
The supplied forecasts indicate continued improvement in headline asset-quality ratios. Gross NPAs are estimated at 1.45%, versus 1.47% in Q1 FY27 and 1.73% a year earlier, while net NPAs are estimated at 0.37%, compared with 0.38% and 0.42%, respectively. Motilal Oswal separately projects gross NPA at 1.4% and net NPA at 0.4%.
For shareholders, the result will provide a clearer view of whether the bank can sustain loan growth, manage deposits and protect margins within its stated FY27 operating framework. The actual earnings release will be more important than any individual forecast because the estimates differ significantly on profit and operating performance.
Conclusion
SBI's Q2 FY27 announcement is expected to show continued growth in NII, with brokerages projecting an 11-13% annual increase, alongside improving asset-quality ratios. However, PAT forecasts range widely from ₹20,378 crore to ₹25,250 crore, reflecting different views on provisions, other income and the impact of the prior year's exceptional gain.
Investors will watch SBI's reported credit and deposit growth, NIM, provisions and gross and net NPA ratios when the board considers the September-quarter and half-year results on November 3, 2026. The bank's 14-16% FY27 credit-growth guidance and NIM guidance of around 3% remain key reference points for the rest of the financial year.