Actions
Action Type



Welcome to Multibagg AI
Log in to access personalized features
IRIS
Multibagg AI is an AI powered stock research and analysis platform. We provide data, information, content, and analytics for publicly traded Indian companies listed on NSE and BSE. AI can make mistakes, check important information.
Research powered by GOALZEN CAPITAL SERVICES PRIVATE LIMITED · SEBI Research Analyst INH000013448
Prices might be delayed by a few minutes.
Join our Exclusive Community


Join our Exclusive Community
Made with 💙 in India. © Finsky Technologies Pvt Ltd. 2026


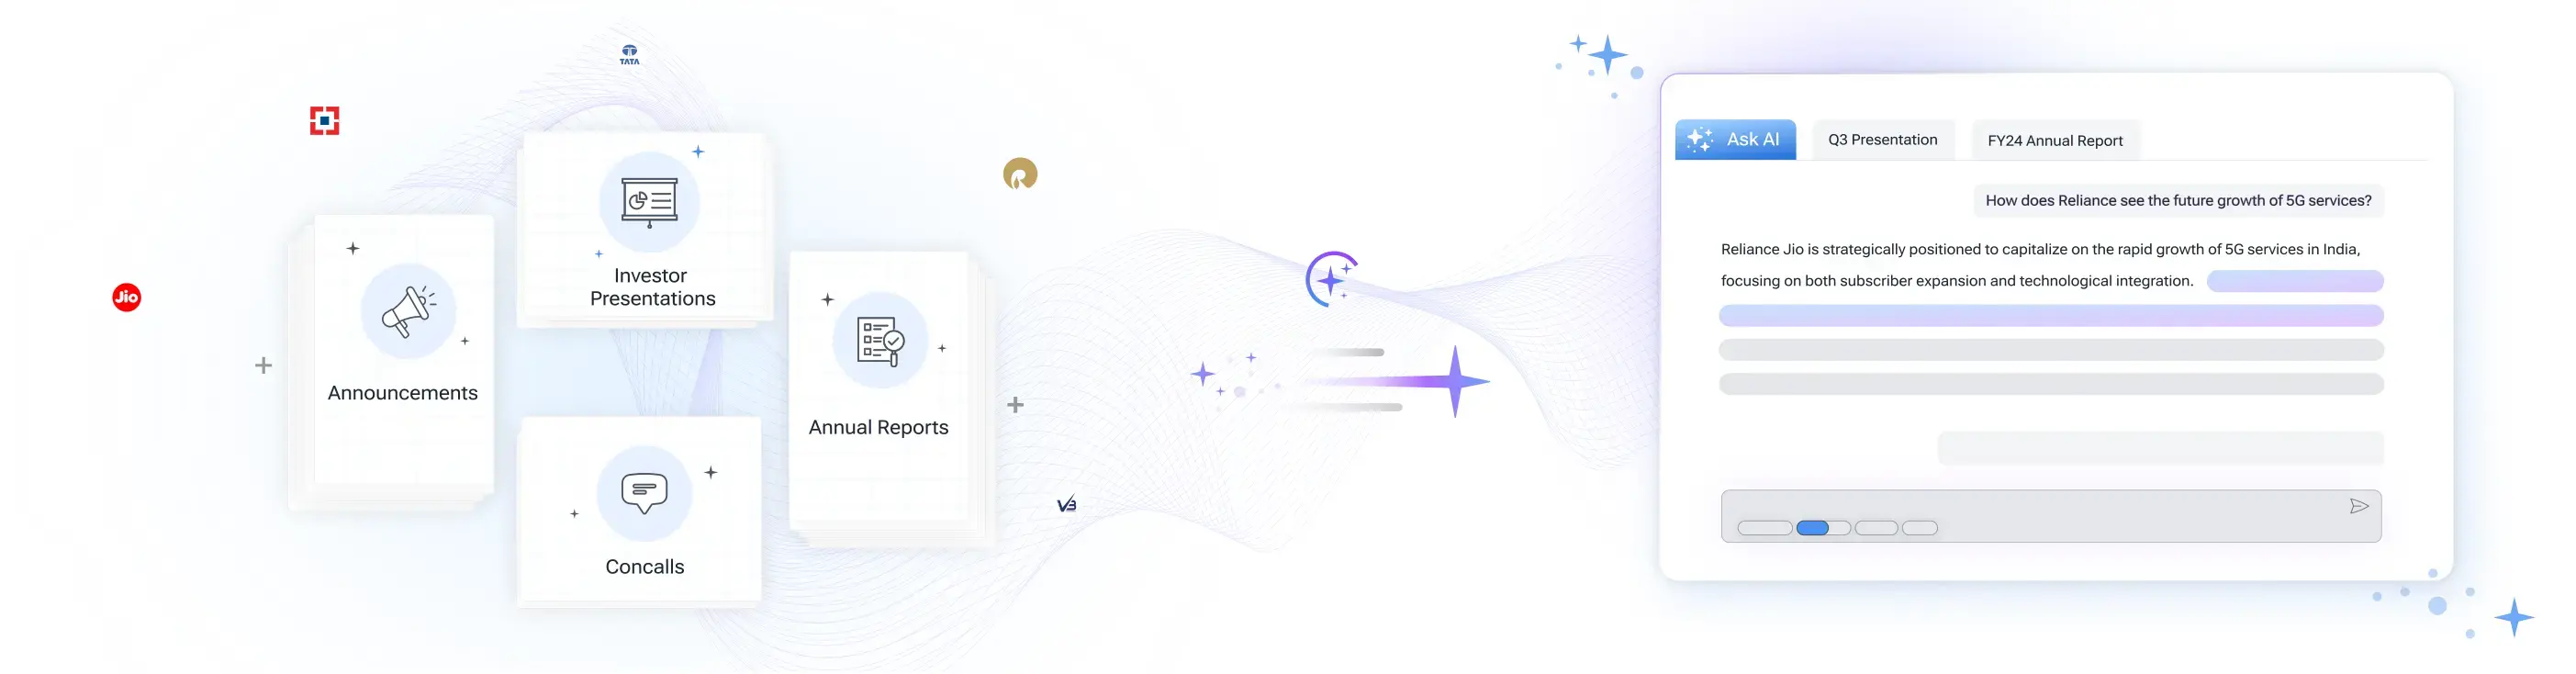
Get instant AI-powered insights about company performance, financials, and strategy. Ask questions about trends, competition, and developments while receiving responses backed by official documents and market data, with clear attribution to source documents.

 Discovery themes featuring this stock
Bearish
4
Neutral
2
Bullish
8
Bearish
36
Neutral
2
Bullish
8
Bearish
32
Neutral
0
Bullish
0
Bearish
4
Neutral
2
Bullish
8
Bearish
4
Neutral
2
Bullish
8
Bearish
32
Neutral
0
Bullish
0
Bearish
32
Neutral
0
Bullish
0
Bearish
32
Neutral
0
Bullish
0
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone


 Discovery themes featuring this stock
Jubilant Foodworks Ltd (JUBLFOOD) is currently trading at 404.50 per share. Stock prices fluctuate during market hours on NSE and BSE based on demand, company updates, and overall market conditions. Refer to the live price chart above for the most recent price movement.
Jubilant FoodWorks Limited is India’s largest food‑service company operating brand‑owned and franchised Quick Service Restaurant (QSR) concepts including Domino’s Pizza, Popeyes (master franchise rights), ChefBoss packaged foods, and other brand initiatives; the company runs an extensive store network supported by commissaries, a Jubilant Food park and dedicated technology platforms. Popeyes has emerged as a second growth engine with dramatic acceleration: same‑store dynamics show LFL growth jumping from single digits to roughly 40%–45% in the latest quarter, driven by product differentiation, supply‑chain integration and focused store execution, making Popeyes an important near‑term contributor to JFL’s top‑line expansion and margin potential. Management reiterated disciplined capital allocation with FY27 capex guidance of INR 750–900 crore concentrated on new stores, selective store upgrades (dine‑in focus) and technology investments rather than large new supply chain builds, while earlier commissaries and Mumbai food factory commissioning improve supply economics and allow JFL to ‘sweat’ existing assets for better returns. Margin and free cash flow focus: JFL reported healthy gross margins (around 75.5% in the quarter), turned free cash flow positive in FY26 and is pursuing a 200bp structural improvement plan split between Domino’s and emerging brands while balancing calibrated pricing, cost efficiencies and selective marketing to protect profitability amid commodity, LPG and wage inflation.
Over the past 52 weeks, Jubilant Foodworks Ltd has traded between a low of ₹400.30 and a high of ₹622.50. The 52-week high and low indicate the stock’s price range over the last year and help investors understand its volatility and recent trading levels.
Jubilant Foodworks Ltd has a market capitalization of approximately 26,908.49. Market capitalization represents the total value of a company’s outstanding shares and helps investors understand its size, stability, and relative risk compared to other listed companies.
Jubilant Foodworks Ltd’s investment profile depends on its business fundamentals, valuation, and long-term outlook. The stock currently trades at a PE ratio of 70.89 and operates in the its sector sector. Investors typically assess financial performance, growth prospects, and individual risk tolerance before making investment decisions.
Based on its market capitalization of 26,908.49 Cr, Jubilant Foodworks Ltd is classified as a Small Cap stock. Large-cap stocks are generally more stable, while mid-cap and small-cap stocks tend to offer higher growth potential along with higher price volatility.
Jubilant Foodworks Ltd operates in the its sector sector. Sector classification matters because companies in the same sector are often affected by similar economic conditions, regulatory changes, and competitive dynamics, which can influence overall stock performance.
The Price-to-Earnings (PE) ratio of Jubilant Foodworks Ltd is 70.89. The PE ratio compares a company’s share price to its earnings and is commonly used to assess valuation. Comparing the PE ratio with sector peers and historical levels provides better context.
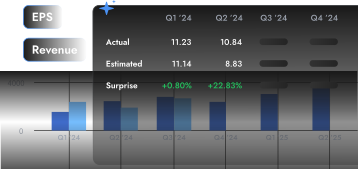
The company reported consolidated revenue from operations of ₹2,261.4 crore in Q1 FY26, up 17% year-on-year.
The stock fell as investors focused on Domino’s India like-for-like growth of just 0.2%, operational disruption from LPG supply issues, and margin pressure concerns, despite a 66% YoY profit rise.
The stock fell up to about 8% as brokerages highlighted near-term margin pressure from LPG, labour and commodity inflation, along with weaker dine-in trends and slower demand indicators.
The stock fell as management highlighted near-term inflationary pressures in labour, utilities and logistics, and brokerages cut earnings estimates despite higher profit and revenue.


| Symbol | Watchlist | Price | Market Cap | P/E | P/B | Div Yield (%) | ROE (%) | ROCE (%) | ROA (%) |
407.80 | 26,908 Cr | 70.89 | 11.74 | 0.29 | 18.69 | 13.86 | 4.71 | ||
1176.30 | 15,494 Cr | 31.87 | 10.74 | 0.87 | 30.57 | 38.98 | 21.32 | ||
116.25 | 14,333 Cr | -514.46 | 9.30 | 0.00 | -1.32 | 4.46 | -0.41 | ||
533.95 | 8,326 Cr | 262.66 | 13.45 | 0.14 | 0.83 | 5.77 | 1.12 | ||
87.55 | 6,235 Cr | -32.53 | 3.84 | 0.00 | -25.94 | -0.53 | -5.67 | ||
192.95 | 6,201 Cr | -382.78 | 4.46 | 0.00 | -1.04 | 3.89 | -0.50 | ||
634.70 | 2,483 Cr | -57.85 | 8.00 | 0.00 | -19.06 | 1.49 | -2.99 | ||
| Median: 7 Co. | — | 407.80 | 8,326 Cr | -32.53 | 9.30 | 0.00 | -1.04 | 4.46 | -0.41 |
Jubilant FoodWorks Limited is India’s largest food‑service company operating brand‑owned and franchised Quick Service Restaurant (QSR) concepts including Domino’s Pizza, Popeyes (master franchise rights), ChefBoss packaged foods, and other brand initiatives; the company runs an extensive store network supported by commissaries, a Jubilant Food park and dedicated technology platforms.
Popeyes has emerged as a second growth engine with dramatic acceleration: same‑store dynamics show LFL growth jumping from single digits to roughly 40%–45% in the latest quarter, driven by product differentiation, supply‑chain integration and focused store execution, making Popeyes an important near‑term contributor to JFL’s top‑line expansion and margin potential.
Management reiterated disciplined capital allocation with FY27 capex guidance of INR 750–900 crore concentrated on new stores, selective store upgrades (dine‑in focus) and technology investments rather than large new supply chain builds, while earlier commissaries and Mumbai food factory commissioning improve supply economics and allow JFL to ‘sweat’ existing assets for better returns.
Margin and free cash flow focus: JFL reported healthy gross margins (around 75.5% in the quarter), turned free cash flow positive in FY26 and is pursuing a 200bp structural improvement plan split between Domino’s and emerging brands while balancing calibrated pricing, cost efficiencies and selective marketing to protect profitability amid commodity, LPG and wage inflation.
Leisure Services
Restaurants
26,691 Cr
High Risk
70.3
35.2
3.1
11.7
622.50
400.30
Sales CAGR
Profit CAGR
ROE
ROCE