










ARSS Infrastructure Projects plans Rs 550 crore promoter issue
Key highlights
- ARSS Infrastructure Projects proposes up to Rs 550 crore of unsecured promoter-funded preference shares.
- Dipti Ranjan Patnaik is allocated up to Rs 500 crore and Ocean Capital Market Limited up to Rs 50 crore.
- Each preference-share tranche would run for 22 months and target a 10% annual IRR through redemption premium.
- ARSS Infrastructure Projects reported total assets of Rs 1,263.9234 crore at September 30, 2026.
powered by IRIS
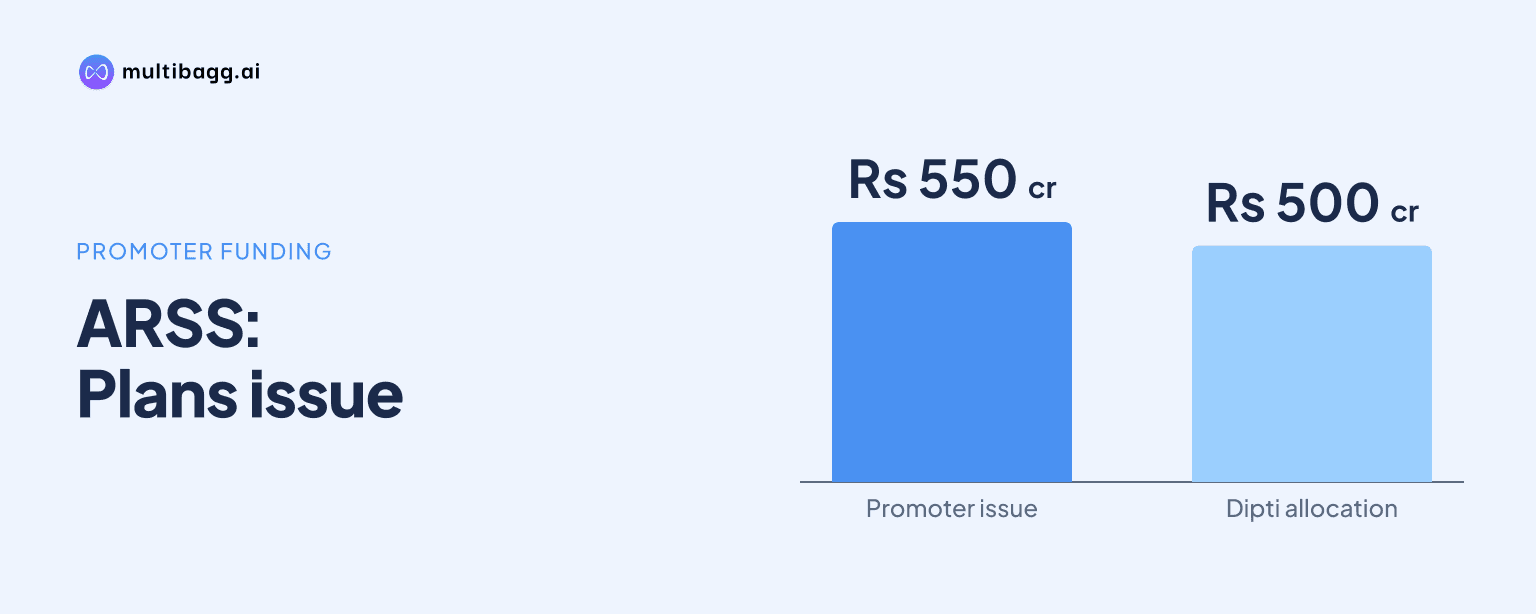
ARSS Infrastructure Projects Limited plans to issue up to Rs 550 crore of unsecured, unlisted preference shares to two promoters, with each tranche redeemable after 22 months at a premium designed to deliver a 10% annual internal rate of return. The private placement includes Rs 500 crore for Dipti Ranjan Patnaik and Rs 50 crore for Ocean Capital Market Limited.
Know ARSS Infrastructure Projects inside out
Results, valuation, peers and who's buying, in one view.
What is ARSS Infrastructure Projects proposing to issue?
ARSS Infrastructure Projects is proposing non-cumulative, non-convertible redeemable preference shares, or NCRPS, through a private placement to its promoters. The company disclosed a maximum issue size of Rs 550 crore, comprising shares with a face value of Rs 10 each. The securities are not proposed to be listed under the Regulation 30 disclosure.
The proposed issue has two investor allocations, totalling 55 crore preference shares. Ocean Capital Market Limited may receive up to 5 crore shares for Rs 50 crore, while Dipti Ranjan Patnaik may receive up to 50 crore shares for Rs 500 crore. The board may allot the shares in one or more tranches after obtaining shareholders' approval, rather than on one specified allotment date.
The funding structure is preference-share funding rather than an issue of ordinary equity shares. The instruments are explicitly non-convertible and redeemable, with a 22-month tenure from the allotment date of each tranche. The disclosure identifies the securities as non-cumulative NCRPS with a Rs 10 face value.
Who will provide the Rs 550 crore to ARSS Infrastructure Projects?
The proposed Rs 550 crore will come from Dipti Ranjan Patnaik and Ocean Capital Market Limited, both identified in the filing as promoters of ARSS Infrastructure Projects. Dipti Ranjan Patnaik has the larger allocation of up to Rs 500 crore, or 50 crore preference shares, while Ocean Capital Market Limited has up to Rs 50 crore, or 5 crore shares.
Both proposed placements have the same Rs 10 face value per share, 22-month tenure and 0.01% annual non-cumulative dividend. The announcement does not identify a bank, institutional investor or public subscriber for the Rs 550 crore issue. It describes promoter funding through an unlisted private placement that remains subject to shareholder approval and board decisions on allotment tranches.
The terms give preference shareholders a preferential right over equity shareholders for payment of dividends, if any, and repayment of capital in accordance with the Companies Act, 2013. The filing states that no other special rights, interests or privileges apply beyond this preference over equity shares.
Got a follow-up? Ask IRIS
How will the preference shares pay and redeem?
ARSS Infrastructure Projects' proposed NCRPS carry a 0.01% annual non-cumulative dividend on the Rs 10 face value, payable annually if declared, and a redemption premium intended to produce a 10% annual internal rate of return, or IRR. The stated return includes the premium payable at redemption, rather than only the annual dividend.
Each tranche will have a tenure of 22 months from its individual allotment date. At the end of that period, ARSS Infrastructure Projects proposes to redeem the NCRPS at a premium sufficient to provide preference shareholders with the disclosed 10% per annum IRR. The filing does not state the rupee amount of the redemption premium or the final redemption value per share.
The preference shares will be unsecured and will not carry any charge over ARSS Infrastructure Projects' assets. The disclosure marks as not applicable the item concerning payment delays exceeding three months or defaults in interest or principal, as well as the item concerning letters or comments on payment or non-payment.
ARSS Infrastructure Projects obtained a valuation report dated July 23, 2026, from CA Prithvi Ranjan Parhi, a registered valuer for securities or financial assets. The filing says the valuer issued a certificate in relation to the proposal, but does not disclose a per-share valuation, the premium amount or a final cash redemption figure.
How does the proposed funding compare with ARSS Infrastructure Projects' balance sheet?
ARSS Infrastructure Projects reported consolidated total assets of Rs 1,263.9234 crore at September 30, 2026, compared with Rs 1,273.8346 crore at March 31, 2026. During the same period, non-current borrowings rose to Rs 278.7186 crore from Rs 258.1222 crore, while current borrowings declined to Rs 4.1023 crore from Rs 5.6574 crore.
The proposed Rs 550 crore preference-share issue is separate from the Rs 90.1185 crore equity share capital reported at both September 30, 2026 and March 31, 2026. It is also distinct from the reported borrowing balances because the proposed security is a preference share, although its terms require redemption after 22 months and specify a 10% annual IRR target.
ARSS Infrastructure Projects reported a consolidated loss of Rs 18.9682 crore for the half year ended September 30, 2026, compared with a loss of Rs 3,342.9252 crore in the corresponding half year ended September 30, 2025. The filing does not disclose how proceeds from the proposed Rs 550 crore preference-share issue would be used, so no specific deployment of the funds is stated.
Conclusion
The proposed transaction would provide ARSS Infrastructure Projects with up to Rs 550 crore from its two disclosed promoters through unsecured, unlisted NCRPS. The economic terms combine a 0.01% annual non-cumulative dividend with a redemption premium intended to provide a 10% annual IRR after 22 months, while giving holders preference over equity shareholders for dividends, if any, and capital repayment.
The next disclosed steps are shareholder approval and board decisions on whether allotments occur in one or more tranches. The matters to watch are the eventual allotment dates, the amount issued in each tranche, and any later disclosure of the redemption premium or proposed use of proceeds; the filing provides a valuation-report date of July 23, 2026 but no final allotment schedule.