










Ashapura Minechem Guinea exports fall 48% as EBITDA drops
Key highlights
- Ashapura Minechem's Guinea bauxite exports fell to 1.21 MMT in Q2 FY 2026-27 from 2.34 MMT in Q1.
- Ashapura Minechem's Guinea EBITDA per metric tonne declined to $5.3 in Q2 from $6.3 in Q1.
- Ashapura Minechem's Q2 FY 2026-27 income from operations rose 11.6% to Rs 1,063.4 crore.
- Ashapura Minechem's Q2 FY 2026-27 profit before tax declined 4.2% to Rs 77.8 crore.
powered by IRIS
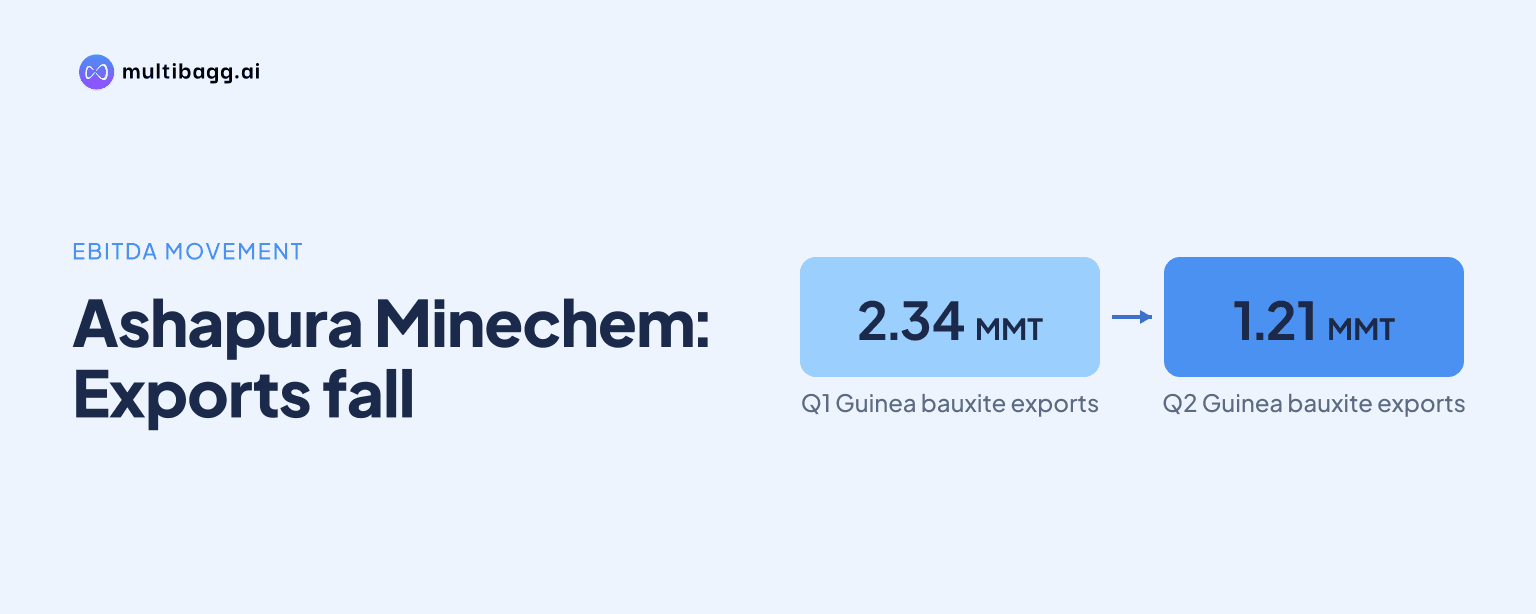
Ashapura Minechem Limited reported Guinea bauxite exports of 1.21 million metric tonnes in Q2 FY 2026-27, 48.3% below 2.34 million metric tonnes in Q1, while EBITDA per metric tonne fell to $5.3 from $6.3. The company attributed lower dispatches primarily to seasonal monsoon conditions, with higher ocean freight and fuel prices also affecting performance.
Know Ashapura Minechem inside out
Results, valuation, peers and who's buying, in one view.
Why did Ashapura Minechem's Guinea bauxite exports fall in Q2 FY 2026-27?
Ashapura Minechem said Q2 FY 2026-27 dispatches from Guinea were lower than Q1 primarily because of seasonal monsoon conditions. Its bauxite export volume was 1.21 million metric tonnes, or MMT, in the second quarter, compared with 2.34 MMT in the first quarter. That is a sequential reduction of 1.13 MMT, or 48.3% when calculated from the disclosed volumes.
The Q2 result was also below the corresponding quarter a year earlier. Guinea bauxite exports were 1.33 MMT in Q2 FY 2025-26, against 1.21 MMT in Q2 FY 2026-27, a decline of 0.12 MMT or 9.0%. The filing identifies the weather-related impact specifically in relation to lower dispatches compared with Q1, rather than setting out a separate explanation for the year-on-year change.
How much did Ashapura Minechem's Guinea EBITDA per tonne decline?
Ashapura Minechem reported EBITDA of $5.3 per metric tonne, or PMT, for Guinea bauxite exports in Q2 FY 2026-27, down $1.0 PMT from $6.3 in Q1 FY 2026-27. This represents a 15.9% sequential decline based on the figures disclosed, alongside the 48.3% reduction in exported volume.
Against Q2 FY 2025-26, the per-tonne figure fell $3.6 PMT from $8.9 to $5.3, a 40.4% decline. Ashapura Minechem said higher costs for ocean-going vessel freight and increased fuel prices adversely affected its performance. The filing does not quantify how much of the $1.0 PMT sequential change came from freight, fuel, monsoon-related volumes or other factors.
What were Ashapura Minechem's consolidated Q2 financial results?
Ashapura Minechem's consolidated income from operations rose 11.6% year on year to Rs 1,063.4 crore in Q2 FY 2026-27, from Rs 952.5 crore in Q2 FY 2025-26. EBITDA increased to Rs 137.7 crore from Rs 132.1 crore over the same periods, while profit before tax declined to Rs 77.8 crore from Rs 81.2 crore.
The contrasting movement between revenue and profit before tax is relevant to the Guinea update because Ashapura Minechem cited lower bauxite dispatches, higher ocean freight and fuel prices as factors that adversely affected overall performance. Income from operations increased by Rs 110.9 crore, whereas profit before tax decreased by Rs 3.4 crore. The release does not provide a segment-level reconciliation from Guinea's $5.3 PMT EBITDA to consolidated profit before tax.
The reported Q2 figures cover the quarter ended September 30, 2026, and were announced in Mumbai on November 5, 2026. They are consolidated figures, meaning they incorporate the parent company, subsidiaries, associates and joint ventures as applicable, while the Guinea metrics in the release relate specifically to bauxite export volumes and EBITDA per metric tonne.
Got a follow-up? Ask IRIS
What does Ashapura Minechem's first-half result show?
Ashapura Minechem reported income from operations of Rs 2,679.5 crore for H1 FY 2026-27, up 16.1% from Rs 2,308.1 crore in H1 FY 2025-26. H1 refers to the six months ended September 30, 2026. The first-half revenue increase of Rs 371.4 crore was larger in percentage terms than the Q2 increase of 11.6%.
First-half EBITDA was Rs 326.6 crore, compared with Rs 319.9 crore a year earlier, while profit before tax declined 2.5% to Rs 207.8 crore from Rs 213.1 crore. Revenue and EBITDA rose during the six-month period, but profit before tax was lower. Ashapura Minechem's release cited freight and fuel costs as factors that adversely affected performance.
The filing provides both H1 and Q2 comparisons with prior-year periods but does not disclose a standalone Q1 consolidated income or profit before tax figure in this announcement. It does, however, provide the Q1 FY 2026-27 Guinea operating comparison of 2.34 MMT of exports and $6.3 PMT of EBITDA, allowing the sequential movement in the bauxite business to be measured directly.
Which businesses contribute to Ashapura Minechem's reported performance?
Ashapura Minechem classifies its operations into Bauxite and Iron Ore in Guinea; Bentonite and Allied Minerals, White Performance Materials and Others in India; Specialty Adsorbent Solutions through Ashapura Perfoclay Limited; and Advanced Ceramic Materials through Orient Ceratech Limited. The Guinea disclosure of 1.21 MMT in Q2 FY 2026-27 relates to the first of these classifications.
Ashapura Minechem stated that Ashapura Perfoclay Limited is a 50% joint venture, so only 50% of its displayed bottom line is added to Ashapura Minechem's consolidated accounts. It also stated that Orient Ceratech Limited is a 32.07% associate, with only 32.07% of its displayed bottom line added to the consolidated accounts. These ownership treatments mean the operational classifications are not necessarily reflected in consolidated results on a 100% basis.
The auditor's review report covers the quarter and year-to-date period from April 1, 2026 to September 30, 2026. It listed 21 subsidiaries whose reviewed interim results included total gross revenue of Rs 1,483.31 crore for the quarter and Rs 3,796.48 crore for the half year, illustrating the broader group structure behind the consolidated announcement.
Conclusion
Ashapura Minechem's Q2 FY 2026-27 release shows that Guinea bauxite exports were materially lower sequentially, falling from 2.34 MMT to 1.21 MMT, while EBITDA per tonne declined from $6.3 to $5.3. At the consolidated level, Q2 income from operations rose 11.6% to Rs 1,063.4 crore, but profit before tax fell 4.2% to Rs 77.8 crore as the company cited dispatch, freight and fuel pressures.
Investors will next be able to assess management's discussion of the 1.21 MMT volume and $5.3 PMT outcome at Ashapura Minechem's planned investor call on November 13, 2026 at 4:00 p.m. The company said a formal announcement on the call would be communicated to the exchanges; the release did not disclose an export-volume target, freight-cost outlook or timetable for any recovery in Guinea dispatches.