










Aurionpro data-centre orders top 30%, lifting cash strain
Key highlights
- Aurionpro said data-centre contracts exceeded 30% of its order book of more than Rs 2,000 crore.
- Management expects Aurionpro's data-centre business to grow 70%-80% or more in FY27.
- An analyst cited current borrowings of about Rs 150 crore, versus roughly Rs 50 crore in March.
- Management expects an enterprise margin range of 17%-18% in FY27 and FY28 under current assumptions.
powered by IRIS
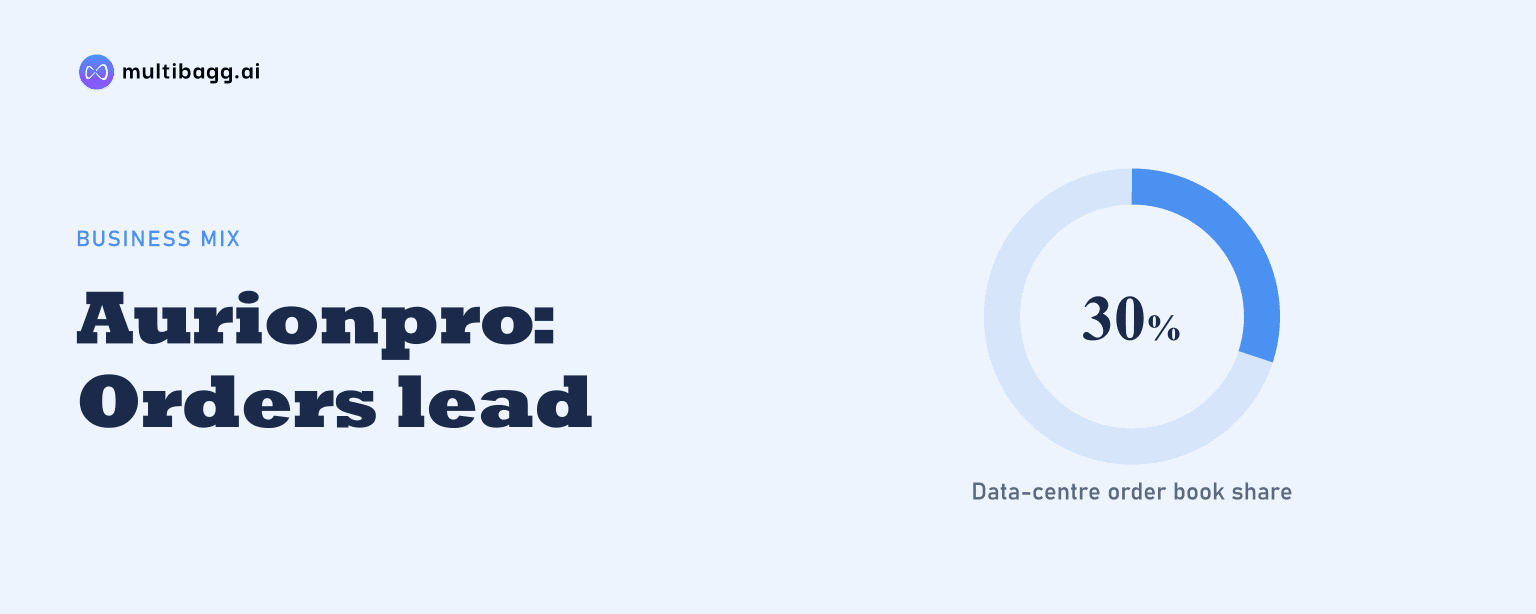
Aurionpro Solutions Limited said on November 2, 2026 that data-centre contracts exceeded 30% of its order book of more than Rs 2,000 crore, but the rapid build-out is creating near-term cash pressure. Management expects the data-centre business to grow 70%-80% or more in FY27, with costs currently running ahead of revenue from recently won large contracts.
Know Aurionpro Solutions inside out
Results, valuation, peers and who's buying, in one view.
How large is Aurionpro's data-centre order book?
Aurionpro said data-centre contracts accounted for more than 30% of an order book exceeding Rs 2,000 crore entering H2 FY27. Management described the broader order-book split as roughly two-thirds in the Technology Innovation Group, or TIG, and one-third in banking and fintech, with data centres housed in TIG alongside transit activity.
The data-centre share of TIG is also rising. Management said data centres represented about one-third of TIG in the prior year and could account for about 40%-50% of TIG in FY27. Aurionpro does not disclose data-centre revenue separately, so it did not give an H1 FY27 revenue figure for the business.
Order-book share does not equate directly to immediate revenue share. Management said banking and fintech contracts execute faster, while data-centre mandates are larger and require capacity to be built for time-bound delivery. It said data-centre revenue grew in H1 FY27 but should grow more strongly in H2 FY27.
Why are Aurionpro's data-centre projects straining cash?
Aurionpro said one or two very large data-centre contracts created point-in-time working-capital pressure in FY27. An analyst on the call said current borrowings had increased to about Rs 150 crore from roughly Rs 50 crore in March, while cash had declined to around Rs 83 crore; management linked the movement chiefly to the scale of these data-centre deals.
The recent contracts have started contributing a little revenue, but management said their more immediate effect has been pressure on cash and borrowings. It said costs are ahead of revenue and described a need to retool the enterprise for contracts larger than those Aurionpro had previously delivered.
Management expects the pressure to ease through execution rather than persist as a structural cash issue. It said Aurionpro should be in a better position on cash, profit and revenue by the end of FY27, while stressing that the outcome depends on H2 execution and delivery of the planned growth.
Can Aurionpro convert more profit into operating cash flow?
Aurionpro said operating cash flow, or OCF, equal to 60%-70% of earnings before interest, taxes, depreciation and amortisation, or EBITDA, is achievable in FY27. Management said collections in its business are usually weighted toward Q3 and Q4, making the second half especially important after negative OCF in H1 FY27, as cited by an analyst.
Management identified growth opportunities as the principal variable around that cash-conversion objective. It said incremental investment could be required if opportunities expand across banking, transit or data centres, although it would discuss any such investment transparently. The company did not provide a FY27 company-wide revenue-growth target.
The data-centre cash requirement is tied to delivery rather than a disclosed plan to own data-centre capacity. Management said the global sector is in a major capital-expenditure cycle but reiterated that Aurionpro intends to remain capital-light, serving hyperscalers, artificial-intelligence clouds and banks through design, engineering, components and execution.
Got a follow-up? Ask IRIS
Will data-centre growth hold back Aurionpro's margins?
Aurionpro expects data-centre revenue to grow 70%-80% or more in FY27, faster than its other units, and said this mix shift should limit enterprise-level margin expansion. Management said data-centre margins are currently below enterprise margins, even as banking and fintech and transit are expected to improve in H2 FY27.
Management said it currently expects an enterprise margin range of 17%-18% for FY27 and FY28. It said banking and fintech margins in H1 FY27 were at, or slightly above, its expected level, while transit margins had been trending upward, but the larger contribution from data centres could offset those improvements in the consolidated mix.
The margin outcome could differ if data-centre revenue grows substantially beyond the current plan. Management used a hypothetical increase to 100% growth instead of 70% as an example of a scenario that could add pressure to the margin percentage because the lower-margin activity would represent a larger share of revenue.
How does Aurionpro plan to improve data-centre economics?
Aurionpro plans to add more internally developed and manufactured products to data-centre contracts over several quarters to several years. Management said the business is at a stage similar to transit about four years ago: Aurionpro has visibility across the component value chain and is seeking to introduce more of its own products into it.
Management cited prefabricated, or prefab, offerings among its research and development priorities. It said each proprietary product incorporated into a contract should improve the margin profile, but described this as a progressive process rather than an immediate FY27 change. The plan uses the company's engineering, research and development, and manufacturing capabilities.
Aurionpro said its broader strategy combines intelligent software with precision hardware, which it calls an atoms-to-bits approach. For data centres, management said the immediate focus is helping customers bring capacity online faster and more predictably, while product development is intended to increase the company's role in contract value over time.
What will determine Aurionpro's H2 FY27 data-centre conversion?
Aurionpro said delivery capacity is the key variable for converting data-centre orders into FY27 revenue. Management said these are time-bound projects, leaving limited flexibility if capacity is not available when required, although it expects meaningful data-centre growth and conversion in H2 FY27.
Management did not quantify H2 FY27 growth but said H2 should be much stronger than H1. It pointed to a 16% expansion from Q1 to Q2 FY27 and said each quarter should become stronger through the year, while cautioning that later quarters may not expand at the same pace.
Capacity released in banking and fintech could support broader order conversion. Management said major AI-native product build-outs are approaching their later stages and it has not added development capacity for several quarters, citing productivity gains from new tools. It expects more of that capacity to shift to revenue-earning projects in H2 FY27.
Conclusion
Aurionpro's data-centre operation has become a material part of its more than Rs 2,000 crore order book, with management expecting 70%-80% or higher FY27 growth. The near-term trade-off is visible in cash and borrowing pressure from large-contract execution, while the business's current margin profile limits the scope for enterprise-level margin expansion despite improvement expected in other units.
The next indicators are H2 FY27 revenue conversion, OCF-to-EBITDA conversion toward management's 60%-70% objective, and the scale of any further data-centre wins. Management also said data-centre disclosure could become a separate reported number in the near future if the business gains sufficient scale and predictability, while proprietary-product development will take several quarters to several years.