










Bansal Roofing Products Ltd Revenue Rises 27% in Q1 FY27
Key highlights
- Bansal Roofing Products Ltd reported Q1 FY27 revenue from operations of ₹45.89 crore, up 26.78% year on year.
- Q1 FY27 net profit rose 31.93% year on year to ₹2.66 crore, while EBITDA increased 35.0% to ₹4.12 crore.
- FY26 revenue was ₹154.43 crore, up 59.60% from ₹96.76 crore in FY25.
- The board is scheduled to consider Q2 FY27 and H1 FY27 unaudited results on November 4, 2026.
powered by IRIS
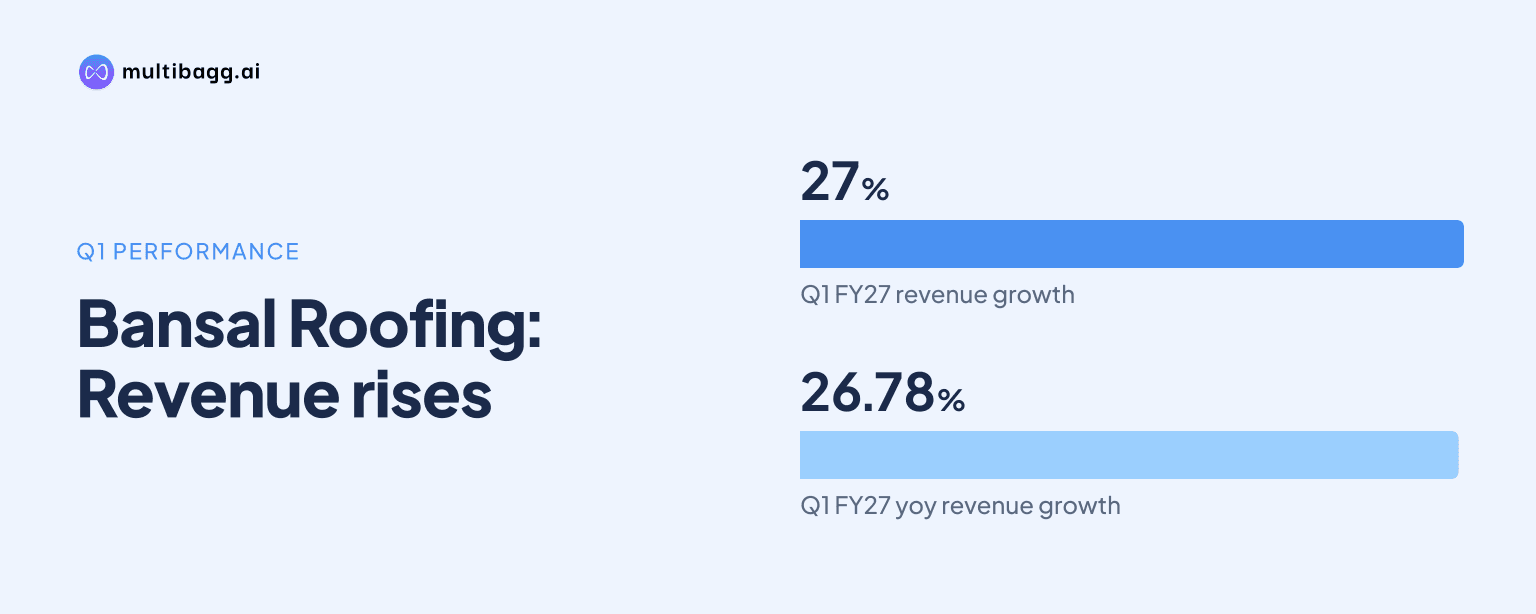
Bansal Roofing Products Ltd reported revenue from operations of ₹45.89 crore in the quarter ended June 30, 2026, up 26.78% year on year, while net profit increased 31.93% to ₹2.66 crore. The Q1 FY27 performance followed FY26 revenue growth of 59.60% to ₹154.43 crore and preceded the board's consideration of Q2 FY27 results.
Know Bansal Roofing Products inside out
Results, valuation, peers and who's buying, in one view.
What did Bansal Roofing Products Ltd report for Q1 FY27?
Bansal Roofing reported standalone revenue from operations of ₹45.89 crore for Q1 FY27, compared with ₹36.20 crore in the corresponding quarter a year earlier. Net profit rose to ₹2.66 crore from ₹2.02 crore, while EBITDA increased to ₹4.12 crore from ₹3.05 crore. The detailed quarterly statement placed basic and diluted earnings per share at ₹2.02, compared with ₹1.53 in Q1 FY26.
The company’s profit before tax was ₹3.57 crore, against ₹2.57 crore a year earlier. Tax expense stood at ₹90.68 lakh for the June 2026 quarter. The board approved the unaudited standalone results on August 10, 2026, after review by statutory auditors Parikh Shah Chotalia & Associates.
How did revenue and profit move from the March quarter?
Bansal Roofing’s supplied quarterly summary showed revenue of ₹45.96 crore for June 2026, compared with ₹45.35 crore in March 2026, an increase of 1.35% quarter on quarter. The detailed standalone result separately reported revenue from operations of ₹45.89 crore for June 2026. The minor difference is present in the supplied data, while both figures indicate that quarterly revenue remained close to the March-quarter level.
Profitability moderated sequentially. The quarterly summary listed operating profit at ₹3.57 crore in June 2026 versus ₹4.61 crore in March 2026, down 22.56%. It also listed profit at ₹2.66 crore, down 23.78% from ₹3.49 crore in the preceding quarter. These movements contrast with the year-on-year increase in Q1 revenue, EBITDA and net profit.
What is driving Bansal Roofing’s operating performance?
Bansal Roofing attributed the Q1 FY27 revenue expansion to higher sales volumes and capacity additions. Its pre-engineered buildings, or PEB, operations were operating at 80.9% utilisation, according to the information provided. The company also cited a ₹24 crore order as part of the PEB business activity supporting execution during the period.
The company commissioned a solar module mounting structure, or MMS, line with stated capacity of 2,500 metric tonnes per month. Management indicated that solar MMS operations offer net margins of about 2.5% to 3%. It also said solar revenue had not been included in its FY27 revenue guidance, making the new line relevant to operating scale but not yet embedded in the published revenue projection.
PEB capacity was expected to reach 15,000 tonnes per annum by mid-September 2026. However, utilisation was lower in other operations, with roofing at 50.7% and decking at 9.2%. These figures show that capacity expansion and utilisation levels differ across the company’s product lines.
Got a follow-up? Ask IRIS
What does the FY26 performance show?
Bansal Roofing reported FY26 revenue of ₹154.43 crore, compared with ₹96.76 crore in FY25. That represents annual revenue growth of 59.60%. The rise provides the base for management’s FY27 projection of ₹180 crore to ₹200 crore, which implies growth of 25% to 32% over the FY26 figure.
The historical quarterly revenue series also shows an expansion from ₹36.21 crore in June 2025 to ₹45.96 crore in June 2026 in the summary data. Revenue was ₹45.35 crore in March 2026 and ₹38.69 crore in December 2025. These figures indicate that reported quarterly sales were higher in the latest reported periods than in the comparable quarters of the previous year.
Management described its FY27 revenue range as conservative because solar MMS revenue was excluded from the projection. This is a management view rather than an assured outcome. The disclosed projection remains the company’s stated outlook and should be assessed alongside actual quarterly execution and margins.
When will Bansal Roofing consider its September-quarter results?
Bansal Roofing scheduled a board meeting for November 4, 2026, through video conference to consider and approve unaudited standalone financial results for the quarter and half year ended September 30, 2026. The agenda also includes adoption of the auditors’ Limited Review Report. The company said the information would be hosted on its website.
The trading window for designated persons and their immediate relatives was closed from October 1, 2026. It will reopen 48 hours after the board approves the financial results, in line with the SEBI (Prohibition of Insider Trading) Regulations, 2015. The closure covers the Q2 FY27 and H1 FY27 reporting period.
The upcoming results will provide the next reported update on the company’s FY27 guidance, PEB capacity additions and the initial contribution from solar MMS operations. The supplied information also identifies working-capital risk, with solar receivable days stated at 30 to 45 days compared with below 14 days earlier, as well as the company’s first debt of ₹5 crore to ₹6 crore.
How does the result matter for investors and operations?
The Q1 result showed that revenue and net profit grew faster than the comparable quarter a year earlier, with EBITDA growth of 35.0% exceeding revenue growth of 26.78%. At the same time, the quarter-on-quarter data showed lower reported profit than in the March 2026 quarter. Investors therefore have both year-on-year growth and sequential profitability data to consider.
Capacity additions could influence the company’s production mix and revenue base, especially in PEB and solar MMS. But the disclosed margin profile for solar MMS, lower utilisation in roofing and decking, and longer solar receivable periods are relevant operating factors. The stated debt of ₹5 crore to ₹6 crore also marks a change in the company’s funding position.
Conclusion
Bansal Roofing Products Ltd entered FY27 after reporting FY26 revenue growth of 59.60% and a Q1 FY27 increase of 26.78% in revenue from operations. Net profit rose 31.93% year on year to ₹2.66 crore, supported by higher sales volumes and PEB execution, although the supplied sequential figures showed a decline in profit from the March quarter.
The next disclosed event is the November 4, 2026 board meeting for unaudited standalone Q2 FY27 and half-year results. Investors will watch reported progress against the ₹180 crore to ₹200 crore FY27 revenue guidance, PEB capacity expansion, solar MMS contribution, utilisation levels and the stated receivables and debt position.