










Bench Mark Infotech H1 EBITDA margin rises to 23.9% on mix
Key highlights
- Bench Mark Infotech's H1 FY27 EBITDA margin rose to 23.9% from 10.5% in H1 FY26.
- Operational EBITDA increased to Rs 3.36 crore from Rs 1.48 crore despite Rs 14.05 crore of H1 FY27 total income.
- Management said project margins can range from 12% to 30%, depending on scope and competition.
- Bench Mark Infotech reported an open tender pipeline of Rs 74 crore on November 18, 2026.
powered by IRIS
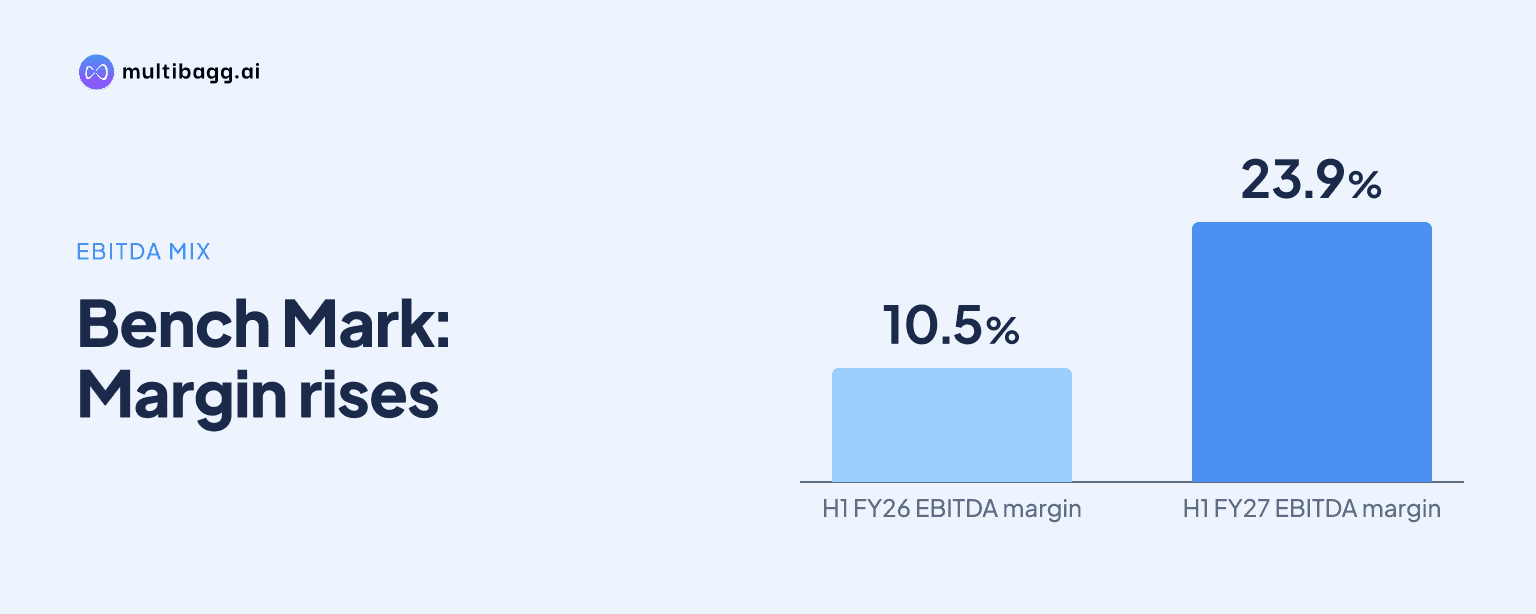
Bench Mark Infotech Services Limited reported a 23.9% EBITDA margin for H1 FY27 ended September 30, 2026, up from 10.5% a year earlier, as lower material content and more technically complex, service-led projects lifted operational EBITDA to Rs 3.36 crore despite total income of Rs 14.05 crore.
Know Bench Mark Infotech Services inside out
Results, valuation, peers and who's buying, in one view.
How much did Bench Mark Infotech's H1 profitability improve?
Bench Mark Infotech's operational EBITDA, or earnings before interest, tax, depreciation and amortisation, rose to Rs 3.36 crore in H1 FY27 from Rs 1.48 crore in the prior-year half, while its EBITDA margin increased by 13.4 percentage points to 23.9% from 10.5%. The increase in EBITDA was about 127% even though management described H1 total income of Rs 14.05 crore as broadly in line with last year.
The comparison shows that the reported change was chiefly in profitability rather than first-half sales volume. Management presented the margin result on its November 18, 2026 earnings call after the half year ended September 30, 2026, and said the company had received projects with a different cost composition from those executed in the preceding year.
Why did Bench Mark Infotech's EBITDA margin rise despite flat revenue?
Bench Mark Infotech said the margin expanded because H1 FY27 projects had lower material costs and higher service content than the previous year's work. Management attributed this mix to contracts requiring more complicated technology and services, supported by its technical team, rather than to a stated increase in total income beyond the reported Rs 14.05 crore.
Its stated offering includes data security, cyber security, networking, wireless communication, geographic information system mapping and audio-visual work. The company said the projects won during the half were more service-related than material-related, reducing the share of costs tied to supplied equipment and increasing EBITDA to Rs 3.36 crore.
Management did not set a single sustainable EBITDA-margin target. Instead, it said project-level margins can range from 12% to 30%, with examples including 15%, 18%, 20%, 22% and 25%, depending on the work scope and competitive conditions. That range means the 23.9% H1 FY27 result reflects the projects being executed, not a fixed margin applicable to every business vertical.
Is Bench Mark Infotech's first half normally smaller than its second half?
Yes, Bench Mark Infotech said its first half is seasonally smaller because project milestones and government billings tend to cluster in the second half. Management said H1 represented around 23% of full-year revenue in the prior year, which explains why it described Rs 14.05 crore of H1 FY27 income as broadly in line despite its expectation of more significant activity later in the fiscal year.
The company linked the expected H2 FY27 activity to its government-focused project model and said recurring service revenue grew in the first half. It also said it had disclosed orders of about Rs 80 crore including taxes, a figure management described as higher than last year, although it did not provide a period-by-period revenue forecast for the remaining months of FY27.
Management separately referred in its opening remarks to an order book of about Rs 66.60 crore. During the question session, an analyst cited Rs 86.93 crore as an outstanding order book as of November 2026, but management did not confirm that specific figure or specify how much would be executed in H2 FY27, saying only that it would try to execute a substantial portion of orders gathered.
Got a follow-up? Ask IRIS
What opportunities and risks could affect Bench Mark Infotech's margin next?
Bench Mark Infotech identified data security, complex networking solutions and integrated audio-video solutions as areas of stronger demand, while saying its data-centre and storage solutions could grow by 20% to 25% in the current year. Management also said it does not intend to make one vertical its primary business, preferring to add new technologies while retaining existing capabilities.
The company reported an open tender pipeline of Rs 74 crore as of the November 18 call and said a substantial portion could be monetised during the fiscal year. However, tender conversion, the eventual service-versus-material mix and the level of competition will determine whether new work resembles the H1 FY27 margin outcome of 23.9% or falls within management's broader 12% to 30% project-margin range.
A further planned area is graphics processing unit, or GPU, computing. Management said it intends to invest about Rs 100 crore in GPU computing in phases as customer demand develops, buying GPUs and renting services. It did not disclose an expected GPU margin because the business had not started, but said it expected to be competitive and to earn a decent margin.
Management said phased GPU deployment is intended to manage fluctuations in GPU hardware prices. It argued that falling hardware prices could lower rental prices but could also reduce procurement costs for capacity bought later; capacity under the Rs 100 crore plan would therefore vary with prevailing GPU prices. Management said any decision to use debt would be an internal management and board decision, noting that the company had historically been debt-free.
Conclusion
The H1 FY27 figures show that Bench Mark Infotech's profitability moved sharply even as revenue remained near the prior-year level: EBITDA rose from Rs 1.48 crore to Rs 3.36 crore and margin reached 23.9% from 10.5%. Management directly linked that movement to complex, service-heavy contracts carrying less material cost, while also making clear that project margins can vary from 12% to 30%.
The next evidence point is H2 FY27 execution, when management expects government project milestones and billings to be more concentrated. Investors can watch conversion of the Rs 74 crore open pipeline, progress on executing the disclosed order book, and the phased implementation of the planned Rs 100 crore GPU investment, for which management has not yet disclosed margins or capacity.