










Biocon Limited Q2 FY27 Revenue Seen at ₹4,600-4,700 Crore
Key highlights
- Biocon is scheduled to report Q2 FY27 results on November 4, 2026.
- Q2 FY27 total income is estimated at ₹4,600-4,700 crore, with EBITDA margin projected at 20-21%.
- Biocon reported Q1 FY27 revenue from operations of ₹4,336 crore, up 10.0% year on year.
- FY27 consensus revenue forecast was cut to ₹19,420 crore from ₹20,010 crore.
powered by IRIS
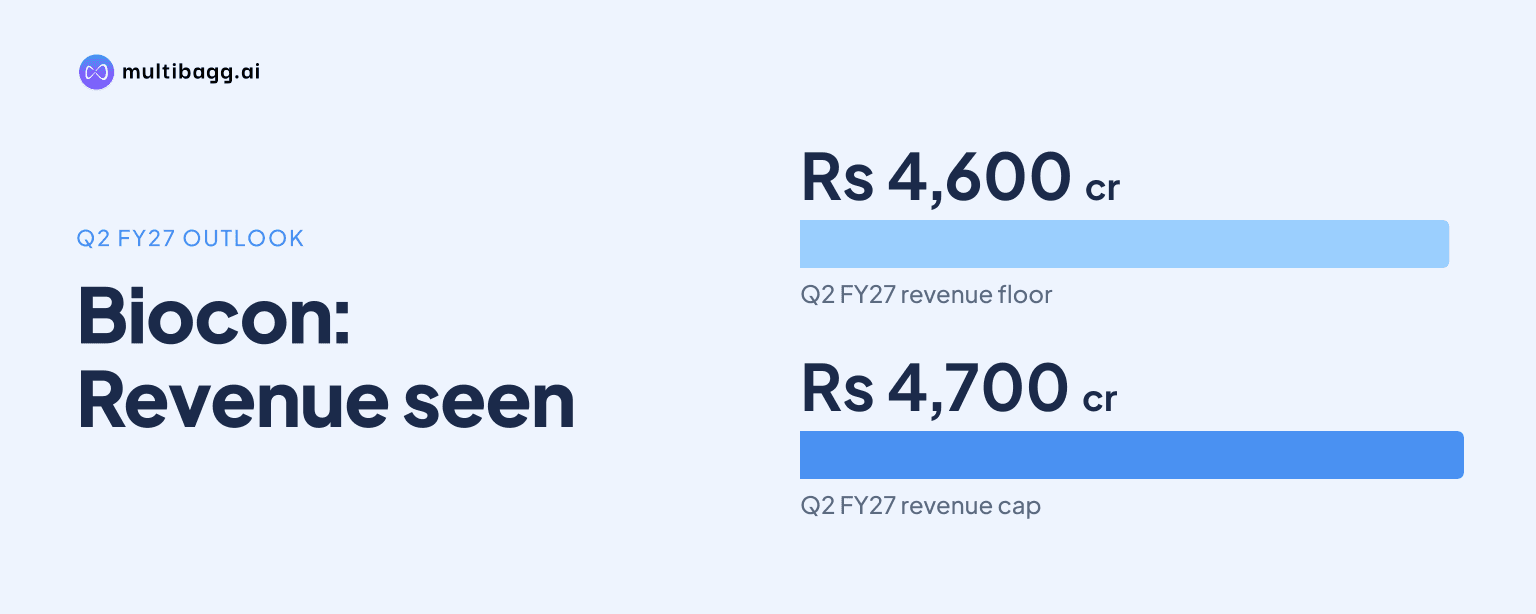
Biocon Limited is scheduled to report Q2 FY27 results on November 4, with total income estimated at ₹4,600-4,700 crore and EBITDA projected at ₹920-980 crore. The board is due to approve unaudited standalone and consolidated financial statements for the quarter and half-year ended September 30, 2026.
Know Biocon inside out
Results, valuation, peers and who's buying, in one view.
What is Biocon reporting on November 4?
Biocon is scheduled to announce its financial results for the July-September 2026 quarter, or Q2 FY27, on November 4, 2026. Its board will consider and take on record unaudited standalone and consolidated results for both the quarter and the half-year ended September 30.
The company has also scheduled an earnings conference call for the same day for analysts and investors. Biocon disclosed that its trading window would remain closed from October 1 through November 6, 2026. The timing places Biocon among several listed companies reporting September-quarter numbers on November 4, including Apollo Hospitals Enterprise, Dabur India, BSE, NHPC and Power Finance Corporation.
The key reported measures will include revenue, operating profitability, margins and profit after tax. These numbers will show whether momentum in the biopharmaceuticals business, including biosimilar launches, has continued during the September quarter.
What are the Q2 FY27 estimates for Biocon?
The available estimates indicate total income of about ₹4,600-4,700 crore for Q2 FY27, implying expected growth of 14-16%. EBITDA is estimated at approximately ₹920-980 crore, with an EBITDA margin of 20-21%, while net profit is expected in the ₹140-160 crore range.
The estimates follow a reported Q1 FY27 in which revenue from operations was ₹4,336 crore, up 10.0% year on year, and net profit was ₹137 crore, up 53.9% year on year. The source material also said group operating revenue rose 10% year on year in Q1, with the biopharmaceuticals segment growing 17%.
A ₹3.04 crore demand, comprising ₹1.86 crore of tax and ₹1.18 crore of interest under an October 10 order, has been identified as a factor that could affect reported profit. The available information does not provide the company’s final accounting treatment or the outcome of any response to the order.
Got a follow-up? Ask IRIS
How did Biocon perform before the September quarter?
Biocon entered Q2 after reporting an improvement in profitability in Q1 FY27. According to the provided data, net profit before exceptional items increased 245% year on year, supported by better generics profitability and lower interest costs.
The business mix was uneven. Biopharmaceuticals recorded 17% revenue growth in Q1 FY27, while the services segment faced a 16% decline in revenue. Management indicated that it expected momentum to build progressively during the year through biosimilar launches and expanded manufacturing capacity.
The company’s longer-term revenue trend has remained upward. Revenue increased from ₹8,024.8 crore in FY22 to ₹16,779.9 crore in FY26. However, quarterly performance has varied, and operating costs, product launches, research expenditure and capacity investments remain relevant to margin assessment.
Why are margins and earnings forecasts in focus?
Margins and the outlook for earnings are in focus because the consensus forecast for FY27 has been reduced. The revenue forecast has declined to ₹19,420 crore from ₹20,010 crore, while the earnings-per-share estimate has been cut to ₹6.95 from ₹8.27.
The estimate range for Q2 nonetheless assumes EBITDA margins close to the 21% level referenced for Q1 FY27. Sustaining that level would be relevant after research and development spending and capital expenditure associated with biosimilar launches. The September-quarter result will provide the next reported data point on these operating factors.
Biocon’s Q2 FY26 result provides a recent comparison point. It reported revenue of ₹4,296 crore and net profit of ₹133 crore for that quarter, and the share price reaction cited in the source was a 5.4% rise, from ₹385.1 to ₹405.9, following the November 12, 2025 release. That past move does not establish how the market will respond to the upcoming result.
What should investors assess in the Q2 FY27 release?
Investors will be able to assess the result against the stated revenue range of ₹4,600-4,700 crore, the 20-21% EBITDA margin expectation and the ₹140-160 crore profit estimate. The earnings call may also provide management’s commentary on biosimilar launches, manufacturing expansion, the services business and the tax demand.
The result will matter for how the market interprets the reduced FY27 earnings expectations. Revenue growth alone will not provide the full picture, since the operating margin, interest costs and profit conversion will determine whether the reported performance aligns with the expectations set before the announcement.
Conclusion
Biocon’s Q2 FY27 result is expected to provide an update on the progress of its biosimilar-led growth strategy and its ability to maintain operating profitability. Available estimates point to total income of ₹4,600-4,700 crore and EBITDA margin of 20-21%, following a Q1 marked by revenue growth and improved profit.
The main items to watch next are the board-approved September-quarter figures, the same-day earnings call and any management update on FY27 demand, margins, new launches, services-segment performance and the ₹3.04 crore tax and interest demand.