










CFF Fluid Control Limited retains 51% in proposed TKMS venture
Key highlights
- CFF Fluid Control approved the binding TKMS joint-venture agreement on 6 November 2026.
- CFF Fluid Control is proposed to own 51% of TKMS CFF Defence Systems Private Limited, while TKMS would own 49%.
- The proposed venture would cover local manufacturing, system integration and through-life support for anti-submarine warfare.
- The filing disclosed no agreement value, capital contribution, issue price or operational start date.
powered by IRIS
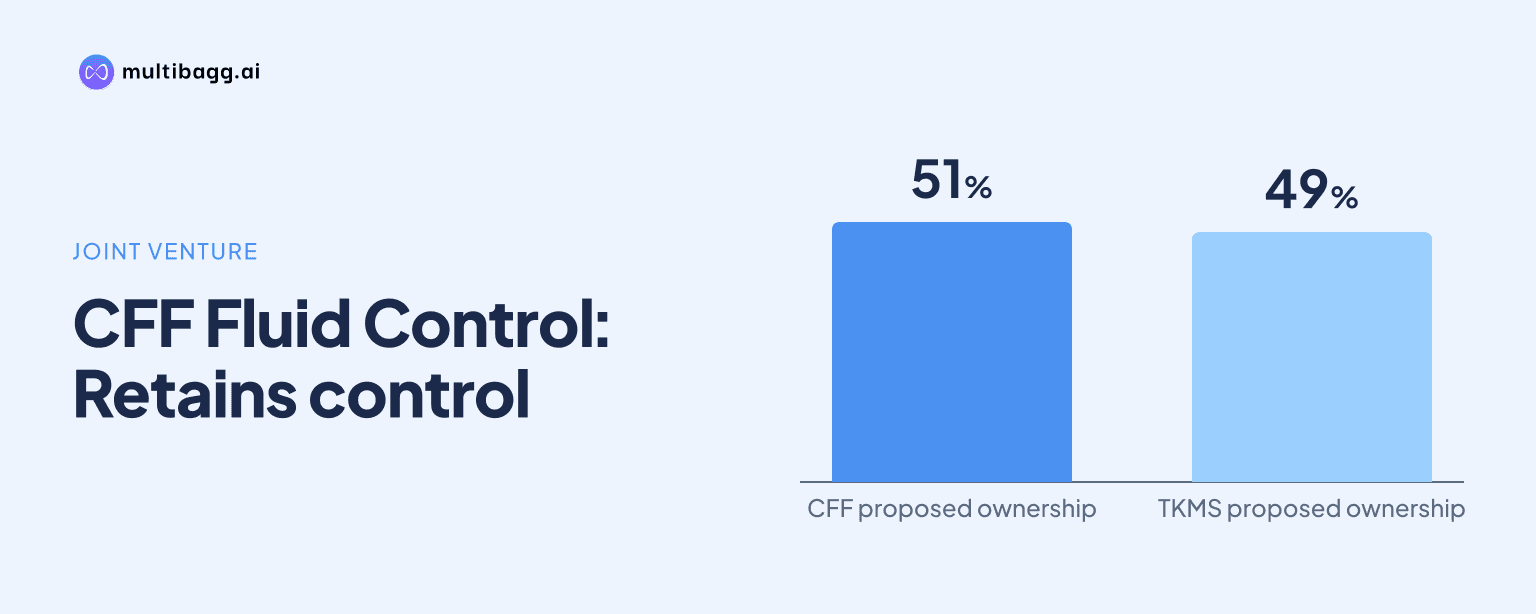
CFF Fluid Control Limited approved a binding joint-venture agreement on 6 November 2026 under which it is proposed to hold 51% of TKMS CFF Defence Systems Private Limited, with TKMS ATLAS ELEKTRONIK GmbH holding 49%. The planned Indian venture would cover anti-submarine warfare manufacturing, system integration and through-life support.
Know CFF Fluid Control inside out
Results, valuation, peers and who's buying, in one view.
What did CFF Fluid Control approve with TKMS?
CFF Fluid Control approved entering into a binding joint-venture agreement with TKMS on 6 November 2026 to establish TKMS CFF Defence Systems Private Limited in India. Its board considered and approved the arrangement on that date, according to the company’s disclosure to BSE Limited under Regulation 30 of the Securities and Exchange Board of India, or SEBI, Listing Obligations and Disclosure Requirements Regulations, 2015.
The proposed venture’s stated purpose is to advance the Make in India initiative through local manufacturing, system integration and comprehensive through-life support for anti-submarine warfare. The filing identifies no naval programme, customer, purchase order, contract value or delivery timetable, so it describes the intended operating scope rather than revenue associated with a disclosed award.
CFF Fluid Control termed the arrangement a binding joint-venture agreement, but said definitive agreements between the parties are yet to be executed. The announcement therefore establishes the approved framework and proposed 51%-49% ownership structure, while leaving the detailed rights, obligations and other terms to the definitive documentation.
The company’s disclosure also cites SEBI Master Circular No. HO/49/14/14(7)2025-CFD-POD2/I/3762/2026 dated 30 January 2026. This regulatory context explains why the announcement records the parties, purpose, ownership, related-party status and terms still to be documented for the 6 November 2026 arrangement.
Who would own TKMS CFF Defence Systems Private Limited?
CFF Fluid Control is proposed to own 51% of TKMS CFF Defence Systems Private Limited and TKMS is proposed to own 49%. The 2-percentage-point difference gives CFF Fluid Control the majority position in the proposed Indian entity, and the same split appears in both the main announcement and Annexure A.
The filing does not disclose capital contributions from either shareholder, despite specifying the 51%-49% split. It records the size of the agreement as not applicable, meaning there is no disclosed rupee value, enterprise valuation, investment commitment or expected turnover for the proposed venture as of 6 November 2026.
The company also said the class of shares, issue price and other related terms are to be finalised and documented in definitive agreements executed by the parties. As a result, the stated 51% stake does not provide a disclosed subscription price, share valuation, funding schedule or dilution mechanism.
What anti-submarine warfare work would the venture perform?
The proposed venture would undertake local manufacturing, system integration and comprehensive through-life support for anti-submarine warfare in India. These three stated activities place manufacturing and integration alongside support throughout the operating life of relevant systems, rather than limiting the announced plan to the supply of a single product.
The filing does not identify the systems to be manufactured, the platforms to be integrated or the support services to be delivered. It also gives no facility location, local-content percentage, technology-transfer detail, production capacity or employee count, so the 6 November 2026 disclosure does not quantify the operating scale of the plan.
CFF Fluid Control presents the venture as supporting Make in India, but it does not provide a sales target, margin target, order backlog or date for the entity to begin operations. The proposed venture’s anti-submarine warfare focus is defined, while its financial contribution and commercial launch schedule are not disclosed.
The company marked loan-agreement details as not applicable in Annexure A. Consequently, the announcement provides no lender, borrower, loan amount, security or repayment information for TKMS CFF Defence Systems Private Limited at the time of the 6 November 2026 board approval.
Got a follow-up? Ask IRIS
Which CFF Fluid Control-TKMS terms remain to be documented?
The definitive agreements remain to be executed and are expected to set out the respective rights and obligations of CFF Fluid Control and TKMS. The filing specifically links the proposed 51%-49% ownership structure to terms and conditions that will be contained in those agreements.
No special rights are specified in the current disclosure. The regulatory disclosure category covers matters such as director-appointment rights, first rights to subscribe for shares and restrictions on capital-structure changes, but CFF Fluid Control does not provide those provisions for the proposed venture on 6 November 2026.
CFF Fluid Control’s board authorised Managing Director Sunil Menon and Chairman and Non-Executive Director Gautam Makker to finalise and execute the agreement on its behalf. The authorisation identifies two company representatives, although the filing does not name a nominee director for the proposed venture’s board.
The company said TKMS is not related to CFF Fluid Control, its promoter or its promoter group, and classified the transaction as not a related-party transaction. That status distinguishes the proposed 51%-49% venture from a transaction involving a disclosed promoter-linked counterparty.
What does the filing establish and what does it leave open?
The filing establishes an approved binding framework, a proposed Indian entity and a 51%-49% ownership allocation. Compared with these disclosed headline terms, the agreement size is marked not applicable and the disclosure provides no capital contribution, issue price, contract value or operational start date.
The difference between the settled ownership allocation and the undisclosed economic terms is material to interpreting the announcement. CFF Fluid Control has disclosed its proposed 51% stake and the venture’s three activity areas, but has not quantified how much either party would invest or what financial contribution the entity might make.
The company has also not disclosed customer commitments, manufacturing assets, regulatory approvals or a named anti-submarine warfare programme for the proposed venture. These omissions do not alter the stated purpose of local manufacturing, integration and through-life support, but they leave the timing and scale of implementation unresolved.
For the 6 November 2026 filing, termination or amendment details were listed as not applicable. CFF Fluid Control noted that a future termination or amendment would require additional stock-exchange disclosure covering the parties, agreement nature, execution date and stated impact or reasons.
Conclusion
CFF Fluid Control has approved a binding framework with TKMS for an Indian anti-submarine warfare venture in which it is proposed to hold 51%, compared with TKMS’s proposed 49%. The announcement combines a defined ownership structure with a Make in India plan spanning local manufacturing, system integration and comprehensive through-life support.
The next disclosed step is execution of definitive agreements, which are to set out the parties’ rights, obligations and share-related terms, including the issue price and class of shares. Any later disclosure on funding, governance, customer programmes, facilities or an operating start date would provide information not quantified in the 6 November 2026 announcement.