










Coromandel Engineering first-half profit rises to Rs 34.29 lakh
Key highlights
- Coromandel Engineering's first-half revenue rose to Rs 25.25 crore for the period ended September 30, 2026, from Rs 22.03 crore a year earlier.
- Coromandel Engineering reported first-half profit after tax of Rs 34.29 lakh, versus a Rs 69.12 lakh loss a year earlier.
- Coromandel Engineering's September-quarter profit before tax was Rs 1.39 lakh on revenue of Rs 9.88 crore.
- The auditor highlighted Rs 8.59 crore of overdue micro and small enterprise dues, including interest.
powered by IRIS
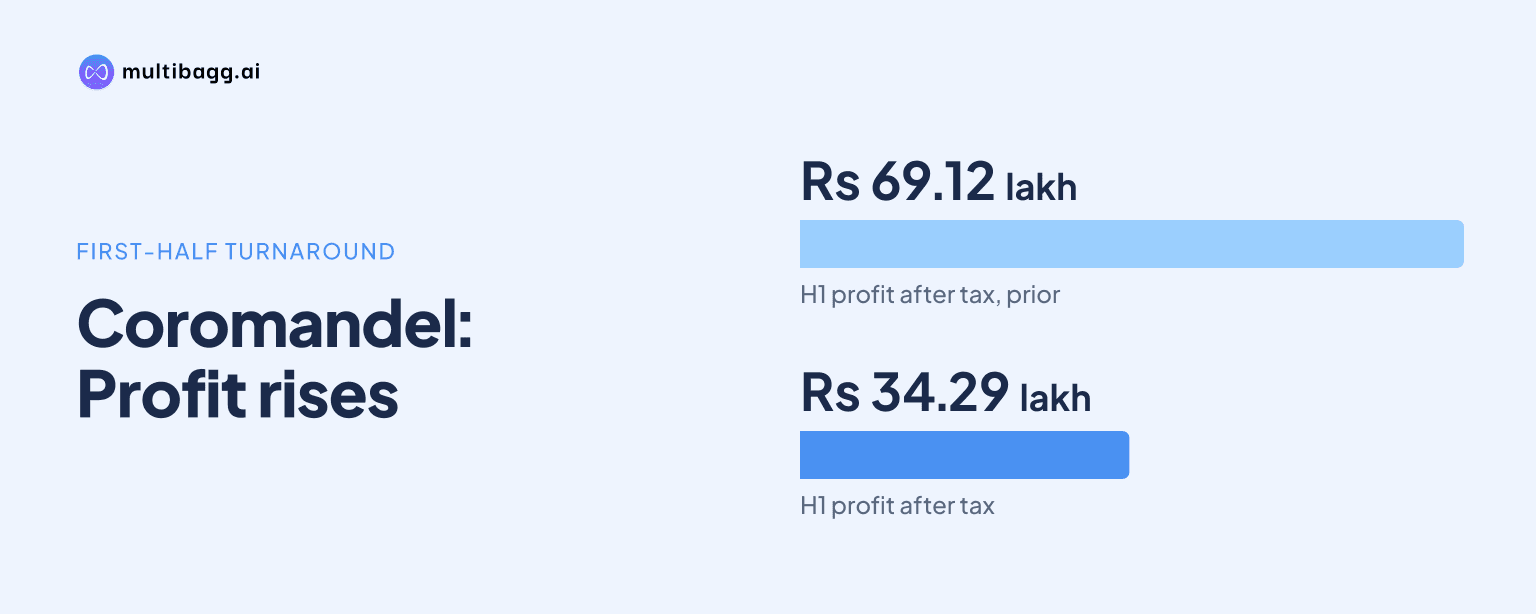
Coromandel Engineering Company Limited reported profit after tax of Rs 34.29 lakh for the half year ended September 30, 2026, compared with a Rs 69.12 lakh loss a year earlier, while September-quarter profit was Rs 1.39 lakh on revenue from operations of Rs 9.88 crore.
Know Coromandel Engineering Company inside out
Results, valuation, peers and who's buying, in one view.
How did Coromandel Engineering perform in the first half?
Coromandel Engineering returned to a first-half profit after tax of Rs 34.29 lakh in the six months ended September 30, 2026, compared with a Rs 69.12 lakh loss in the corresponding 2025 period. Profit before tax was Rs 34.29 lakh, up from Rs 9.71 lakh a year earlier, and the latest half-year statement recorded no current or deferred tax expense.
Revenue from operations increased by Rs 3.21 crore to Rs 25.25 crore from Rs 22.03 crore in the prior-year half. Total revenue, including other income of Rs 2,000, was Rs 25.25 crore, compared with Rs 22.15 crore in the half year ended September 30, 2025.
Total expenses rose to Rs 24.90 crore in the September 2026 half year from Rs 22.05 crore a year earlier. Sub-contracting and labour payments increased to Rs 18.33 crore from Rs 13.82 crore, while material consumption declined to Rs 1.88 crore from Rs 2.84 crore and finance costs fell to Rs 1.07 crore from Rs 1.43 crore.
The movement in reported net profit also reflects the prior-year tax line. The half year ended September 30, 2025 carried a deferred-tax charge of Rs 78.83 lakh, converting profit before tax of Rs 9.71 lakh into a loss after tax of Rs 69.12 lakh; the September 2026 half-year profit before tax and profit after tax were both Rs 34.29 lakh.
Coromandel Engineering identifies construction as its single significant business segment. The September 2026 filing therefore provides no separate revenue, cost or profit split by project type, geography or operating division.
Why did Coromandel Engineering's September-quarter margin narrow?
Coromandel Engineering earned Rs 1.39 lakh after tax in the quarter ended September 30, 2026, down from Rs 32.89 lakh in the June 2026 quarter and Rs 3.39 lakh in the September 2025 quarter. With revenue from operations of Rs 9.88 crore, the September-quarter profit before tax was about 0.14% of revenue, compared with about 2.14% in the preceding quarter.
Quarterly revenue from operations declined by Rs 5.48 crore from Rs 15.36 crore in June 2026 to Rs 9.88 crore in September 2026. Total expenses declined by Rs 5.17 crore to Rs 9.87 crore, but the decrease was marginally smaller than the revenue reduction, leaving a profit before tax of Rs 1.39 lakh.
Sub-contract and labour payments were Rs 7.97 crore in the September quarter, compared with Rs 10.36 crore in June. The September-quarter statement reported negative material consumption of Rs 27.62 lakh, against material consumption of Rs 2.15 crore in June, while other expenses rose to Rs 80.98 lakh from Rs 71.47 lakh.
Finance costs reduced to Rs 25.94 lakh in the September quarter from Rs 81.10 lakh in June and Rs 90.51 lakh in the September 2025 quarter. Employee-benefit expense nevertheless increased to Rs 82.99 lakh from Rs 71.65 lakh in June, while depreciation and amortisation was Rs 27.76 lakh against Rs 27.90 lakh.
The September-quarter comparison shows that revenue fell by more than one-third from the June quarter, whereas the profit before tax reduction was much sharper. The filing does not provide project-level information explaining the change because construction is reported as one business segment.
Got a follow-up? Ask IRIS
What changed in Coromandel Engineering's cash flow and balance sheet?
Coromandel Engineering generated net cash from operating activities of Rs 9.06 crore in the half year ended September 30, 2026. This compared with net cash used in operating activities of Rs 2.72 crore for the year ended March 31, 2026, although the two disclosed periods are not directly comparable because one covers six months and the other a full year.
The half-year operating cash movement included a Rs 35.56 crore increase in trade and other payables and a Rs 27.04 crore increase in trade and other receivables. Cash generated from operations was Rs 9.06 crore after these working-capital changes, while the statement did not report a separate direct-tax payment or refund for the period.
Investing activities produced an inflow of Rs 2.26 crore, principally from sale of property, plant and equipment. Financing activities used Rs 11.15 crore, including net loan repayment of Rs 10.18 crore and finance charges of Rs 97.51 lakh, resulting in a Rs 17.07 lakh increase in cash and cash equivalents to Rs 46.65 lakh at September 30, 2026.
Total assets were Rs 122.85 crore at September 30, 2026, compared with Rs 97.04 crore at March 31, 2026. Current assets increased to Rs 105.72 crore from Rs 79.35 crore, while current liabilities rose to Rs 108.17 crore from Rs 72.83 crore and total equity increased to Rs 13.65 crore from Rs 13.31 crore.
What auditor matters and plans should readers note?
Coromandel Engineering's independent auditor drew attention to overdue statutory dues in its review report dated November 14, 2026. Tax deducted at source of Rs 26.85 lakh for April to September 2026 and Employees' Provident Fund contributions of Rs 7.24 lakh for June to September remained unpaid beyond due dates, with provision made in the accounts.
The auditor also highlighted dues to micro and small enterprises, including interest, of Rs 8.59 crore that remained unpaid beyond the dates prescribed under the Micro, Small and Medium Enterprises Development Act, 2006. The review report stated that the auditor's conclusion was not modified in respect of the statutory and micro-enterprise dues.
A separate outstanding tax-deducted-at-source demand of Rs 13.75 lakh remained unpaid at the reporting date, and no provision had been recognised in the accounts for that demand. The auditor also did not modify its conclusion in relation to this matter.
The Board approved establishing either a subsidiary or a wholly owned subsidiary in Sri Lanka, subject to applicable regulations, citing global expansion and construction-business opportunities and proposals received by Coromandel Engineering. The filing does not disclose an investment amount, establishment date, project value or revenue target for the proposed operation.
The Board also approved the appointment of Lakshmi Narasimman Srikanth as an additional non-executive independent director from November 14, 2026, subject to shareholder approval. His proposed term is five years, and the filing describes 25 years of experience in finance, taxation, compliance, cash management and asset management.
Conclusion
Coromandel Engineering's first-half result shows a return to reported profitability as revenue from operations increased to Rs 25.25 crore and profit before tax reached Rs 34.29 lakh. The September-quarter outcome was materially lower than the June quarter, however, with profit before tax of Rs 1.39 lakh on Rs 9.88 crore of revenue, compared with Rs 32.89 lakh on Rs 15.36 crore in June.
The next disclosures to watch are progress on the proposed Sri Lanka subsidiary or wholly owned subsidiary, for which Coromandel Engineering has not provided a timetable or financial commitment, and any change in the Rs 8.59 crore of overdue micro and small enterprise dues. The company will also need to address the statutory dues noted in the November 14, 2026 auditor review.