










DHP India records Rs 14.3993 crore half-year valuation gain
Key highlights
- DHP India reported a Rs 14.3993 crore gross fair-value gain in OCI for the half year ended September 30, 2026.
- A Rs 3.2946 crore deferred-tax charge reduced DHP India’s half-year OCI gain to Rs 11.1047 crore.
- DHP India’s current financial investments increased to Rs 204.7856 crore from Rs 182.5866 crore at March 31, 2026.
- DHP India reported a Rs 5.5707 crore gross valuation loss in the September 2026 quarter after a Rs 19.97 crore gain in June.
powered by IRIS
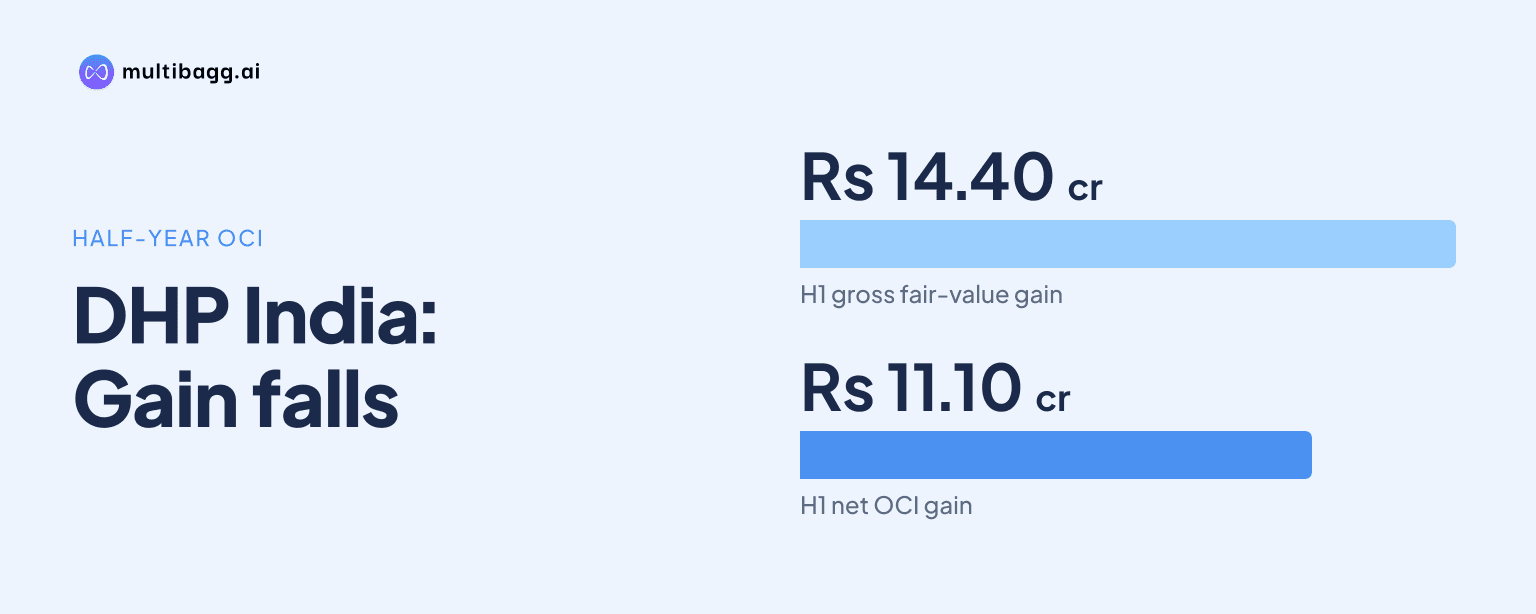
DHP India Limited recorded a Rs 14.3993 crore gross fair-value gain on equity and debt investments in other comprehensive income for the half year ended September 30, 2026, while current financial investments stood at Rs 204.7856 crore. The gain followed a Rs 48.28 lakh gross gain a year earlier and a Rs 14.4487 crore gross loss in the year ended March 31, 2026.
Know DHP India inside out
Results, valuation, peers and who's buying, in one view.
What was DHP India’s half-year investment valuation gain?
DHP India reported a Rs 14.3993 crore unrealised fair-value gain on equity and debt investments for the half year ended September 30, 2026. It presented this amount under other comprehensive income, or OCI, as an item that will not be reclassified to profit or loss under Indian Accounting Standards, or Ind AS.
The company said it used net asset value, or NAV, at September 30, 2026 to value its investments. The disclosed holdings include equity mutual funds and gold/silver exchange-traded fund, or ETF, investments, with the valuation movement described as appreciation or diminution of equity and debt mutual-fund investments.
The half-year gross gain was Rs 13.9165 crore higher than the Rs 48.28 lakh reported in the corresponding half year ended September 30, 2025. The direction also reversed from the Rs 14.4487 crore gross valuation loss reported for the year ended March 31, 2026.
How did deferred tax change DHP India’s OCI gain?
DHP India recorded a Rs 3.2946 crore deferred-tax charge against the Rs 14.3993 crore half-year gross valuation gain. After this tax effect, its net OCI gain was Rs 11.1047 crore for the six months ended September 30, 2026.
The after-tax OCI outcome was higher than the Rs 37.23 lakh net OCI gain in the corresponding prior-year half. In the year ended March 31, 2026, the company reported a Rs 11.1428 crore net OCI loss after a Rs 14.4487 crore gross loss was partly offset by a Rs 3.3059 crore deferred-tax benefit.
The two quarters within the September 2026 half moved in opposite directions. DHP India reported a Rs 19.97 crore gross valuation gain in the quarter ended June 30, 2026, followed by a Rs 5.5707 crore gross valuation loss in the quarter ended September 30, 2026.
For the September quarter, a Rs 81.79 lakh deferred-tax benefit reduced the net OCI loss to Rs 4.7528 crore. The June-quarter gross gain carried a Rs 4.1125 crore deferred-tax charge, resulting in net OCI income of Rs 15.8575 crore for that quarter.
How large was DHP India’s investment portfolio at September 2026?
DHP India carried Rs 204.7856 crore of current financial investments at September 30, 2026, compared with Rs 182.5866 crore at March 31, 2026. The reported balance increased by Rs 22.199 crore over the six-month period.
Investments were the largest specifically identified current financial-asset line in the standalone statement. At September 30, 2026, trade receivables were Rs 9.9493 crore, cash and cash equivalents were Rs 2.6794 crore, and other financial assets were Rs 3.2586 crore.
The company also reported inventory of Rs 23.1958 crore at September 30, 2026, compared with Rs 22.7848 crore at March 31, 2026. This makes the investment balance substantially larger than inventory and the separately listed financial-asset balances in the same statement.
The balance-sheet disclosure does not split the Rs 204.7856 crore investment line by mutual fund, gold ETF, silver ETF or debt holding. Its valuation note identifies the relevant instruments as equity mutual funds and gold/silver ETF funds, rather than providing individual fund values or units held.
Got a follow-up? Ask IRIS
Did the valuation gain increase DHP India’s reported profit?
DHP India’s Rs 14.3993 crore gross valuation gain did not enter profit after tax because it was reported in OCI rather than the profit-and-loss statement. Profit after tax for the half year ended September 30, 2026 was Rs 9.9604 crore, compared with Rs 5.7266 crore in the corresponding half year of 2025.
Combining Rs 9.9604 crore of profit after tax with Rs 11.1047 crore of net OCI gives total comprehensive income of Rs 21.0651 crore for the half year. This total includes the after-tax investment valuation movement, while the reported profit figure excludes it.
Net revenue from operations increased to Rs 49.9823 crore in the half year ended September 30, 2026 from Rs 34.9677 crore a year earlier. Profit before tax rose to Rs 13.5402 crore from Rs 7.7196 crore over the same periods.
DHP India stated that it is primarily engaged in manufacturing engineering goods and has no separate reportable segment under Ind AS 108, the segment-reporting standard. The filing therefore does not attribute the investment holdings or the OCI movement to a separate operating segment.
What do DHP India’s cash-flow disclosures say about mutual-fund purchases?
DHP India’s half-year cash-flow statement listed Rs 7.7996 crore under investment in mutual funds for the six months ended September 30, 2026. The same cash-flow statement recorded Rs 8.3761 crore of net cash used in investing activities, including Rs 60.25 lakh spent on property, plant and equipment and capital work in progress.
The company separately stated that it made no investment in mutual funds during the quarter ended September 30, 2026. That statement distinguishes the September quarter from the cumulative half-year cash-flow line, but the filing does not provide a quarter-by-quarter reconciliation of mutual-fund cash purchases.
The significant-events note refers to cumulative mutual-fund investment of Rs 7.7996 crore “during the half year ended September 30, 2025,” whereas the cash-flow statement for the current half year carries the same Rs 7.7996 crore line. The filing does not explain this date difference, so the disclosed figures do not establish a precise timing for the cash movement.
Cash and cash equivalents were Rs 2.6794 crore at September 30, 2026, compared with Rs 44.58 lakh at the beginning of the year. Net cash from operating activities was Rs 10.5692 crore and net cash from financing activities was Rs 4.05 lakh for the half year.
Conclusion
DHP India’s September 2026 half-year results show that NAV-based valuation of its disclosed mutual-fund and gold/silver ETF holdings had a material effect on comprehensive income. The Rs 14.3993 crore gross gain, reduced to Rs 11.1047 crore after deferred tax, sat outside the Rs 9.9604 crore profit-after-tax figure, while current investments rose to Rs 204.7856 crore.
The next NAV-based valuation will determine whether the September-quarter Rs 5.5707 crore gross loss extends into another OCI loss or reverses. Investors can also watch for clarification of the Rs 7.7996 crore mutual-fund cash-flow line, given the filing’s statement that no mutual-fund investment was made in the quarter ended September 30, 2026.