










Emerald Leisures earmarks ₹98.5 crore from rights issue
Key highlights
- Emerald Leisures proposes gross rights-issue proceeds of ₹130 crore.
- Emerald Leisures has earmarked ₹48.5 crore for working capital in Fiscal 2027 and Fiscal 2028.
- Emerald Leisures plans ₹25 crore each for preference-share redemption and borrowings repayment.
- Emerald Leisures reported outstanding borrowings of ₹83.609 crore as of September 30, 2026.
powered by IRIS
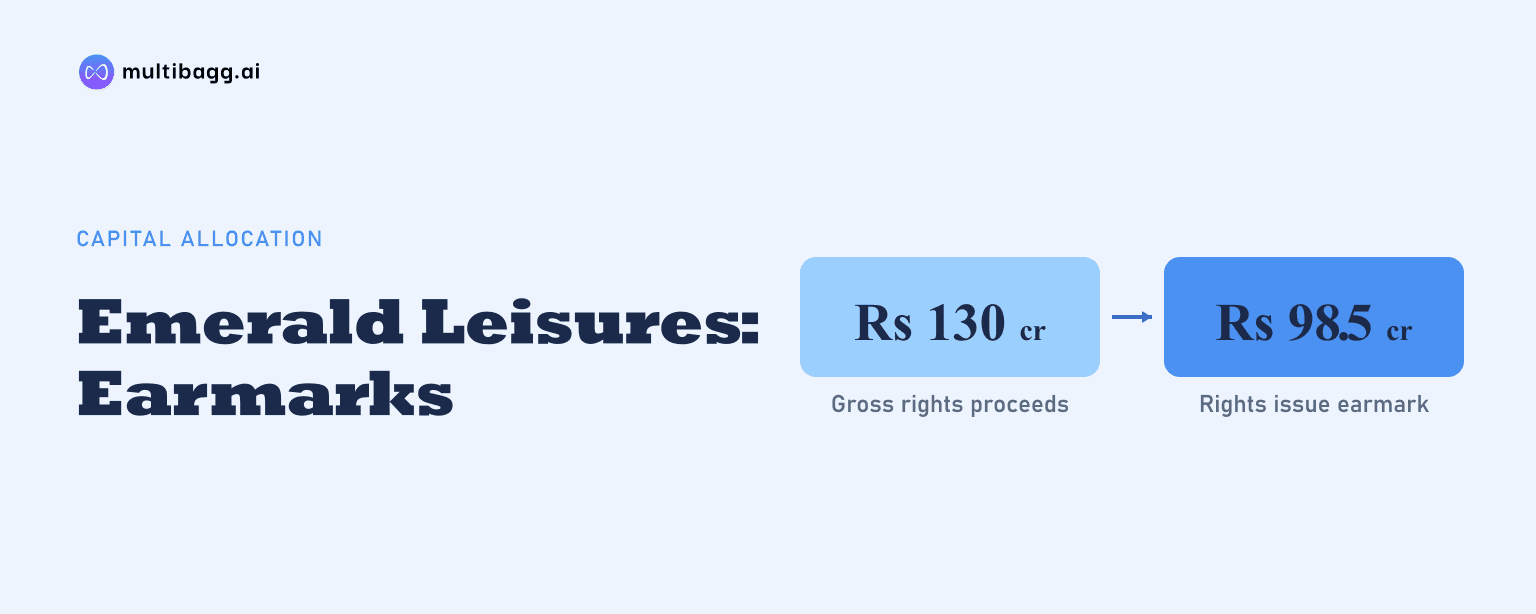
Emerald Leisures Limited plans a ₹130 crore rights issue, with ₹48.5 crore earmarked for working capital and ₹25 crore each for preference-share redemption and borrowings repayment under a November 5, 2026 committee-approved allocation. The draft offer leaves the issue price, expenses and net proceeds to be finalised.
Know Emerald Leisures inside out
Results, valuation, peers and who's buying, in one view.
How will Emerald Leisures use the rights issue proceeds?
Emerald Leisures proposes to allocate ₹98.5 crore of its planned ₹130 crore gross rights-issue proceeds to three specified uses: ₹25 crore for redeeming preference shares, ₹25 crore for repayment or prepayment of borrowings, and ₹48.5 crore for working-capital requirements. The board authorised the issue on October 1, 2026, and the Rights Issue Committee approved the proposed deployment on November 5, 2026.
The three disclosed allocations leave ₹31.5 crore of gross proceeds before issue expenses and any final general-corporate-purpose allocation. The draft offer does not state the issue price, number of Rights Equity Shares, record date, rights-entitlement ratio, issue expenses or net proceeds because these items are to be determined and updated in the final letter of offer.
Emerald Leisures may use any balance net proceeds for general corporate purposes, subject to a cap of 25% of gross proceeds under the disclosed plan. The company says this category may include growth opportunities, marketing, brand-building and strategic initiatives, with its board or a committee deciding the specific use based on business requirements.
How much preference capital and debt will Emerald Leisures address?
Emerald Leisures intends to redeem ₹25 crore of its 10% non-convertible, non-cumulative, participating, redeemable preference shares, or NCPRPS, in Fiscal 2027. The planned redemption covers 25 lakh preference shares, representing half of the 50 lakh NCPRPS outstanding at the draft offer date.
The NCPRPS have a face value of ₹100 each and an outstanding value of ₹50 crore. They were allotted between September 2017 and April 2019, are redeemable at par, and have a tenure of up to 10 years from their allotment dates as determined by the board. Emerald Leisures said no funds had been deployed towards their redemption as of the draft offer date.
Emerald Leisures also plans to use ₹25 crore to repay or prepay certain borrowings from total outstanding borrowings of ₹83.609 crore as of September 30, 2026. The earmark is therefore a partial repayment plan rather than a proposal to eliminate all reported borrowings.
The disclosed borrowings comprise 10 inter-corporate deposits carrying interest rates of 10% or 12%, all repayable on demand. The two largest principal balances were ₹29.625 crore owed to Jaydeep V Mehta and ₹22.1865 crore owed to Juhu Resorts & Development Private Limited, together amounting to ₹51.8115 crore. Emerald Leisures does not specify which lenders will receive the proposed ₹25 crore repayment.
Why is Emerald Leisures raising ₹48.5 crore for working capital?
Emerald Leisures proposes to deploy ₹48.5 crore from net proceeds for incremental working-capital needs in Fiscal 2027 and Fiscal 2028. The schedule allocates ₹13.9038 crore to Fiscal 2027 and ₹34.5962 crore to Fiscal 2028, making the latter period the larger planned deployment year.
The company forecasts net working-capital requirements of ₹37.8412 crore in Fiscal 2027 and ₹68.6554 crore in Fiscal 2028. Besides rights-issue funding, the plan assumes borrowings of ₹12 crore in each year and internal accruals of ₹11.9374 crore in Fiscal 2027 and ₹22.0592 crore in Fiscal 2028.
The projected requirements follow a change in Emerald Leisures' historical working-capital position. Net working capital moved from negative ₹10.7952 crore in Fiscal 2024 to ₹5.4461 crore in Fiscal 2025 and ₹11.4837 crore in Fiscal 2026, while inventories rose from ₹1.1257 crore in Fiscal 2024 to ₹31.164 crore in Fiscal 2026.
Got a follow-up? Ask IRIS
What projects support Emerald Leisures' working-capital forecast?
Emerald Leisures links the working-capital proposal to its planned expansion into real-estate development, including redevelopment of its Chembur, Mumbai plot into a residential tower with estimated saleable area of about 1.75 lakh square feet. The company also holds a 51% interest in a limited liability partnership with Gala Group that is exploring a cluster development at Mahim, Mumbai.
The company identifies construction and development expenditure, material procurement, payments to contractors and consultants, professional fees, statutory charges and project-management costs as expected working-capital uses. It says cash outflows during project execution can occur before customer collections, which may be linked to construction milestones and payment schedules.
Emerald Leisures forecasts total current assets of ₹60.2043 crore in Fiscal 2027 and ₹90.584 crore in Fiscal 2028, compared with ₹32.1881 crore in Fiscal 2026. Other current assets are projected to rise from ₹34.6 lakh in Fiscal 2026 to ₹31.6542 crore in Fiscal 2027 and ₹60.3935 crore in Fiscal 2028, primarily reflecting anticipated advances and operating balances.
The company expects inventory holding days to decline from 689 days in Fiscal 2026 to 151 days in Fiscal 2027 and 53 days in Fiscal 2028. Trade receivable days are estimated at four days in Fiscal 2027 and five days in Fiscal 2028, compared with 13 days in Fiscal 2026, while trade payable days are projected to fall from 37 days to 29 days and then 14 days.
What is still undecided in Emerald Leisures' rights issue?
Emerald Leisures has not disclosed the price of its rights shares, the subscription ratio, record date, issue expenses or final net-proceeds amount. The capital structure table also leaves the number of Rights Equity Shares blank, and the draft offer states that the rights shares may be partly paid, with the board retaining the ability to alter the timing of a first and final call.
The company says its deployment plan has not been appraised by a bank or financial institution. Actual funding deployment may be reduced, extended or reallocated in response to completion timing, market conditions, business requirements, economic trends, potential investments and acquisitions, or other commercial factors.
If a stated use receives less funding than allocated, Emerald Leisures may direct the remaining amount to general corporate purposes within the 25% cap on gross proceeds. If the issue raises less than required for the stated objects, the company says it may consider internal accruals, additional equity arrangements, debt arrangements, or a combination of these funding sources.
Conclusion
Emerald Leisures' proposed rights issue combines balance-sheet actions with funding for planned real-estate activity. Of the ₹98.5 crore specifically earmarked, ₹50 crore is directed to preference-share redemption and debt repayment, while ₹48.5 crore is intended to support working-capital needs associated with the Chembur redevelopment, the Mahim partnership opportunity and other prospective projects.
The next points to watch are the final issue price, entitlement ratio, record date, expenses and net-proceeds calculation. Emerald Leisures has scheduled ₹13.9038 crore of working-capital deployment for Fiscal 2027 and ₹34.5962 crore for Fiscal 2028, while its plan remains subject to business conditions and board-approved revisions.