










Emmforce Autotech FY26 Revenue Rises 27% to ₹113 Crore
Key highlights
- Emmforce reported FY26 revenue of about ₹113 crore, up 27% year on year.
- FY26 profit after tax was ₹8.25 crore, up 2.27%, while net profit margin declined to 7.32%.
- A U.S. export order worth roughly ₹470 crore over nine years is expected to contribute about ₹60 crore in FY27.
- Management has targeted approximately ₹195 crore of FY27 revenue and nearly ₹240 crore for FY28.
powered by IRIS
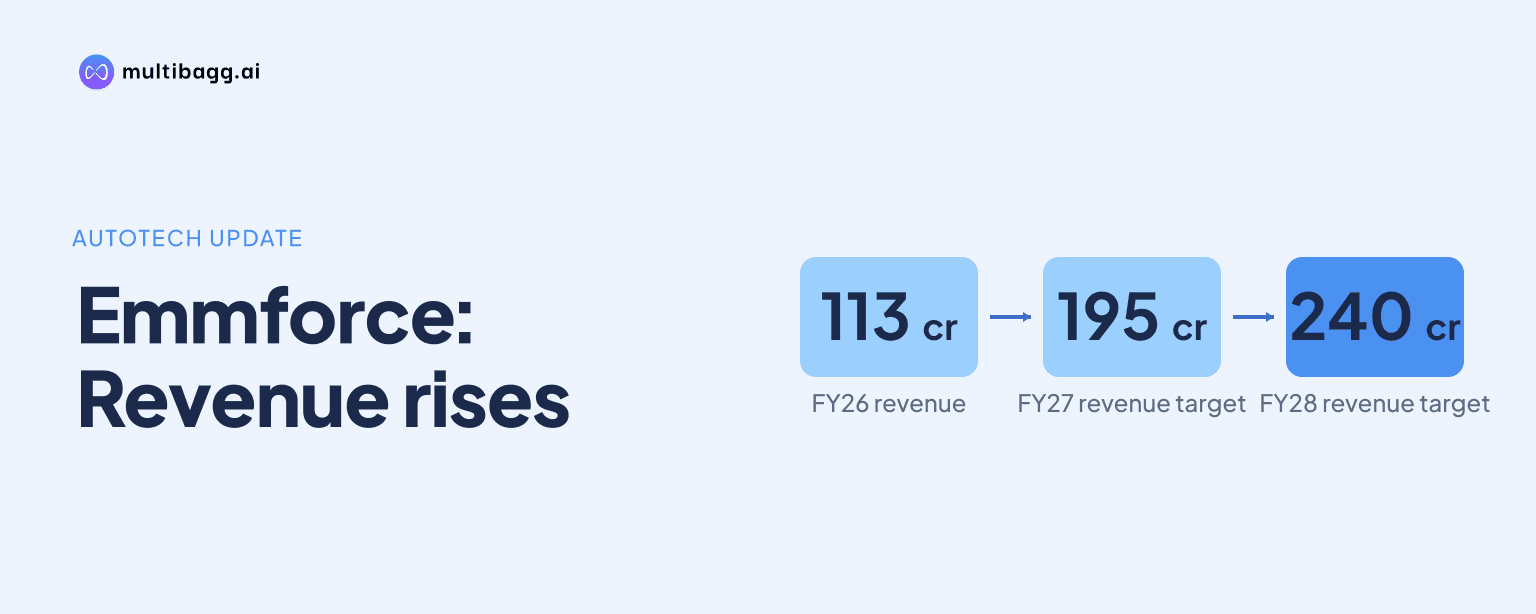
Emmforce Autotech Limited reported FY26 revenue of ₹113 crore, a 27% increase from the prior year, with an EBITDA margin of about 20%, supported by drivetrain components and the scaling of its agricultural business. The company has also outlined a FY27 revenue target of ₹195 crore, including expected production from its export order book.
Know Emmforce Autotech inside out
Results, valuation, peers and who's buying, in one view.
What did Emmforce report for FY26?
Emmforce Autotech Limited reported FY26 revenue of ₹113 crore and an EBITDA margin of about 20% in its investor presentation and earnings-call material. The performance was attributed to demand for specialized automotive drivetrain parts and the initial scale-up of the agricultural equipment business. Emmforce is a Baddi, Himachal Pradesh-based precision engineering manufacturer serving automotive, agricultural equipment and forging applications.
The company’s annual financial insights show total revenue of ₹112.72 crore for FY26, compared with ₹89.03 crore in FY25, representing growth of 26.61%. The small difference between the rounded ₹113 crore figure in the presentation and ₹112.72 crore in the financial insights reflects rounding. Total expenses rose 30.21% to ₹100.71 crore, faster than revenue growth.
Reported FY26 profit after tax was ₹8.25 crore, up 2.27% from ₹8.06 crore in FY25. The annual operating profit margin declined to 12.97% from 16.10%, while net profit margin fell to 7.32% from 9.21%. These figures show that revenue growth did not translate into a proportionate rise in reported profit after tax.
A separate results table in the supplied material lists FY25-26 revenue of ₹104.47 crore and net profit of ₹12.06 crore. As the source presents this alongside the annual insights table without reconciling the difference, investors should rely on the company’s filed audited financial statements for the final statutory comparison.
How did Emmforce perform in the second half of FY26?
Emmforce reported H2 FY26 revenue from operations of ₹59.1 crore, up 12.6% year on year, while net profit declined 10.6% to ₹4.2 crore. The half-year result indicates that sales continued to expand, although profitability was weaker on the reported H2 comparison.
For the March 2026 quarter, the reported-results table shows revenue of ₹55.00 crore and net profit of ₹5.63 crore. Revenue was 11.2% higher quarter on quarter than the ₹49.47 crore reported for the September 2025 quarter. However, net profit was 12.6% lower quarter on quarter, and operating margin declined by 220 basis points to 20.17% from 22.37%.
The company’s product range includes four-wheel-drive locking hubs, spindles, driveshaft yokes, axle assemblies, differential parts, forged shafts and gears. It has also launched proprietary hydraulic gear pumps. These products serve a specialised part of the automotive supply chain, particularly four-wheel-drive and performance-racing vehicle applications.
What is driving Emmforce's FY27 growth plan?
Emmforce’s FY27 plan is based on automotive order execution and a larger contribution from the agricultural segment. Management has targeted about ₹165 crore of automotive revenue and about ₹30 crore of agricultural revenue for FY27, implying total revenue of approximately ₹195 crore.
A key element is a U.S. export order secured in December 2024, valued at roughly ₹470 crore over nine years. The order entered full commercial production in December 2025 from a dedicated greenfield facility, according to the supplied material. The company expects this contract to contribute about ₹60 crore annually in FY27.
The investor presentation states that Emmforce’s order book exceeds ₹500 crore. A multi-year order book can provide visibility, but reported revenue will still depend on customer schedules, production ramp-up and execution at the dedicated facility. The source does not provide a quarter-by-quarter revenue schedule for the contract.
Management has also set a FY28 overall revenue aim of nearly ₹240 crore, with the agricultural business expected to contribute close to ₹50 crore. These are company targets rather than reported financial results, and their achievement remains dependent on execution in both operating segments.
Got a follow-up? Ask IRIS
How is the agricultural business contributing to Emmforce?
Emmforce is expanding its agricultural business through its EMSPL subsidiary, which makes rotavator components, rotavator blades and forgings. Commercial sales of rotavator parts and blades to TAFE began in January 2026, creating an additional revenue stream beyond the company’s established automotive operations.
The company stated that it started with around a 30% share of business for these supplies and plans to scale this to 70%-80%. The source does not state the time frame for reaching that range or disclose the associated revenue value. Its FY27 agricultural revenue target is approximately ₹30 crore.
This expansion is significant because it broadens Emmforce’s product mix across automotive and farm-equipment demand. At the same time, the FY26 margin data indicate that investors will need to monitor whether higher volumes in newer businesses support or dilute consolidated profitability.
For customers, the Baddi-based vertically integrated setup covers precision engineering, forging and agricultural components. For investors, the agricultural operation is relevant because management expects it to account for about 15% of the ₹195 crore FY27 revenue target and roughly 21% of the nearly ₹240 crore FY28 target.
What should investors monitor after the FY26 results?
Investors should monitor the conversion of the stated order book into reported revenue, particularly the expected approximately ₹60 crore FY27 contribution from the U.S. export contract. The March 2026 quarter showed revenue growth but lower sequential net profit and operating margin, making margins as important as sales growth in subsequent disclosures.
The next stated earnings date is November 11, 2026, for Q2 FY26-27 results. The company had also issued a board-meeting intimation to consider unaudited financial results for the half year ended September 30, 2026. That update can provide a clearer view of automotive export production, agricultural sales and the trajectory toward management’s FY27 target.
The financial data supplied for FY26 contain differing annual revenue and profit figures across tables. Investors comparing valuation or earnings trends should check the audited standalone and consolidated results approved by the board, along with the notes to accounts, to identify the relevant reporting basis.
Conclusion
Emmforce delivered FY26 revenue growth of about 27% to ₹113 crore, supported by drivetrain components and an emerging agricultural business. Yet reported annual profit growth was limited and margins declined in the annual insights data, while H2 net profit also fell year on year. The results therefore show stronger sales scale alongside pressure on profitability metrics.
The next major checkpoint is the Q2 FY26-27 result scheduled for November 11, 2026. Investors will watch for evidence that the U.S. export programme is contributing toward its expected ₹60 crore annual FY27 run rate, that TAFE-linked agricultural supplies are scaling, and that margins improve as revenue rises.