










Encompass deploys Rs 12 crore, leaves Rs 7 crore unused
Key highlights
- Encompass raised Rs 19 crore in the first preferential tranche allotted on 24 September 2026.
- Encompass used Rs 10 crore for loan repayment by 30 September 2026.
- Encompass fully deployed Rs 2 crore for new product categories and subsidiary assistance.
- Encompass had Rs 7 crore of working-capital proceeds unutilised at 30 September 2026.
powered by IRIS
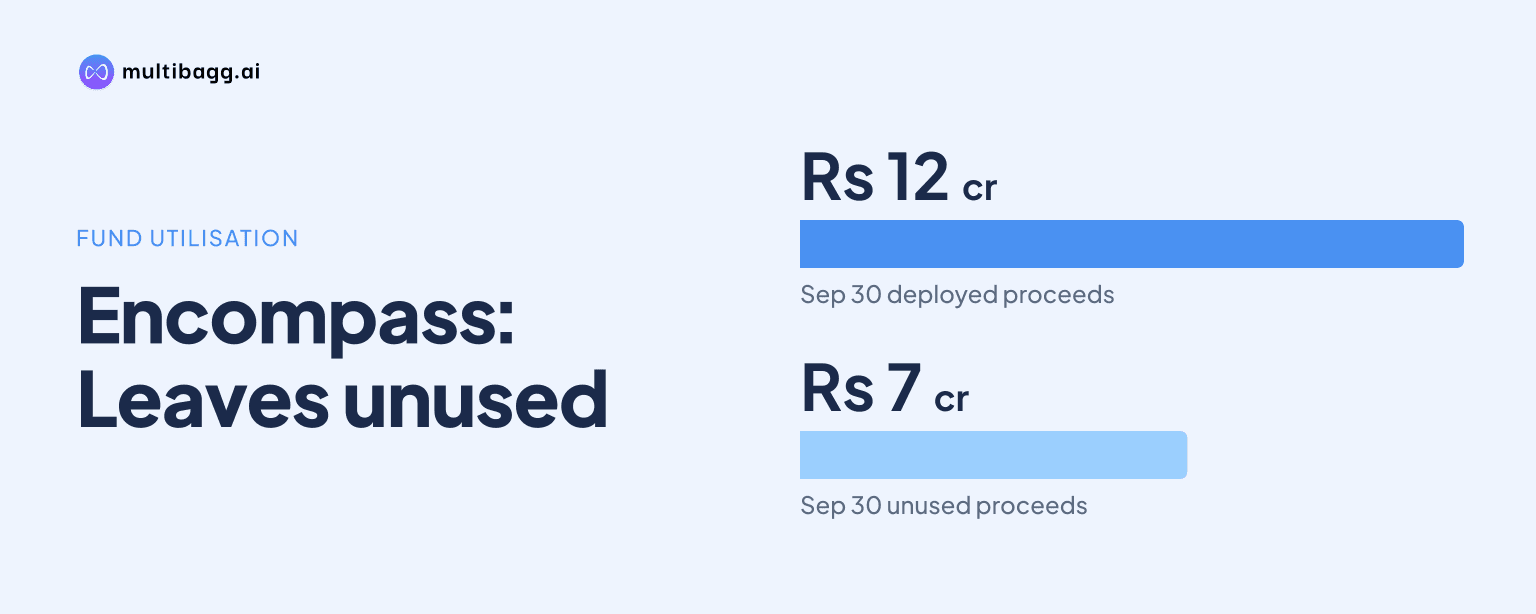
Encompass Design India Limited deployed Rs 12 crore of the Rs 19 crore raised in its first preferential-issue tranche by 30 September 2026, leaving Rs 7 crore unutilised. The company used Rs 10 crore for loan repayment and Rs 2 crore for new product categories and subsidiary assistance, with no reported deviation from the stated objects.
Know Encompass Design India inside out
Results, valuation, peers and who's buying, in one view.
What did Encompass raise in the first preferential tranche?
Encompass raised Rs 19 crore through the first tranche allotted on 24 September 2026, according to the utilisation statement for the half year ended 30 September 2026. The broader preferential issue covered 38.10 lakh equity shares with a face value of Rs 10 each, issued at Rs 250 per share, including a premium of Rs 240 per share.
The fund raise was approved by Encompass’s board on 22 July 2026 and by shareholders on 17 August 2026. NSE Limited gave in-principle approval on 18 September 2026, the same date on which the private-placement offer letter was circulated. The statement specifically covers only the Rs 19 crore received from the 24 September first tranche.
The second tranche was allotted on 3 October 2026, after the 30 September reporting date. Its proceeds were therefore excluded from the reported Rs 19 crore raised, the Rs 12 crore deployed and the Rs 7 crore remaining unutilised. Encompass stated that the second-tranche proceeds will be reported in the subsequent period.
How did Encompass use the Rs 19 crore raised?
Encompass used Rs 10 crore, the largest allocation, to repay loans and used the full Rs 2 crore earmarked for investment in new product categories, including financial assistance to subsidiaries through equity infusion and/or debt. That left the Rs 7 crore working-capital allocation untouched at 30 September 2026.
Loan repayment accounted for Rs 8 crore more deployment than investment in product categories and subsidiaries. The allocation structure also shows a split at 30 September: the Rs 10 crore loan-repayment object and Rs 2 crore investment object had each been fully used, while none of the Rs 7 crore designated for working capital had been used.
The statement records nil deviation or variation for each of the three stated objects. The Rs 12 crore deployment matched the original allocation amounts for the two completed uses, while the unspent Rs 7 crore remained within its original working-capital purpose rather than being reallocated.
Why was Rs 7 crore still unutilised at September-end?
Encompass reported that Rs 7 crore allocated to funding working-capital requirements had not yet been utilised as of 30 September 2026. The annexure did not provide a reason, timetable or revised allocation for that balance; its stated remark was that the amount was not yet utilised at the reporting date.
The position differed from the other two objects. The Rs 2 crore planned for new product categories and financial assistance to subsidiaries had been fully utilised, as had the Rs 10 crore earmarked for repayment of loans. The gap between allocation and deployment was therefore confined to the timing of the working-capital spend, rather than a reported change in purpose.
The subsidiary-related object is relevant because Encompass incorporated THE Longevity Plan Private Limited on 8 July 2026. The utilisation disclosure permits financial assistance to subsidiaries by equity infusion and/or debt, but it does not state how much of the Rs 2 crore was provided to that subsidiary, whether it was equity or debt, or identify a specific new product category funded.
Got a follow-up? Ask IRIS
Did the certificate find any deviation in Encompass’s use of funds?
No, V. K. Beswal & Associates certified that the Rs 19 crore first-tranche proceeds had been used in line with the stated objects, with no deviation or variation other than any stated in the annexure. The certificate, dated 14 November 2026, says the accountant agreed the annexure amounts with Encompass’s unaudited books, bank statements and other relevant records as at 30 September 2026.
The certificate was issued under Regulation 32 of the Securities and Exchange Board of India’s Listing Obligations and Disclosure Requirements Regulations, 2015. It defines a deviation or variation as a change in the objects or purposes of the issue, a difference in the amount used against the original disclosure, or a change in terms of a contract referred to in the explanatory statement or private-placement offer letter.
The auditor reported nil comments, while the disclosure listed no monitoring agency and no audit-committee comments after review. The certificate’s scope was limited to submission to Encompass’s board, audit committee and NSE Limited, and it did not cover the second tranche allotted on 3 October 2026.
What does the disclosure show about Encompass’s allocation timing?
The disclosure shows that Encompass had fully used the Rs 10 crore loan-repayment allocation and the Rs 2 crore investment allocation from the Rs 19 crore received by 30 September 2026. The company had not, by that date, drawn on the Rs 7 crore specifically designated for working capital, which represented more than one-third of the first-tranche allocation.
The filing does not quantify the loans repaid, name lenders or state the balance of borrowings after the Rs 10 crore repayment. It also does not break down the Rs 2 crore investment between new product categories and financial assistance to subsidiaries, so the filing identifies the approved uses and sums deployed but not the recipients or commercial outcomes.
Conclusion
Encompass deployed Rs 12 crore of the Rs 19 crore received in its 24 September 2026 preferential-issue tranche by the 30 September reporting date. The full Rs 10 crore loan-repayment allocation and full Rs 2 crore investment allocation were used, while the entire Rs 7 crore working-capital allocation remained available, with the certificate recording no deviation or variation.
The next disclosure to watch is Encompass’s reporting of proceeds from the second tranche allotted on 3 October 2026, which was outside the period covered by the certificate. Investors can also watch whether the company subsequently uses the Rs 7 crore still allocated to working capital and provides further detail on the Rs 2 crore new-category and subsidiary investment.