










Epigral Q2 revenue rises 28% as EBITDA margin falls to 18%
Key highlights
- Epigral’s Q2FY27 revenue increased 28% year on year to Rs 752 crore, supported by 6% sales-volume growth and improved realisations.
- Q2FY27 EBITDA rose 3% year on year to Rs 136 crore, while the EBITDA margin fell to 18% from 23% because of high raw-material costs.
- Derivatives and Specialty Chemicals contributed 57% of Q2FY27 revenue, up from 50% in Q2FY26 and 49% in Q1FY27.
- Epigral’s CPVC Resin and ECH expansions entered trial runs and are expected to commission within a quarter, while its 1,25,000-tonne Epoxy Resin and Formulations plant is targeted for H2FY28 commissioning.
powered by IRIS
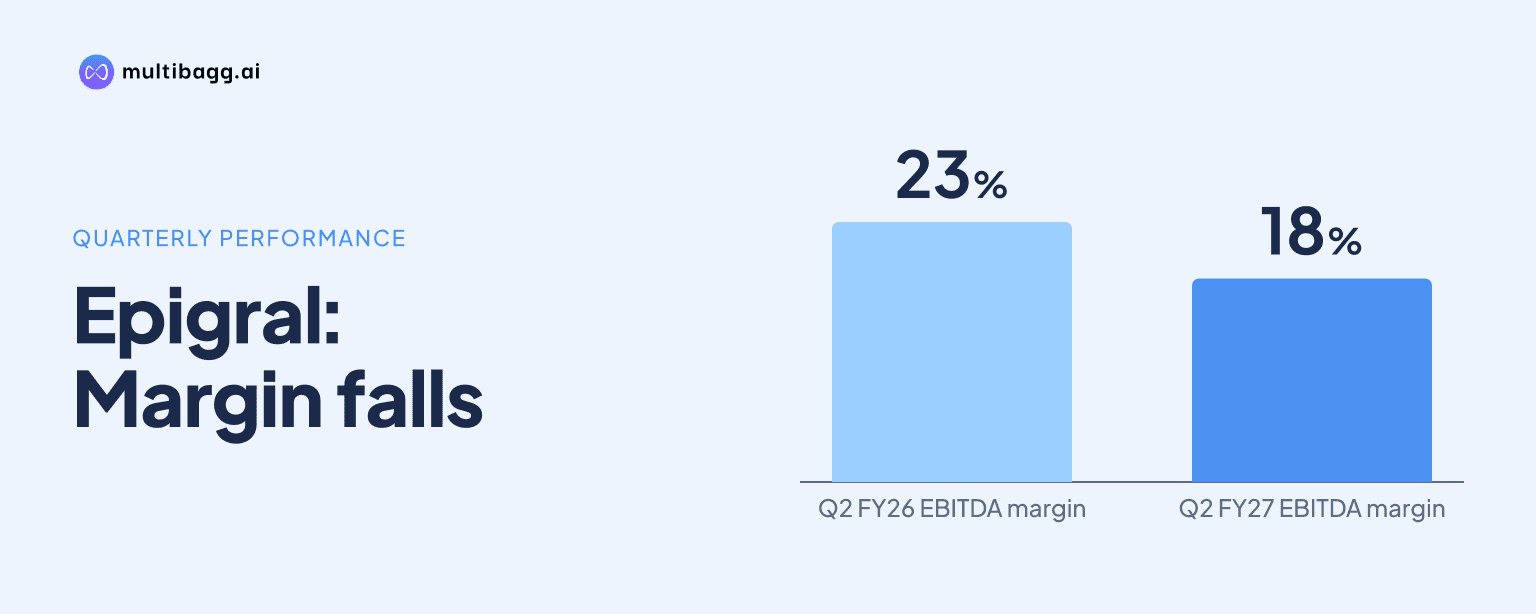
Epigral reported second-quarter FY27 (Q2FY27) revenue of Rs 752 crore, 28% above Q2FY26, but earnings before interest, tax, depreciation and amortisation (EBITDA) increased only 3% to Rs 136 crore. The EBITDA margin fell to 18% from 23% as Epigral cited high raw-material costs, despite 6% sales-volume growth and improved realisations.
Know Epigral inside out
Results, valuation, peers and who's buying, in one view.
Why did Epigral’s Q2FY27 revenue increase by 28%?
Epigral’s Q2FY27 revenue increased 28% year on year to Rs 752 crore from Rs 589 crore, driven by 6% sales-volume growth and improved realisations. Revenue was also Rs 43 crore above the Rs 709 crore reported in Q1FY27, despite the company describing market conditions as challenging and volatile.
The revenue mix moved further towards Derivatives and Specialty Chemicals during Q2FY27. This business contributed 57% of revenue, compared with 50% in Q2FY26 and 49% in Q1FY27, while Chlor-Alkali’s contribution declined to 43% from 50% a year earlier.
The Rs 163 crore year-on-year increase in revenue was substantially larger than the Rs 4 crore increase in EBITDA. Chairman and Managing Director Maulik Patel said volume growth and improved realisations lifted revenue, while elevated raw-material prices affected EBITDA margins.
Why did Epigral’s EBITDA margin fall to 18%?
Epigral’s Q2FY27 EBITDA margin fell to 18% because of high raw-material costs, although EBITDA increased to Rs 136 crore from Rs 132 crore in Q2FY26. The margin was 5 percentage points below the 23% recorded a year earlier and 7 percentage points below Q1FY27’s 25%.
Revenue increased by Rs 43 crore sequentially from Q1FY27, while EBITDA declined by Rs 43 crore from Rs 179 crore. The presentation attributes the muted Q2FY27 margin to raw-material costs and does not provide a separate raw-material cost amount or a detailed cost breakdown.
PAT rose 26% year on year to Rs 64 crore in Q2FY27 from Rs 51 crore, while PAT margin remained at 9%. That margin matched Q2FY26 but was below the 14% reported in Q1FY27, when PAT was Rs 99 crore.
Got a follow-up? Ask IRIS
How did Epigral perform in H1FY27?
Epigral reported first-half FY27 (H1FY27) revenue of Rs 1,461 crore, up 21% from Rs 1,204 crore in H1FY26, while EBITDA rose 7% to Rs 315 crore from Rs 296 crore. The H1FY27 EBITDA margin declined to 22% from 25%, extending the pattern of revenue growth exceeding operating-profit growth.
H1FY27 PAT was Rs 164 crore, compared with Rs 131 crore in H1FY26 on the comparison basis used in the financial table, and PAT margin stayed at 11%. Epigral said the Rs 131 crore H1FY26 figure excludes an Rs 81 crore reduction in deferred-tax liability after its shift to a 25.17% tax rate; including that reduction, reported H1FY26 PAT was Rs 212 crore.
Net debt to EBITDA was 0.9 times on September 30, 2026, compared with 0.8 times on September 30, 2025 and 0.8 times in Q1FY27. Return on capital employed was 15% in Q2FY27 versus 21% in Q2FY26, while return on equity was 13% versus 18%; the ratios use trailing-12-month EBITDA and PAT, and capital employed includes capital work in progress.
What capacity projects does Epigral expect to commission next?
Epigral spent Rs 88 crore on capital expenditure in H1FY27 and said its CPVC Resin, epichlorohydrin (ECH) and wind-solar hybrid power projects were in their final stages. Management said CPVC Resin and ECH expansions had entered trial runs and were expected to commission within a quarter.
The board has approved an Epoxy Resin and Formulations plant at Epigral’s existing Dahej complex with annual capacity of 1,25,000 tonnes. The project is expected to commission in H2FY28, and Epigral has set up a pilot plant to optimise the manufacturing process, validate product quality and facilitate customer approvals before commercial-scale production.
A Multi-Purpose Plant (MPP) downstream of the ECH and chlorotoluenes value chain is also planned for the Dahej complex, with H2FY28 expected commissioning. Epigral said the MPP will use ECH and chlorotoluenes as raw materials and serve agrochemical and pharmaceutical intermediates and water-treatment chemicals; management said the Epoxy Resin and Formulations and MPP projects were progressing as planned.
Conclusion
Epigral’s Q2FY27 results show a gap between sales growth and operating-profit growth: revenue rose 28% to Rs 752 crore, while EBITDA rose 3% to Rs 136 crore and margin fell to 18%. In H1FY27, revenue increased 21% to Rs 1,461 crore and EBITDA increased 7% to Rs 315 crore, with margin declining to 22% from 25%.
The next disclosed milestones are the expected commissioning of CPVC Resin and ECH expansions within a quarter following trial runs, and H2FY28 commissioning targets for the 1,25,000-tonne Epoxy Resin and Formulations plant and the MPP. Management also said the second half of the financial year has traditionally delivered stronger performance than the first half and maintained a positive outlook for H2FY27.