










Fineotex Chemical Limited Reports 169% Q2 Income Growth
Key highlights
- FCL reported Q2 FY27 consolidated total income of about ₹391 crore, up 169% year on year.
- H1 FY27 consolidated total income rose 166.8% to ₹778.13 crore, while EBITDA rose 111.2% to ₹118.74 crore.
- Q2 FY27 profit after tax was about ₹45 crore, up about 71% year on year.
- FCL shares were down 16.43% over one month but up 75.77% over one year in the provided market data.
powered by IRIS
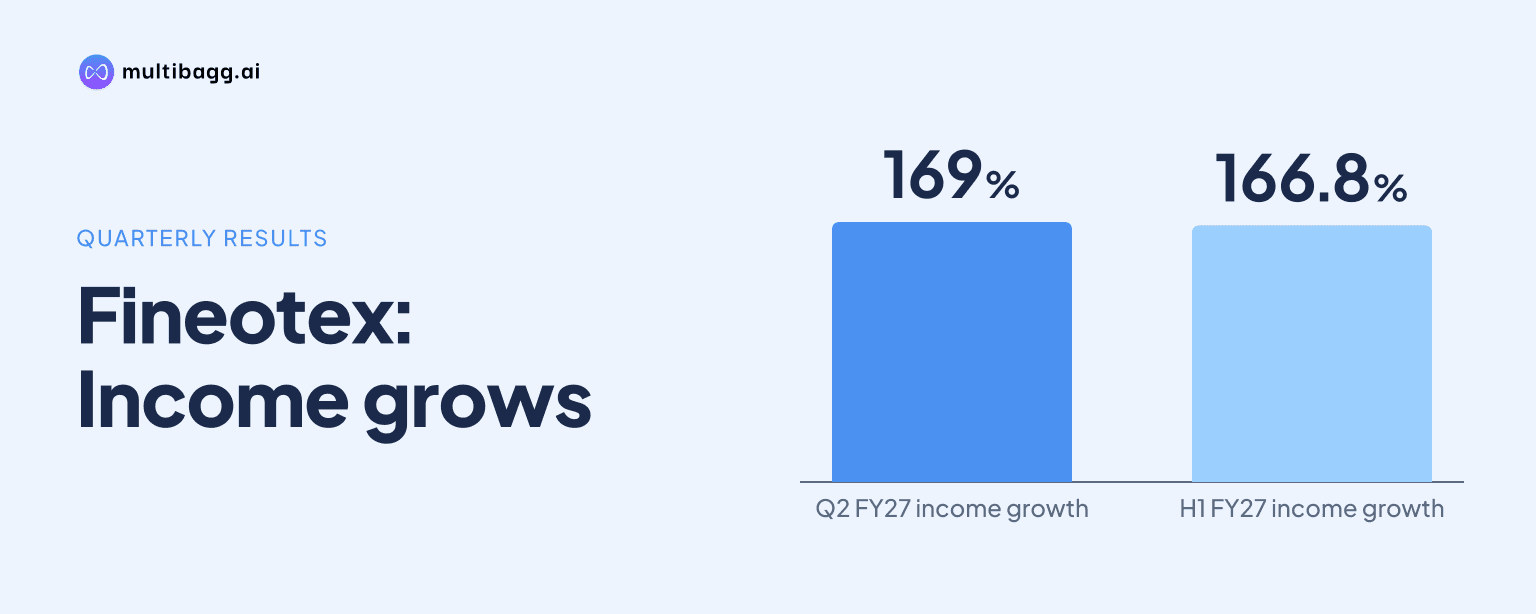
Fineotex Chemical Limited reported about ₹391 crore in consolidated total income for Q2 FY27, up 169% year on year, while profit after tax rose about 71% to ₹45 crore. The performance reflected the larger business base following the CrudeChem acquisition, although management indicated that blended margins are moderating from historic levels.
Know Fineotex Chemical inside out
Results, valuation, peers and who's buying, in one view.
What did FCL report for Q2 and H1 FY27?
FCL reported consolidated total income of about ₹391 crore in Q2 FY27, compared with year-earlier levels, with operating EBITDA rising about 92% to nearly ₹60 crore. Consolidated profit after tax increased about 71% year on year to approximately ₹45 crore for the quarter ended September 30, 2026.
For the first half of FY27, consolidated total income rose 166.8% year on year to ₹778.13 crore. Operating EBITDA increased 111.2% to ₹118.74 crore, while profit after tax grew 81.5% to ₹92.75 crore. Management also said business volumes increased by around 132.3% during the first half, reflecting the expanded scale of operations.
The strong reported growth makes the acquisition-led change in FCL's business mix central to assessing the numbers. Management's comments on margins and new business lines indicate that revenue scale alone is not the only issue investors will track over subsequent quarters.
How did the CrudeChem acquisition affect FCL's results?
The CrudeChem acquisition was identified as the main driver of the sharp growth in FCL's reported revenue and scale. Management described the oil and gas business as a major part of the company's enlarged international footprint and said CrudeChem was expected to remain around 90% to 95% of the oil and gas business line.
However, management also said blended EBITDA and profit-after-tax margins could move closer to historic levels over the next couple of years. This indicates that the acquired business has changed the consolidated mix, with fast growth not necessarily translating into an immediate return to earlier consolidated margin levels.
FCL said it already supplies oil and gas customers in India, including Oil India, ONGC and Reliance. Management characterised the domestic opportunity as smaller and more refining-led than overseas markets, while identifying the US business through CrudeChem as the larger growth engine. It also referred to shipping from India after required plant certification and product approvals during FY27.
Got a follow-up? Ask IRIS
What businesses is FCL developing beyond textiles?
FCL identified four operating areas: textile specialties, cleaning and hygiene, oil and gas, and water treatment. The company said its cleaning and hygiene plant is FDA certified. The strategy outlined on the call is to broaden the business beyond its established textile chemical operations while using manufacturing and technical capabilities across India, Malaysia and the United States.
Water treatment was a key area of management discussion. FCL said it was already conducting water-treatment business from India and expected water-treatment orders to be in hand by Q4 FY27. Fineotex America was also expected to launch a dedicated water-treatment website within one to two weeks of the November 16 call.
Management referred to an earlier planning base of ₹3,000 crore in revenue by FY28 and to an objective of doubling EBITDA margins. But it also said the ₹3,000 crore plan may not be reached in FY28 or FY29, describing it as a planning benchmark rather than a confirmed forecast. It estimated a consolidated effective tax rate of around 17% to 20% going forward.
How has the market viewed FCL's recent performance?
FCL's share price was down 1.17% over one day, 16.98% over one week and 16.43% over one month in the data provided. The stock was nevertheless up 29.21% over six months and 75.77% over one year, showing that the recent correction followed a strong longer-term performance.
The comparison set showed varied returns among chemical and related companies. Yasho Industries was up 127.60% over one year, while Archean Chemical was down 21.22%. These figures provide market context but do not establish a direct causal link between FCL's quarterly financial results and its share-price movements.
For investors, the Q2 results place attention on the quality and durability of acquisition-led growth. Revenue, volume growth, the margin trajectory, certification progress and the conversion of water-treatment discussions into orders are the disclosed operating markers that can be monitored using future company updates.
How was the Q2 FY27 earnings call disclosed?
FCL held its investor and analyst conference call on November 16, 2026, to discuss second-quarter and first-half FY27 financial performance. The company subsequently said the audio recording was made available on its website on November 17, 2026 for investors and other stakeholders.
The disclosure was made under Regulation 46(2)(oa) of the SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015, and was addressed to BSE and NSE. The information supplied confirms the availability of an audio recording but does not state that a presentation, earnings deck, live webcast or company-filed transcript was released.
Conclusion
FCL's Q2 FY27 update showed a substantial rise in consolidated income, EBITDA and profit after tax, led by the expanded scale created by CrudeChem. At the same time, management's margin comments show that the business mix and profitability of newer operations remain as important as the headline revenue growth.
The next disclosed milestones include expected water-treatment orders by Q4 FY27 and potential shipments from India during FY27 after certification and product approvals. Investors will also watch whether FCL gives more specific updates on its revenue planning base, oil and gas execution and the path of blended EBITDA margins.