










Gammon restates FY26 loss after Rs 70.40 crore omission
Key highlights
- Gammon restated FY26 consolidated loss after tax to Rs 1,099.95 crore from Rs 1,170.34 crore.
- Metropolitan Infrahousing settled Rs 80.40 crore of dues for Rs 10 crore, creating a Rs 70.40 crore omitted write-back.
- FY26 current borrowings were restated to Rs 27.48 crore from Rs 68.18 crore.
- Gammon reported current liabilities exceeded current assets by Rs 14,821.86 crore at September 30, 2026.
powered by IRIS
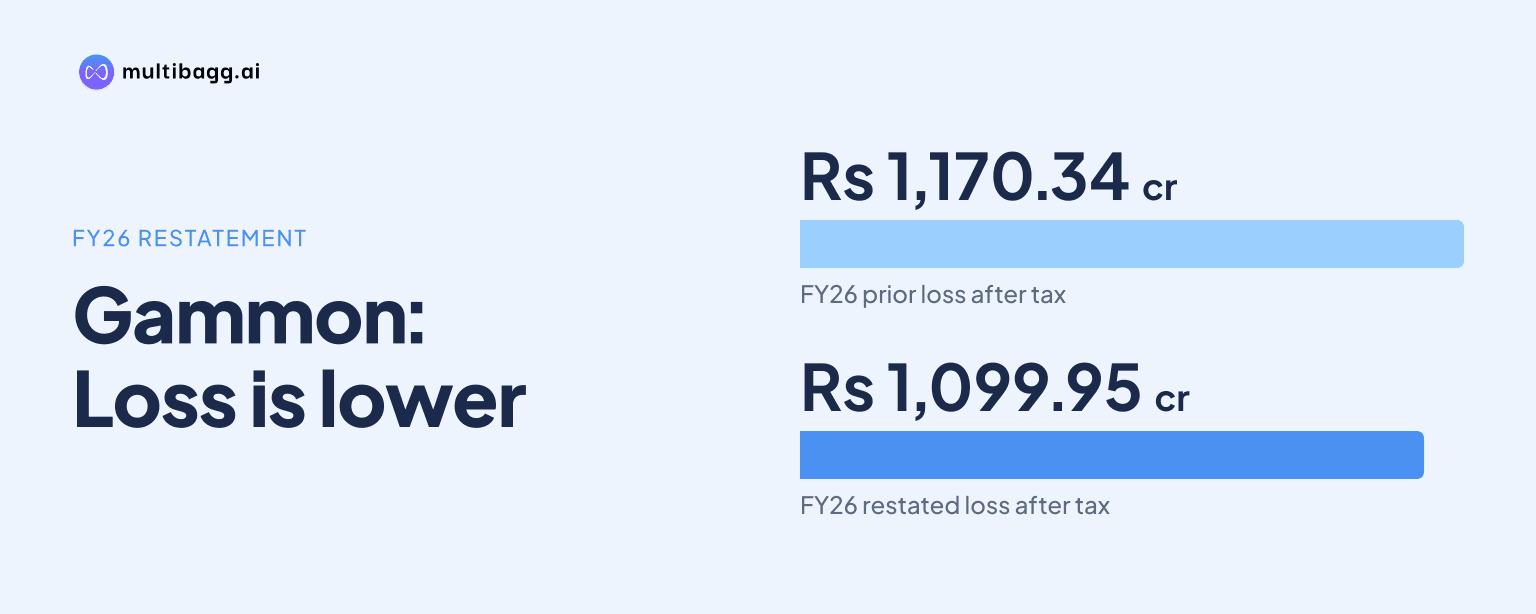
Gammon India Limited restated its consolidated FY26 loss after tax to Rs 1,099.95 crore from Rs 1,170.34 crore after Metropolitan Infrahousing Private Limited omitted a Rs 70.40 crore settlement gain. The retrospective correction relates to an Rs 80.40 crore liability settled for Rs 10 crore on November 3, 2025.
Know Gammon India inside out
Results, valuation, peers and who's buying, in one view.
Why did Gammon restate its FY26 consolidated results?
Gammon restated FY26 because Metropolitan Infrahousing did not account for a debt settlement with Gactel Turnkey Projects Limited in its financial statements for the year ended March 31, 2026. Under the agreement dated November 3, 2025, the subsidiary paid Rs 10 crore in full and final settlement of Rs 80.40 crore in outstanding dues.
The Rs 80.40 crore liability comprised Rs 50.70 crore of principal and Rs 29.70 crore of accrued interest. Metropolitan Infrahousing inadvertently did not write back the remaining Rs 70.40 crore liability or recognise that amount as income in FY26, prompting a correction in FY27 and a retrospective restatement of Gammon's FY26 consolidated comparative figures.
Gammon said it applied Indian Accounting Standard 8, or Ind AS 8, on accounting policies, changes in accounting estimates and errors. The company has presented affected FY26 comparative line items as a restated balance sheet and restated profit and loss statement, while its standalone financial results were not affected.
How much did the settlement change Gammon's FY26 loss?
Gammon's restated consolidated loss after tax for the year ended March 31, 2026 was Rs 1,099.95 crore, compared with the previously reported Rs 1,170.34 crore loss. The Rs 70.40 crore adjustment also increased other income to Rs 179.74 crore from Rs 109.35 crore and total income to Rs 274.22 crore from Rs 203.83 crore.
The adjustment also changed the allocation of FY26 results. Loss attributable to Gammon owners was restated to Rs 1,110.32 crore from Rs 1,169.56 crore, while non-controlling interest changed to a Rs 10.37 crore profit from a Rs 0.78 crore loss.
Gammon's basic and diluted loss per equity share were each restated to Rs 30.10 from Rs 31.71. The disclosed per-share adjustment was Rs 1.61 for both measures, and total comprehensive loss attributable to owners was restated to Rs 1,498.50 crore from Rs 1,557.74 crore.
How did the correction change Gammon's liabilities and equity?
Gammon restated current borrowings at March 31, 2026 to Rs 27.48 crore from Rs 68.18 crore, reflecting a Rs 40.70 crore adjustment. Other financial liabilities were restated to Rs 13,714.82 crore from Rs 13,744.52 crore, a Rs 29.70 crore adjustment corresponding to accrued interest in the settled obligation.
Other equity was restated to a deficit of Rs 13,106.53 crore from a deficit of Rs 13,165.77 crore. The Rs 59.25 crore adjustment was the portion attributable to Gammon owners, while non-controlling interest improved by Rs 11.15 crore to a negative Rs 109.74 crore.
The balance-sheet change reflects the settlement of the Rs 80.40 crore liability for Rs 10 crore. Although the restatement reduced reported current liabilities and the other-equity deficit at March 31, 2026, the consolidated FY26 result remained a loss of Rs 1,099.95 crore.
Got a follow-up? Ask IRIS
Did the restatement affect Gammon's FY27 results or cash flows?
Gammon said the restatement did not affect its statement of profit and loss for the quarter and half year ended September 30, 2026, or for the quarter ended June 30, 2026. The company instead recorded the FY26 error through retrospective comparative adjustments under Ind AS 8.
The company also reported no effect on net cash flows from operating, investing or financing activities for the year ended March 31, 2026 and the half year ended September 30, 2026. This distinguishes the accounting correction from reported cash-flow categories in the FY26 and FY27 interim statements.
Gammon's standalone financial results were unchanged because the transaction arose at Metropolitan Infrahousing. The consolidated results changed because they include the subsidiary's income, liabilities, equity and non-controlling-interest allocation.
What other reporting matters did Gammon disclose?
Gammon's unaudited consolidated results for the quarter and half year ended September 30, 2026 were approved by the board on November 6, 2026, and its statutory auditors issued a modified conclusion. The auditors' matters included Rs 10 crore of contract claims recognised by Gammon and lender-imposed penal, incremental interest and other charges.
Gammon said lenders levied Rs 24.55 crore of such charges during the September 2026 half year, taking the cumulative amount to Rs 416.30 crore based on available loan statements. CFM Assets Reconstruction Company Private Limited, an asset reconstruction company, had also levied Rs 519.78 crore of charges after acquiring debt from Gammon's lenders.
At September 30, 2026, Gammon reported current liabilities exceeding current assets by Rs 14,821.86 crore. Management said it continued to prepare accounts on a going-concern basis, while identifying material uncertainty around lender acceptance of its resolution plan, claim recoveries, investment monetisation and debt-settlement proposals.
Conclusion
Gammon's FY26 restatement corrects an omitted Rs 70.40 crore income recognition at Metropolitan Infrahousing after the subsidiary settled Rs 80.40 crore of dues for Rs 10 crore. The correction reduced the consolidated FY26 loss by Rs 70.40 crore, lowered current liabilities and improved other equity, without changing standalone results or reported cash-flow categories.
The next disclosed matter to watch is the lender-resolution process. Management said a resolution plan approved by some lenders in 2021 remains under discussion, while Rs 936.09 crore of penal interest, incremental interest and other charges remains contingent and unaccounted for as of September 30, 2026.