










Geetanjali Credit and Capital reports Rs 4.3134 crore tax matters
Key highlights
- Geetanjali Credit and Capital disclosed four quantified tax matters worth Rs 4.3134 crore.
- The AY 1999-00 case totals Rs 3.3167439 crore of demand and interest.
- The AY 2000-01 matter totals Rs 68.41556 lakh and remains pending after remand.
- The AY 2018-19 portal-recorded pending amount is Rs 30.83867 lakh.
powered by IRIS
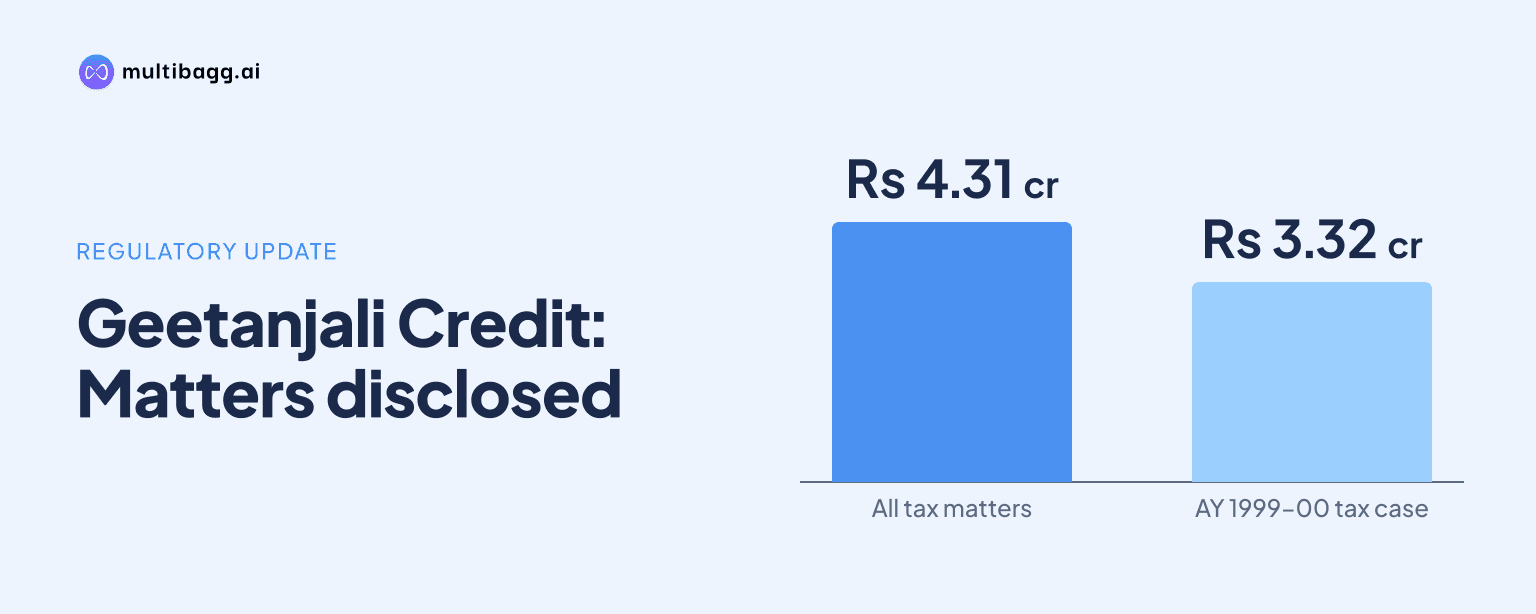
Geetanjali Credit and Capital Limited disclosed four pending income-tax matters with a quantified aggregate amount of Rs 4.3134 crore in its Letter of Offer, led by disputed reassessment matters for assessment years, or AYs, 1999-00 and 2000-01 that remain pending after a January 15, 2019 remand.
Know Geetanjali Credit and Capital inside out
Results, valuation, peers and who's buying, in one view.
What tax matters are pending against Geetanjali Credit and Capital?
Geetanjali Credit and Capital reported four tax-liability matters totalling Rs 4.3134 crore, to the extent quantifiable, as of the Letter of Offer date. The litigation summary records nil cases involving statutory or regulatory actions, moral turpitude or criminal liability, material statutory violations, economic offences, and other matters exceeding the company’s materiality threshold.
The four matters cover AY 1999-00, AY 2000-01, AY 2015-16 and AY 2018-19. The two legacy cases account for Rs 3.3167439 crore and Rs 68.41556 lakh respectively, while the Income Tax Department website showed pending amounts of Rs 41,611 for AY 2015-16 and Rs 30.83867 lakh for AY 2018-19.
The Rs 4.3134 crore figure is the amount in the litigation summary, not an indication that Geetanjali Credit and Capital has accepted every demand. The Letter of Offer explicitly says the AY 1999-00 and AY 2000-01 demands were disputed, while the status of the two older matters is pending following remand for decisions on merits.
How did the 1999-00 and 2000-01 disputes reach remand?
Geetanjali Credit and Capital’s AY 1999-00 matter began with a March 16, 2006 notice issued under Section 143(3) of the Income-tax Act, 1961, raising a demand of Rs 1.347281 crore plus interest of Rs 1.9694629 crore. The combined Rs 3.3167439 crore is the largest individual amount among the four tax matters disclosed.
For AY 2000-01, a separate March 16, 2006 notice under Section 143(3) raised a demand of Rs 27.8115 lakh and interest of Rs 40.60406 lakh. The combined amount of Rs 68.41556 lakh was lower than the AY 1999-00 amount, but it exceeded the Rs 30.83867 lakh portal-recorded amount later disclosed for AY 2018-19.
Geetanjali Credit and Capital appealed both matters before the Income Tax Appellate Tribunal, Division Bench, Chandigarh, through ITA Nos. 920 and 921/CHD/2008. According to the Letter of Offer, the Tribunal’s April 22, 2016 order deleted an addition of Rs 2.10 crore, set aside the orders of the authorities and quashed reopening of the assessments under Sections 147 and 148.
The revenue appealed the Tribunal’s decision to the High Court of Delhi through Income Tax Appeal Nos. 74/2017 and 75/2017. In a common January 15, 2019 order, the High Court decided in favour of the revenue and remanded both cases for decisions on merits after considering the facts and circumstances recorded by the Assessing Officer and the first appellate authority; Geetanjali Credit and Capital says the remanded matters remain pending.
Got a follow-up? Ask IRIS
What are Geetanjali Credit and Capital’s newer tax demands?
For AY 2015-16, Geetanjali Credit and Capital received a January 13, 2020 show-cause notice under Section 154 proposing rectification of an assessment made under Section 143(3). The issue concerned Rs 68,500 of filing fees related to an increase in share capital, which the tax department alleged was capital expenditure rather than revenue expenditure.
Communications dated February 4, 2022 and June 23, 2022 proposed rectification on the basis of under-assessed income of Rs 68,500 and a short tax levy of Rs 27,940, including applicable interest. The Assessing Officer issued a Section 154 rectification order on July 5, 2022 raising a demand of Rs 27,940, while the department website later showed Rs 27,940 plus Rs 13,671 interest pending, totalling Rs 41,611.
For AY 2018-19, a March 14, 2023 order under Sections 147, 144 and 144B added Rs 16 lakh to returned income of nil as unexplained cash credit under Section 68 read with Section 115BBE. It resulted in a demand of Rs 20.69457 lakh, comprising Rs 12.36 lakh in tax, Rs 8.30887 lakh in interest under Sections 234A, 234B and 234C, and Rs 2,570 relating to a refund already issued.
A separate September 29, 2023 order under Section 271AAC(1) imposed a penalty of Rs 1.236 lakh for AY 2018-19. Geetanjali Credit and Capital also says the department website showed Rs 21.9244 lakh plus interest of Rs 8.91427 lakh pending, or Rs 30.83867 lakh; that portal amount differs from a simple addition of the earlier Rs 20.69457 lakh assessment demand and Rs 1.236 lakh penalty.
What does the Letter of Offer say about other legal and financial disclosures?
Geetanjali Credit and Capital reported nil litigation involving directors, promoters or promoter group, while also stating that it is professionally managed and has no identifiable promoter. The same litigation table records nil proceedings involving criminal liability, material statutory violations and economic offences, alongside the four quantified tax matters worth Rs 4.3134 crore.
The Letter of Offer says neither Geetanjali Credit and Capital nor its directors had been identified as wilful defaulters or fraudulent borrowers under the Securities and Exchange Board of India Issue of Capital and Disclosure Requirements Regulations. It also states that the company complied with Securities and Exchange Board of India Listing Regulations during the three years immediately before the Letter of Offer.
Geetanjali Credit and Capital states that it had no contingent liabilities under Indian Accounting Standard 37, known as Ind AS 37, as of the Letter of Offer date. That disclosure does not set out an accounting classification for each of the four tax matters, including the Rs 3.3167439 crore AY 1999-00 case and the Rs 68.41556 lakh AY 2000-01 case.
The company proposes a rights issue with gross proceeds of up to Rs 88.384 crore and net proceeds of up to Rs 87.684 crore after issue expenses of up to Rs 70 lakh. It proposes to use up to Rs 79.684 crore to augment capital for lending business activities and up to Rs 8 crore for general corporate purposes, rather than identifying tax demands as a specific use of proceeds.
Conclusion
The disclosed tax litigation is concentrated in the two older reassessment matters, with AY 1999-00 alone accounting for Rs 3.3167439 crore and AY 2000-01 accounting for Rs 68.41556 lakh. The AY 2015-16 amount of Rs 41,611 and AY 2018-19 portal-recorded amount of Rs 30.83867 lakh are materially smaller, although the latter includes an assessment-related demand and a separate penalty order.
The next disclosed matter to watch is the merits-based resolution of the AY 1999-00 and AY 2000-01 proceedings, which have remained pending since the High Court’s January 15, 2019 remand. Geetanjali Credit and Capital also plans to raise net proceeds of up to Rs 87.684 crore through its rights issue, subject to the disclosed 90% minimum subscription requirement.