










Godrej Consumer Q2 FY27 Outlook Signals High-Teens Growth
Key highlights
- GCPL expects high-teens consolidated revenue growth, high-single-digit underlying volume growth and double-digit EBITDA growth in Q2 FY27.
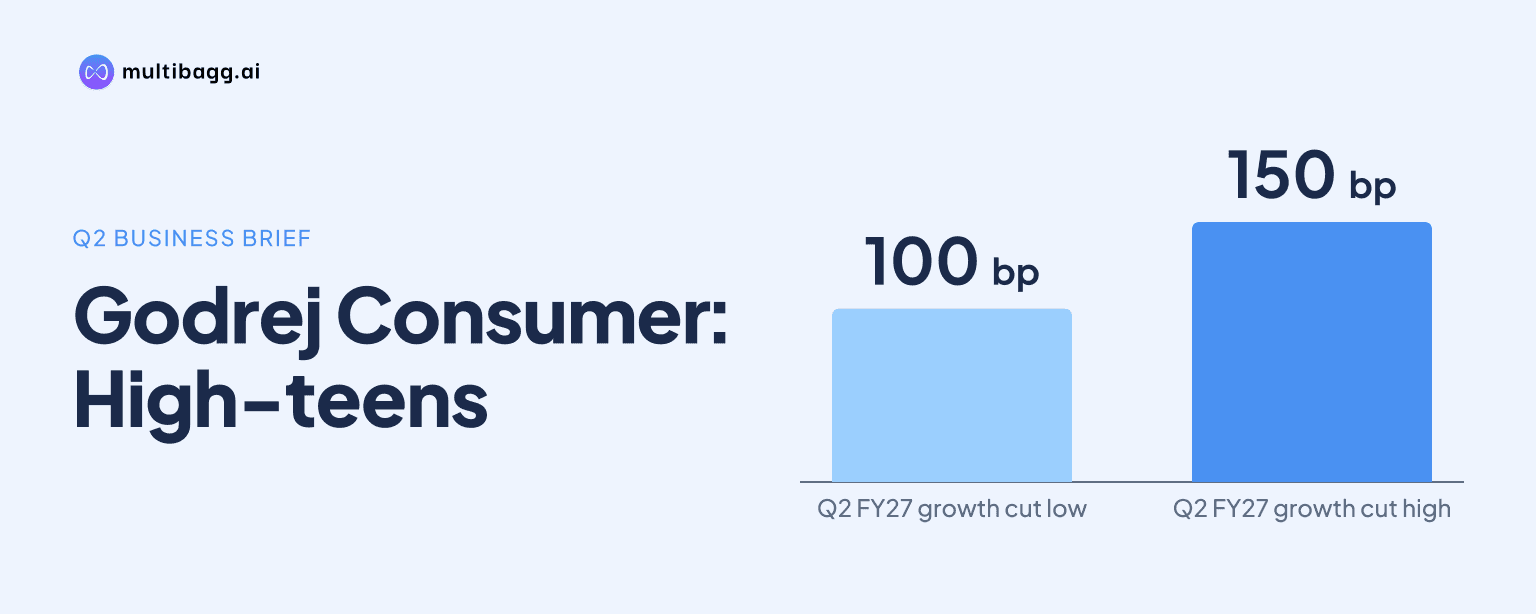
- GCPL’s India business is expected to grow revenue in the teens, with trade inventory correction reducing reported growth by around 100 to 150 basis points.
- Indonesia is expected to deliver high-teens revenue growth with high-single-digit volume expansion in Q2 FY27.
- GCPL’s board will meet on October 29, 2026, to consider Q2 FY27 results and an interim dividend.
powered by IRIS
Godrej Consumer Products Ltd (GCPL) expects high-teens consolidated revenue growth for the quarter ended September 2026, supported by broad-based momentum across India, Indonesia and the GAUM business. The FMCG company has also guided for high-single-digit underlying volume growth and double-digit EBITDA growth for Q2 FY27. Its quarterly update indicates that demand remained resilient across key markets, although consumption conditions were uneven. The outlook comes ahead of the company’s board meeting scheduled for October 29, 2026. The board will consider the unaudited financial results for the quarter and half year ended September 30, 2026, along with an interim dividend declaration.
Know Godrej Consumer Products inside out
Results, valuation, peers and who's buying, in one view.
Q2 FY27 result date and board agenda
GCPL informed the BSE that its board of directors is scheduled to meet on October 29, 2026. The stated agenda includes taking on record the unaudited Q2 and first-half financial results. The board will also consider the declaration of an interim dividend. The company has scheduled a conference call on the same date to discuss its Q2 FY27 performance. Its detailed financial update is expected after board approval of the results.
Consolidated growth outlook remains firm
The company expects consolidated revenue growth in the high teens for Q2 FY27. Underlying volume growth is expected to be in the high single digits, while EBITDA is projected to grow in double digits. GCPL said the expected performance reflects momentum across its operating markets. This guidance is based on internal unaudited management reports and is not the final reported result. The company said it remains focused on delivering performance in line with its annual guidance. It also said it is confident of exceeding annual guidance in select areas through broad-based growth.
India business faces inventory adjustment
For its standalone business, which mainly represents the domestic operations, GCPL expects revenue growth in the teens. Underlying volume growth is expected in the high single digits. Both Personal Care and Home Care portfolios are expected to contribute to the performance. However, trade inventory correction is estimated to reduce reported growth by around 100 to 150 basis points. This means channel-level inventory adjustments may affect the reported growth rate even as underlying consumer demand and volume trends remain positive. The company has described the India performance as broad-based rather than concentrated in one portfolio.
Indonesia and GAUM remain growth contributors
Indonesia, GCPL’s second-largest business after India, is expected to deliver high-teens revenue growth. The company has indicated that this growth will be supported by high-single-digit volume expansion. Its GAUM business is also identified as one of the businesses supporting the consolidated growth outlook. GCPL has said India, Indonesia and GAUM continue to provide multiple engines of growth. The international businesses are therefore important to the company’s consolidated revenue and volume performance, particularly when domestic consumption conditions are uneven.
Commodity inflation remains a key operating issue
GCPL said input cost pressures intensified during the September quarter. Some commodities had started moderating toward the end of Q1 FY27, but inflation returned in Q2 across several raw-material baskets. The company specifically identified crude-linked derivatives, palm oils and other commodity inputs as areas of renewed cost pressure. These costs are relevant for an FMCG business with exposure to personal-care and home-care product categories. The company said it is responding through calibrated pricing actions, cost-saving initiatives, supply-chain efficiencies and disciplined cost management. It added that it has managed larger commodity cycles in the past and aims to address current pressures without compromising its growth agenda.
Monsoon conditions affect consumption backdrop
The company said consumption during the quarter was affected by uneven monsoon conditions linked to an intensifying El Niño. This was cited alongside commodity inflation as a factor creating a more demanding operating environment. At the same time, GCPL noted that the quarter had a supportive comparator. The Q2 outlook therefore combines a favourable comparison base with operational pressures from weather-linked consumption variability and higher costs. Its emphasis on high-single-digit volume growth indicates that the company is tracking consumer demand separately from the impact of pricing and trade inventory movement.
Got a follow-up? Ask IRIS
Q1 FY27 provides the immediate financial base
GCPL reported revenue of ₹4,225 crore in Q1 FY27, according to the data provided. Revenue rose 8.33% quarter-on-quarter and 15.39% year-on-year. Gross profit was ₹726 crore, down 5.11% sequentially but up 14.32% from a year earlier. Net profit was ₹504 crore, showing growth of 11.68% quarter-on-quarter and 11.51% year-on-year. A separate results preview cited Q1 FY27 operating profit of ₹801 crore and operating margin of 18.96%, while referring to net profit of ₹505 crore. The difference of ₹1 crore in the net-profit references should be assessed against the company’s reported financial statements.
Year-ago quarter sets the comparison base
The Q2 FY26 base quarter reported revenue of ₹3,825 crore, operating profit of ₹733 crore and a 19.00% operating margin. Net profit in that September 2025 quarter was ₹459 crore. These figures form the year-on-year reference point for the upcoming Q2 FY27 results. The company’s expectation of high-teens consolidated revenue growth indicates a stronger revenue trajectory than the growth rate reported in Q1 FY27. However, the final assessment will also depend on volumes, margins, pricing and the extent of commodity-cost impact.
What investors will track in the results
Investors will focus on whether reported consolidated revenue matches the high-teens growth expectation. The trend in underlying volumes will be important because the company expects a high-single-digit expansion despite uneven monsoons and an estimated trade inventory correction in India. EBITDA growth and margin commentary will show the effect of higher palm oil, crude-linked derivative and other commodity costs. Market participants will also watch for details on pricing actions and savings measures. Updates from Indonesia and GAUM will help explain the contribution of international operations to overall growth. The board’s decision on an interim dividend will be another event-specific item on October 29.
Why the update matters for the FMCG sector
GCPL’s update highlights the balance consumer-goods companies must manage between demand growth and raw-material inflation. Volume growth remains a key measure of consumption health, while pricing can support revenue but may not fully offset higher costs. Inventory changes in trade channels can also affect reported sales growth for a quarter without necessarily reflecting end-consumer demand. For GCPL, the stated strength in Personal Care, Home Care, Indonesia and GAUM provides context for its consolidated outlook. The final Q2 FY27 financial results will clarify the extent to which this broad-based growth has translated into revenue, profitability and cash-return decisions.
Conclusion
Godrej Consumer Products expects high-teens consolidated revenue growth, high-single-digit volume growth and double-digit EBITDA growth in Q2 FY27. Its domestic business is expected to grow in the teens despite a 100 to 150 basis point effect from trade inventory correction. Rising input costs and uneven monsoon conditions remain important variables. The company’s October 29 board meeting and conference call are the next confirmed events for investors tracking its Q2 FY27 performance and interim dividend decision.