










Gulshan Polyols ethanol EBITDA margin reaches 16% in H1 FY27
Key highlights
- Gulshan Polyols’ ethanol EBITDA margin rose to 16% in H1 FY27 from 8% in H1 FY26.
- Ethanol EBITDA increased 123% to Rs 143 crore as H1 FY27 revenue reached Rs 873 crore.
- Ethanol utilisation reached 82% in H1 FY27, compared with 74% a year earlier.
- Gulshan Polyols holds a Rs 1,305 crore ethanol order book for 19.7 crore litres in ethanol supply year 2026-27.
powered by IRIS
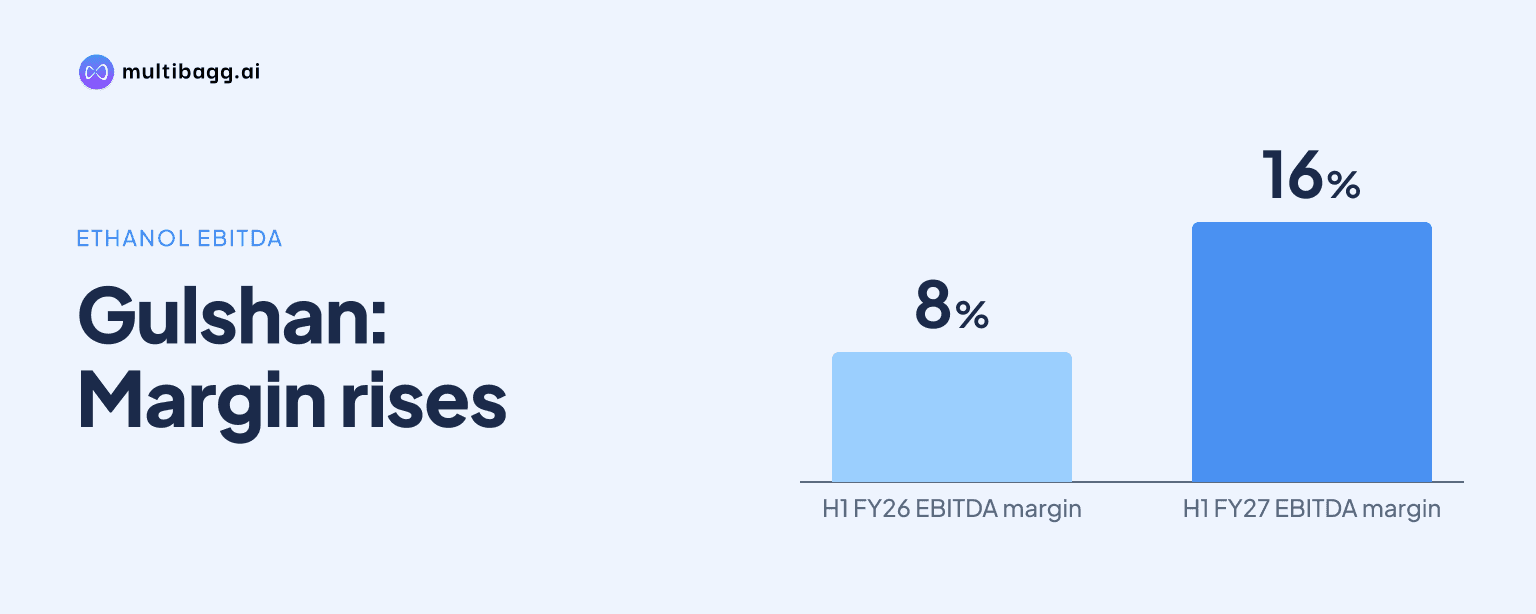
Gulshan Polyols Limited reported a 16% ethanol earnings before interest, tax, depreciation and amortisation (EBITDA) margin in H1 FY27, compared with 8% in H1 FY26, as utilisation rose to 82%. Ethanol EBITDA increased 123% to Rs 143 crore on Rs 873 crore of revenue, while volume rose to 11 crore litres.
Know Gulshan Polyols inside out
Results, valuation, peers and who's buying, in one view.
How did Gulshan Polyols’ ethanol profitability change in H1 FY27?
Gulshan Polyols’ ethanol profitability increased in H1 FY27, with EBITDA rising to Rs 143 crore from Rs 64 crore in H1 FY26. Segment revenue grew 11% to Rs 873 crore from Rs 790 crore, while EBITDA margin expanded by 828 basis points, where one basis point equals one-hundredth of a percentage point, to 16% from 8%.
Ethanol volume increased to 11 crore litres in H1 FY27 from 10 crore litres in H1 FY26, and capacity utilisation rose to 82% from 74%. Gulshan Polyols operates three distillery units with aggregate capacity of 810 kilolitres per day, comprising 60 kilolitres per day and 500 kilolitres per day in Madhya Pradesh and 250 kilolitres per day in Assam.
What does Gulshan Polyols’ Q2 FY27 ethanol performance show?
Gulshan Polyols reported a 15% ethanol EBITDA margin in Q2 FY27, compared with 9% in Q2 FY26 and 16% for H1 FY27. Quarterly revenue increased 10% to Rs 427 crore from Rs 387 crore, while EBITDA rose 89% to Rs 62 crore from Rs 33 crore.
Quarterly ethanol volume was 5 crore litres in both Q2 FY26 and Q2 FY27, but utilisation rose to 80% from 75%. The margin improvement of 614 basis points occurred despite unchanged reported quarterly volume, and Q2 FY27 EBITDA of Rs 62 crore formed part of the Rs 143 crore reported for the first half.
What is supporting Gulshan Polyols’ ethanol margin?
Gulshan Polyols is using a feedstock mix comprising 50% Food Corporation of India rice, 25% maize and 25% broken rice and damaged food grains. Management said it is increasing use of Food Corporation of India rice and damaged food grains while limiting open-market maize purchases to address elevated maize prices and policy revisions.
Management said the revised procurement approach is intended to manage input costs and sustain margins, while its FY27 guidance remains unchanged. The presentation also states that ethanol prices are delinked from crude oil or petrol prices, while the goods and services tax on ethanol is 5%, compared with 18% previously.
How much ethanol demand is covered by Gulshan Polyols’ order book?
Gulshan Polyols has been allocated 19.7 crore litres for ethanol supply year 2026-27 under long-term oil marketing company offtake arrangements, representing an order book of Rs 1,305 crore. The allocated volume compares with installed annual ethanol capacity of 26 crore litres and gives the company disclosed supply visibility for the ethanol supply year.
Management is targeting ethanol capacity utilisation of 80% to 90% in FY27, compared with 82% achieved in H1 FY27. Ethanol contributed 70% of total revenue in FY26, according to the presentation, while distilled dried grains with solubles and other by-products accounted for 25% of ethanol revenue.
Got a follow-up? Ask IRIS
How are Gulshan Polyols’ other segments and expansion plans progressing?
Gulshan Polyols’ grain-processing revenue increased to Rs 335 crore in H1 FY27 from Rs 301 crore in H1 FY26, while EBITDA increased to Rs 11 crore from Rs 4 crore. However, Q2 FY27 grain-processing EBITDA was Rs 2 crore, compared with Rs 4 crore in Q2 FY26, despite quarterly revenue rising to Rs 166 crore from Rs 133 crore.
Mineral-processing revenue rose to Rs 47 crore in H1 FY27 from Rs 45 crore in H1 FY26, but EBITDA declined to Rs 10 crore from Rs 11 crore and margin fell to 22% from 26%. Gulshan Polyols plans to add 30,000 metric tonnes per annum of sorbitol capacity, taking total capacity to 110,000 metric tonnes per annum, and to increase maltodextrin powder and non-dairy creamer capacity to 30,000 metric tonnes per annum from 5,000 metric tonnes per annum by April 2027.
Management has retained FY27 consolidated revenue guidance of Rs 2,600 crore, an EBITDA margin target of 10% to 11% and a profit after tax margin target of 5% to 6%. Separately, Gulshan Polyols has partnered with Zero Footprint Industries Limited to establish a 6-megawatt green-hydrogen plant at its sorbitol facility under a build-own-operate model, supported by a Rs 300 crore supply contract.
Conclusion
Gulshan Polyols’ H1 FY27 results show ethanol was the largest contributor to the group’s reported profit improvement, with segment EBITDA increasing by Rs 79 crore and margin reaching 16% as utilisation rose eight percentage points to 82%. The segment’s 11% revenue growth contrasted with an EBITDA decline in mineral processing, while grain processing recorded higher half-year EBITDA despite lower Q2 EBITDA.
The next disclosed markers are management’s 80% to 90% FY27 ethanol-utilisation target, delivery against the 19.7 crore-litre allocation for ethanol supply year 2026-27, and the April 2027 target to commission the sorbitol and maltodextrin powder and non-dairy creamer projects. Management’s stated feedstock shift away from open-market maize is also relevant to its unchanged 10% to 11% consolidated EBITDA-margin target.