










Harsha Engineers International revenue rises 25.2% in Q1 FY27
Key highlights
- Harsha Engineers International reported Q1 FY27 consolidated revenue of ₹457.43 crore, up 25.2% year on year.
- India Engineering, including HEIL and Advantek, grew 21% year on year in Q1 FY27.
- Q1 FY27 operating profit was ₹67 crore and operating profit margin was 14.66%.
- A ₹4 crore forex loss and around ₹3 crore of higher indirect-material costs added to margin pressure.
powered by IRIS
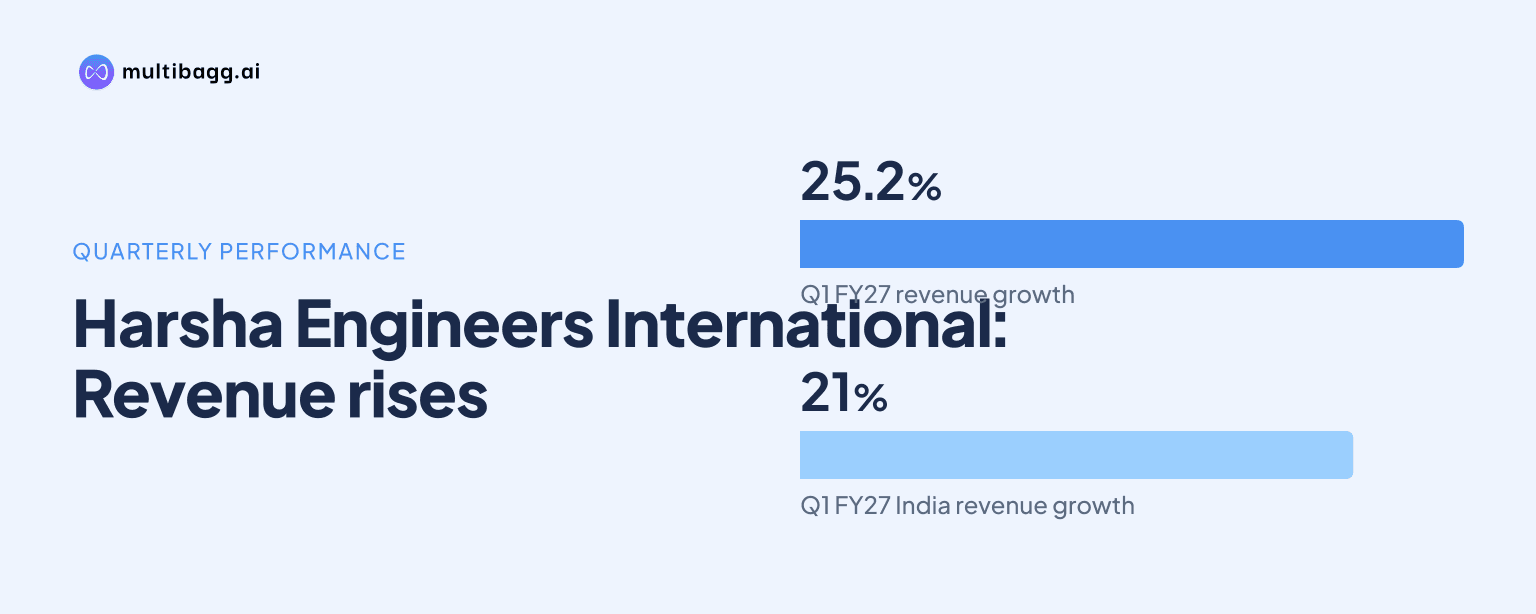
Harsha Engineers International Ltd reported consolidated revenue of ₹457.43 crore in Q1 FY27, a 25.2% year-on-year increase, supported by continued demand from Indian and European industrial customers despite temporary margin pressure. The company said higher raw-material costs, forex losses and indirect-material expenses affected profitability during the June 2026 quarter.
Know Harsha Engineers International inside out
Results, valuation, peers and who's buying, in one view.
What drove Harsha Engineers International's Q1 FY27 revenue growth?
Harsha Engineers International Ltd recorded consolidated revenue of ₹457.43 crore for the quarter ended June 30, 2026, compared with growth of 25.2% from the year-earlier period. The company attributed the increase to continued demand across its engineering operations, with India Engineering, comprising HEIL and Advantek, reporting 21% year-on-year growth.
The company manufactures precision bearing cages, an industrial component used in bearings across several applications. Its Indian engineering operations benefited from exports, particularly to Europe, according to management commentary cited in the available material. Domestic demand remained positive overall, although the company indicated that stamping demand linked to air-conditioning applications had softened.
Revenue was also 3.5% lower sequentially than the preceding quarter, based on the reported Q1 FY27 snapshot. This followed a seasonally stronger March quarter, while the company said its India Engineering business continued to grow 6% sequentially despite that seasonal base. The figures indicate that the year-on-year expansion remained the central operating development in the June quarter.
The Q1 presentation was submitted following the approval of unaudited financial results for the quarter ended June 30, 2026. Harsha Engineers International also released the audio recording of its investor conference call held on August 11, 2026 after the Q1 results approval.
Why did Harsha Engineers International's margins face pressure?
Harsha Engineers International said EBITDA and PAT margins in its India Engineering business were compressed by higher input and other operating costs during Q1 FY27. Raw-material costs increased by about 6% to 8% in the quarter, while the company also recorded a forex loss of around ₹4 crore on settlement of cash-flow hedges relating to previous quarters.
The company further cited higher indirect-material costs, including oil and packing material, of around ₹3 crore. These factors affected the cost base even as revenue expanded. Management said the raw-material price increase would be passed through in subsequent quarters, but the presentation did not provide a specific timing or quantify the expected margin recovery.
Q1 FY27 operating profit was reported at ₹67 crore, translating into an operating profit margin of 14.66%. Net profit stood at about ₹37.4 crore, down 1.5% year on year, according to the reported quarterly snapshot. This difference between revenue growth and profit movement illustrates the impact of the cost and forex items on quarterly earnings.
Got a follow-up? Ask IRIS
How does Q1 FY27 compare with the recent quarterly base?
Harsha Engineers International's Q1 FY27 revenue performance followed a mixed recent earnings base. For the September 2025 quarter, or Q2 FY26, the company had reported revenue of ₹378 crore, operating profit of ₹54 crore, an operating profit margin of 14.29%, and net profit of ₹36 crore.
The June 2026 quarter therefore provides a higher revenue base ahead of the September 2026 results. However, direct quarter-to-quarter comparisons should account for the company’s reference to seasonal strength in the preceding March quarter. The available information does not provide Q2 FY27 financial figures, so no conclusion can be drawn on whether the June-quarter growth rate continued into the September period.
Harsha Engineers International has stated that strong Indian and European industrial demand supported its latest reported quarter. The European export exposure is relevant because it contributes to India Engineering growth, while forex movements can also affect reported costs and hedging settlements. The company’s disclosures identify both demand conditions and input costs as key factors affecting the segment’s financial performance.
What should investors track in Harsha Engineers International's Q2 FY27 results?
Investors will track whether Harsha Engineers International sustains revenue growth and whether the stated raw-material pass-through reduces the margin pressure seen in Q1 FY27. The board was scheduled to meet on November 3, 2026 to consider unaudited Q2 FY27 and half-year results for the period ended September 30, 2026, with an earnings call intimated for November 4.
The main reported operating markers from Q1 were ₹457.43 crore of revenue, ₹67 crore of operating profit and an operating margin of 14.66%. Any updated management remarks on raw-material prices, indirect-material expenses, export demand and forex effects will help investors assess the factors behind changes in profitability.
The company has not disclosed Q2 FY27 revenue, profit or margin figures in the material provided. As a result, expectations for the September quarter should remain tied to the official financial results and accompanying presentation rather than unverified estimates.
How could the quarter affect Harsha Engineers International's operations and investors?
The Q1 figures show that demand supported volume and revenue growth, but rising costs limited the conversion of that growth into profit. For industrial manufacturers such as Harsha Engineers International, the ability to pass through raw-material cost increases is important because input inflation can reduce margins before revised customer pricing takes effect.
For investors, the contrast between 25.2% revenue growth and the 1.5% decline in net profit places emphasis on operating-margin trends. The company’s stated plan to pass through raw-material increases is a disclosed operational response, although the available presentation does not specify the financial impact that may follow.
The company’s export-led India Engineering growth also makes conditions in European industrial markets relevant to its order flow. At the same time, management noted that domestic demand was broadly positive, despite weaker orders in stamping for air-conditioning applications. These disclosures point to varied demand conditions across end markets rather than a uniform trend.
Conclusion
Harsha Engineers International delivered 25.2% year-on-year consolidated revenue growth to ₹457.43 crore in Q1 FY27, led by continued industrial demand and 21% growth in its India Engineering business. Profitability was constrained by a 6% to 8% increase in raw-material costs, a ₹4 crore forex loss and around ₹3 crore of higher indirect-material expenses.
The next key disclosure is the Q2 FY27 and half-year financial result considered by the board on November 3, 2026, followed by the scheduled November 4 earnings call. Investors should watch for reported revenue and margin trends, the status of raw-material cost pass-through, and management commentary on Indian and European demand.