










Highway Infrastructure Limited H1 Profit Falls to ₹10.8 Crore
Key highlights
- Highway Infrastructure Limited reported H1 FY27 revenue of ₹520.7 crore.
- H1 FY27 net profit was ₹10.8 crore, down from ₹16.9 crore in H1 FY26.
- Q1 FY27 revenue from operations rose 170.9% year-on-year to ₹303.28 crore.
- Highway Infrastructure Limited reported an order book of about ₹778 crore as of 30 June 2026.
powered by IRIS
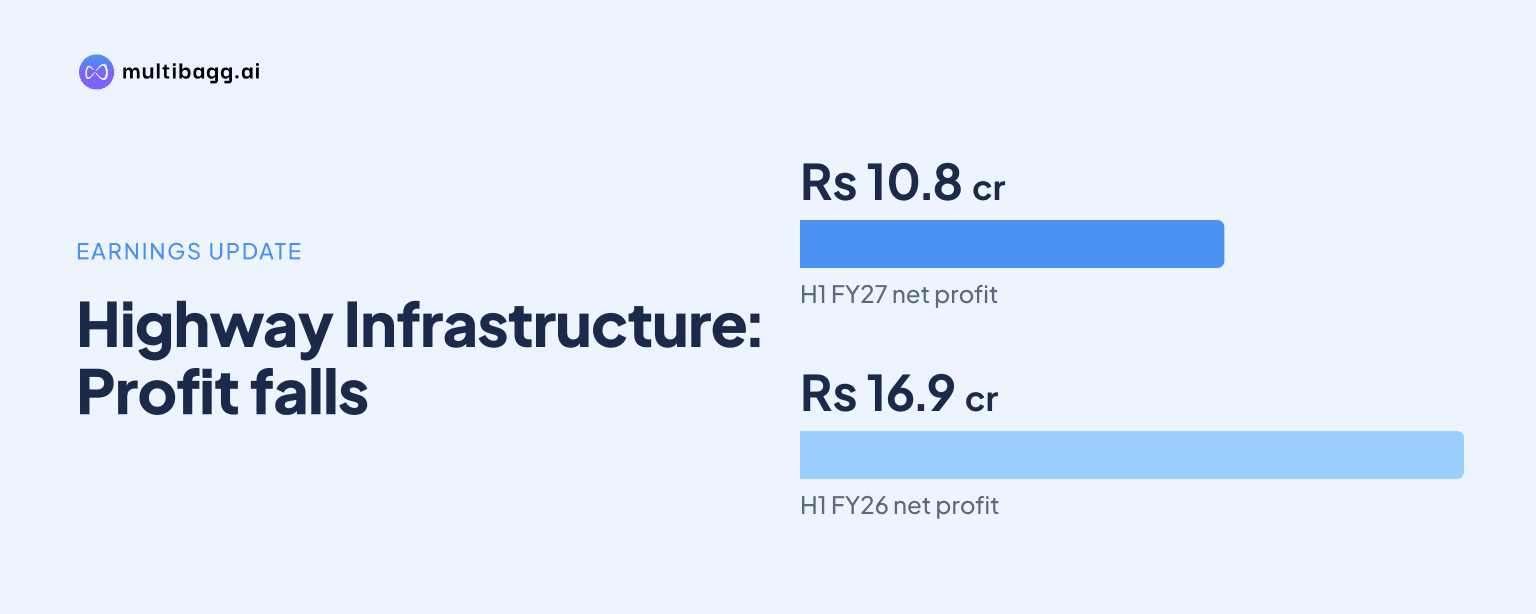
Highway Infrastructure Limited reported consolidated revenue of ₹520.7 crore for H1 FY27, while net profit declined to ₹10.8 crore from ₹16.9 crore in H1 FY26. The result shows that revenue growth and expanded toll operations did not translate into comparable profit growth during the first half of the financial year.
Know Highway Infrastructure inside out
Results, valuation, peers and who's buying, in one view.
What did Highway Infrastructure Limited report for H1 FY27?
Highway Infrastructure Limited reported unaudited consolidated financial results for the quarter ended September 2026, taking its H1 FY27 revenue to ₹520.7 crore and profit after tax to ₹10.8 crore. The board approved the results on 14 November 2026. Compared with H1 FY26 profit of ₹16.9 crore, the H1 FY27 profit was lower by about 36.1%.
The reported H1 performance follows a sharply uneven first quarter. In Q1 FY27, the company recorded revenue from operations of ₹303.28 crore and total income of ₹304.32 crore, compared with revenue of ₹111.95 crore in Q1 FY26. Yet Q1 profit after tax was only ₹1.06 crore, against ₹7.25 crore a year earlier, reflecting weak operating profitability despite higher revenue.
The company operates in toll collection, EPC infrastructure and real estate. Toll operations were its principal revenue source in Q1 FY27, contributing 90.3% of revenue, while work contracts and machinery hire accounted for 9.2% and real estate contributed 0.5%.
Why did profit remain under pressure despite higher revenue?
Profit remained under pressure because the growth in revenue was accompanied by a sharp reduction in operating margin in Q1 FY27. EBITDA for the June 2026 quarter stood at ₹4.8 crore, compared with ₹12 crore in Q1 FY26, and the EBITDA margin declined to about 1.6% from 10.7%.
The company attributed the Q1 profitability pressure to temporary operational factors. These included lower traffic at the Moti Naroli toll project amid geopolitical disruptions, bidding restrictions, and the surrender of an unfavourable toll project. These factors limited earnings even as revenue rose strongly from the previous year's low base.
The available H1 result data indicate that profitability improved from the Q1 level during the subsequent quarter, as the first-half profit of ₹10.8 crore exceeded the ₹1.06 crore reported in Q1. However, the H1 profit remained below the ₹16.9 crore reported for the corresponding period of FY26.
How important are toll contracts to Highway Infrastructure Limited?
Toll collection is central to Highway Infrastructure Limited's current operating profile, accounting for 90.3% of Q1 FY27 revenue. The company has targeted FY27 turnover of about ₹850 crore, including ₹700 crore expected from toll operations and the balance from EPC activity.
The company has also won two National Highways Authority of India contracts to collect user fees at toll plazas, with a combined value of about ₹431.86 crore. One of these contracts is the Palayam project. The stated value of the two orders is significant relative to the company's FY26 consolidated revenue of ₹608 crore.
As of 30 June 2026, Highway Infrastructure Limited reported a consolidated order book of about ₹778 crore. It also secured toll contracts in Tamil Nadu valued at about ₹108.7 crore during Q1 FY27, supporting its move into South India. These order wins add contracted work, but their effect on revenue and margins will depend on execution and operating conditions.
Got a follow-up? Ask IRIS
What should investors take from the first-half results?
Investors have to weigh strong revenue expansion against weaker profitability and thin operating margins. Q1 revenue was approximately 30% of a previously referenced ₹1,000 crore full-year target, while the company has separately cited an FY27 turnover target of ₹850 crore. The two target references show that investors should focus on the company's current guidance in future disclosures.
The H1 profit decline is notable because the company had reported a stronger first half in FY26. In H1 FY26, revenue was reported at ₹227.8 crore, EBITDA at ₹25.8 crore and net profit at ₹16.9 crore. The FY27 comparison therefore highlights a shift from a lower-revenue, higher-margin period to a much larger revenue base with reduced profitability.
The auditor's limited review report on the current results was unqualified. The company also disclosed that subsidiary results with H1 revenue of ₹3.3 crore and profit after tax of ₹0.05 crore were management-certified and had not been reviewed by that subsidiary's auditors. This disclosure is relevant to readers assessing the composition and review status of the consolidated results.
How did the results affect Highway Infrastructure Limited's market context?
The results were released on Saturday, 14 November 2026, when the Indian equity market was closed. Any immediate share-price response would therefore occur on the next trading day, 16 November 2026. The supplied information does not state the subsequent market movement.
For the infrastructure sector, the results underline the difference between winning toll contracts and earning stable margins from them. Toll projects can increase revenue rapidly when operations begin, but traffic patterns, project terms and disruptions can affect profitability. Highway Infrastructure Limited's Q1 margin decline provides a clear example of this operating sensitivity.
The H1 figures also place focus on cash generation and financing discipline across infrastructure businesses. In a separate financial disclosure included in the supplied material, finance costs rose to ₹1.38 crore and operating cash flow was negative ₹2.05 crore, though that disclosure does not provide a basis to attribute those figures to Highway Infrastructure Limited. It should therefore not be treated as part of Highway Infrastructure Limited's reported H1 performance.
Conclusion
Highway Infrastructure Limited closed H1 FY27 with ₹520.7 crore in consolidated revenue but ₹10.8 crore in net profit, down from ₹16.9 crore a year earlier. The company has expanded revenue through toll operations and new contract wins, but the first-half result shows that operating disruptions and a lower EBITDA margin materially affected earnings.
The next points to watch are the company's progress toward its stated FY27 turnover target of about ₹850 crore, the execution of its ₹778 crore order book, and whether toll traffic and margins improve after the Q1 disruptions. Investors will also look for updated guidance and operational details in subsequent quarterly disclosures.