










Hitech Corporation Delisting: Shareholding and ₹426 Exit
Key highlights
- Hitech Corporation’s promoter and promoter group held 74.43%, or 1,27,84,480 shares, before the delisting offer.
- The delisting offer covered 43,91,220 shares, representing 25.57% of paid-up equity capital.
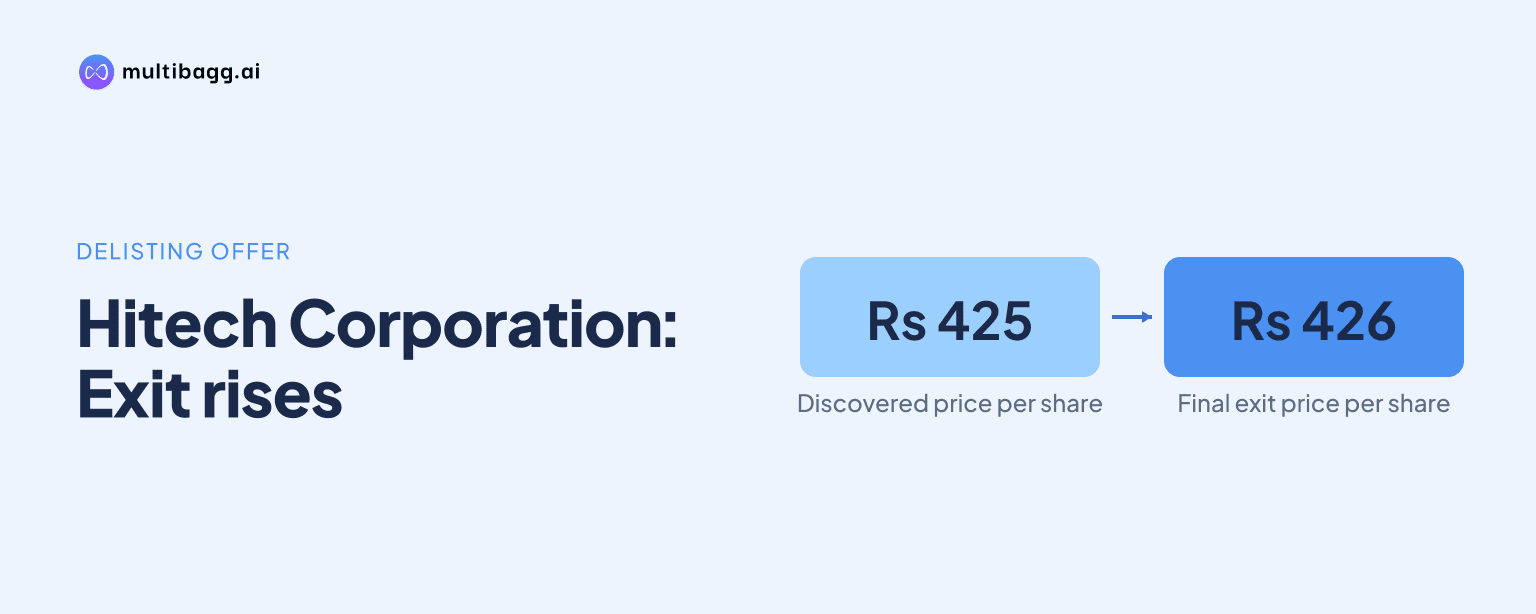
- The reverse book-building process produced a discovered price of ₹425 per share, while the final exit price was fixed at ₹426.
- Reported promoter and acquirer ownership reached 91.96%, exceeding the 90% threshold for delisting success.
powered by IRIS
Hitech Corporation Limited’s shareholding structure became central to its voluntary delisting process from BSE and NSE. The promoter group held 74.43% of the company before the offer, while the delisting proposal sought to acquire shares held outside the promoter group. Geetanjali Trading and Investments Private Limited, a promoter group member, acted as the acquirer. The offer was made under the SEBI Delisting Regulations, 2021. The process gave eligible public shareholders an exit opportunity through reverse book building. Reports subsequently stated that the offer was successful after promoter and acquirer holding crossed the required 90% threshold.
Know Hitech Corporation inside out
Results, valuation, peers and who's buying, in one view.
Promoter Holding Before the Delisting Offer
The Letter of Offer stated that the promoter and promoter group held 1,27,84,480 equity shares, or 74.43% of Hitech Corporation’s issued and paid-up equity capital. This level had remained unchanged across the quarterly data shown from March 2024 through June 2026. Geetanjali Trading and Investments held 1,18,69,295 shares as of the Letter of Offer date. The promoter group’s stable holding was an important starting point for the proposed delisting. It meant that the acquirer needed to obtain a substantial part of the non-promoter shareholding to meet the delisting conditions.
Public Shareholding Figures Need Context
The supplied September 2026 shareholding breakdown lists promoters at 74.43%, FIIs at 0.00%, DIIs at 0.04%, public shareholders at 17.27%, mutual funds at 0.00%, and others at 8.26%. Separately, the Letter of Offer describes public shareholders as owning 43,91,220 shares, or 25.57% of total equity. These figures are presented in different reported shareholding classifications and offer-related disclosures. The Letter of Offer identifies the 25.57% stake as the shares targeted under the delisting offer. Investors should therefore distinguish between a category-based shareholding snapshot and the public shareholding figure used in the offer document.
Terms of the Voluntary Delisting Proposal
The offer covered 43,91,220 equity shares of face value ₹10 each, representing 25.57% of the total paid-up equity share capital. Hitech Corporation’s paid-up capital was stated at ₹17,17,57,000, divided into 1,71,75,700 equity shares. Geetanjali Trading and Investments proposed to acquire all equity shares held by public shareholders. The objective was to voluntarily delist Hitech Corporation’s equity shares from BSE and NSE. The proposal followed an Initial Public Announcement dated May 25, 2026. Kreo Capital Private Limited acted as manager to the delisting offer.
Indicative Price and Reverse Book Building
The offer carried a floor price of ₹252 per share and an indicative price of ₹353 per share. The indicated price was reported as being above Hitech Corporation’s lifetime high of ₹351.35. Under the reverse book-building mechanism, eligible public shareholders could tender shares and indicate the price at which they were willing to sell. The bidding period was stated to run from October 7 to October 13, 2026. The discovered price from the process was reported at ₹425 per share. The acquirer later fixed the final exit price at ₹426 per share, which was ₹1 above the discovered price.
Delisting Offer at a Glance
Got a follow-up? Ask IRIS
Reported Success of the Offer
The delisting offer was reported as successful after the acquirer and promoter holding rose to 91.96%. Another supplied update referred to a 92.67% post-offer holding, subject to the acquirer accepting the discovered price. The reported final exit price of ₹426 followed the reverse book-building outcome. The 90% holding threshold is a key condition in a voluntary delisting process under the applicable regulations. Crossing that level is material because it determines whether the offer can proceed as a successful delisting offer. The reports described Hitech Corporation as deemed successfully delisted following the increase in promoter and acquirer ownership.
Why the Shareholding Pattern Matters
Shareholding data shows the extent of promoter control and the ownership available for public trading. Before the offer, the promoter group’s 74.43% holding left 25.57% with public shareholders according to the Letter of Offer. The proposed acquisition of this stake was therefore necessary for the promoter group to seek delisting. The absence of reported FII and mutual fund holdings in the supplied September 2026 breakdown also indicates that institutional ownership was limited in that snapshot. Domestic institutional holdings were listed at 0.04%. For shareholders, the relevant issue was the tender process and the final exit price rather than regular exchange trading after delisting.
Regulatory Framework for the Offer
The offer was made in accordance with the SEBI Delisting Regulations, 2021, as amended. These regulations govern voluntary delisting proposals by listed companies and their promoters. The Independent Directors Committee of Hitech Corporation recommended the voluntary delisting offer, according to the supplied information. The Letter of Offer set out the acquirer, promoter group holding, share capital, offer size and exit mechanism. Such disclosures allow shareholders to assess the terms of an offer before tendering shares. The proposal covered delisting from both BSE and NSE, where Hitech Corporation’s equity shares were listed.
What Shareholders Should Track
The reported ₹426 final exit price is the principal financial outcome of the delisting process. Shareholders should refer to the final offer documents and exchange disclosures for the applicable settlement and tender-related details. The pre-offer shareholding structure establishes how the promoter group moved from a 74.43% stake toward the reported post-offer level. The final ownership level is also relevant to the completion of the voluntary delisting process. Hitech Corporation’s case illustrates how a promoter-led delisting depends on the number of shares tendered by public holders and the final price accepted by the acquirer.
Conclusion
Hitech Corporation’s voluntary delisting proposal was built on a promoter group stake of 74.43% and an offer for up to 25.57% of its equity held by public shareholders. The reverse book-building process resulted in a reported discovered price of ₹425 per share, followed by a ₹426 final exit price. Reports of promoter and acquirer holding reaching 91.96% placed the offer above the required 90% threshold. The remaining relevant updates are the formal exchange and company disclosures concerning completion of the delisting process and settlement for eligible shareholders.