










HLE Glascoat Limited Q2 EBITDA Rises 72.3% QoQ to ₹39 Crore
Key highlights
- HLE Glascoat reported Q2 FY27 EBITDA of ₹39 crore, up 72.3% quarter on quarter.
- Q2 FY27 revenue from operations was ₹346.7 crore, up 15.3% sequentially and down 1.2% year on year.
- H1 FY27 EBITDA was ₹61.6 crore, down 23% year on year, with a 9.5% EBITDA margin.
- Q2 glass-lined equipment revenue rose 24.2% year on year to ₹195.4 crore.
powered by IRIS
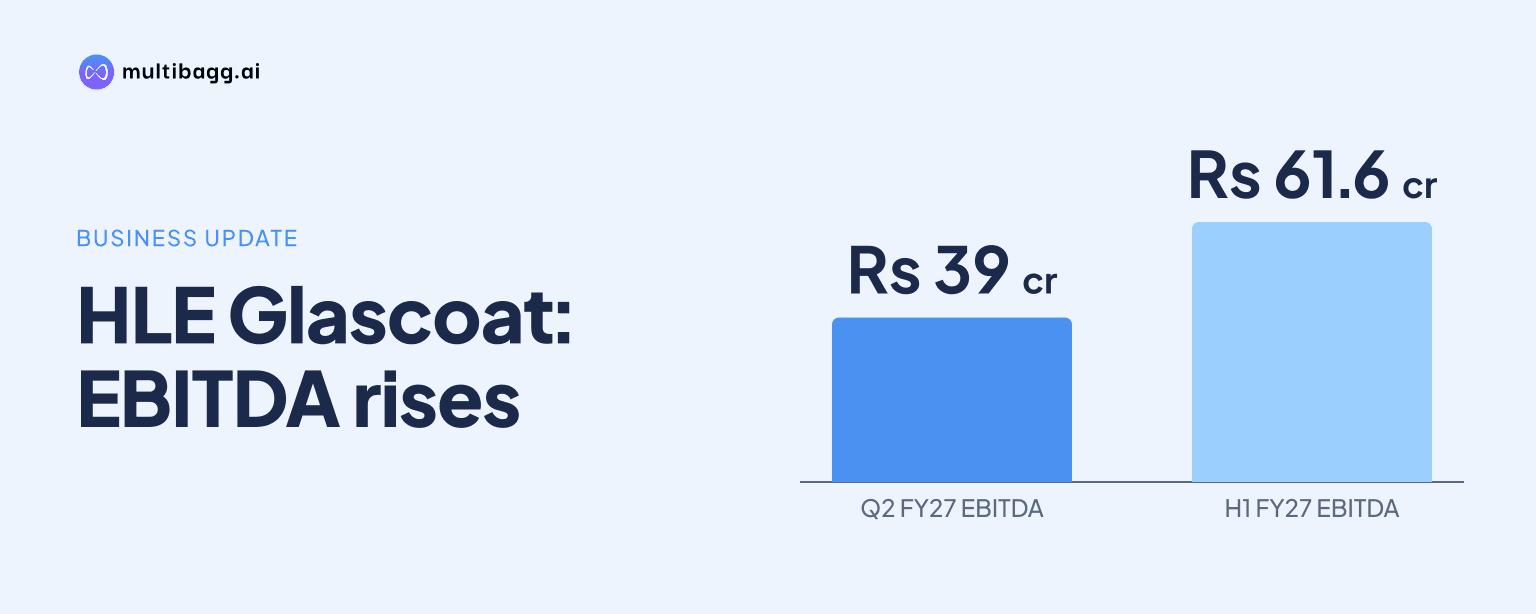
HLE Glascoat Limited reported Q2 FY27 EBITDA of ₹39 crore, up 72.3% quarter on quarter, while revenue from operations rose 15.3% sequentially to about ₹346.7 crore. The improvement lifted quarterly EBITDA margin to 11.2%, although revenue from operations was 1.2% lower than the comparable quarter a year earlier.
Know HLE Glascoat inside out
Results, valuation, peers and who's buying, in one view.
What did HLE Glascoat report for Q2 FY27?
HLE Glascoat reported revenue from operations of about ₹346.7 crore in Q2 FY27, compared with ₹350.8 crore in Q2 FY26. Total revenue for the quarter was ₹349.0 crore, down 1.1% year on year, according to the investor presentation cited in the provided material.
Sequentially, revenue from operations increased 15.3% from Q1 FY27. EBITDA was ₹39 crore, representing a 72.3% quarter-on-quarter increase, and the EBITDA margin was 11.2%. The sequential margin and earnings improvement are the central financial development in the quarter, particularly after a weaker first-half comparison with the previous year.
For H1 FY27, revenue from operations stood at ₹647.4 crore, against ₹634.7 crore in H1 FY26, an increase of 2%. However, H1 EBITDA declined to ₹61.6 crore from ₹80 crore a year earlier. The first-half EBITDA margin was 9.5%, showing that the stronger second quarter did not fully offset the lower profitability recorded earlier in the year.
Which businesses supported the quarterly performance?
The glass-lined equipment business remained a major contributor to the quarter. Its Q2 FY27 revenue was ₹195.4 crore, compared with ₹157.3 crore in Q2 FY26, an increase of 24.2% year on year. H1 FY27 segment revenue in this business increased 35.4%, based on the figures provided.
Filtration, drying and other equipment generated ₹102 crore of Q2 FY27 revenue, compared with ₹96.8 crore in Q1 FY27. This represents 5.4% sequential growth. The two business lines therefore showed different growth patterns: glass-lined equipment recorded strong year-on-year growth, while filtration and drying equipment improved from the preceding quarter.
Management also highlighted the contribution of Thaletec products to the India glass-lined business. Thaletec products accounted for about 22% of the overall glass-lined product business in India during the quarter. This mix is relevant because management linked Thaletec offerings with better realisations in the domestic market.
What did management say about demand and India operations?
Management said demand in India was optimistic, with particularly high demand from the active pharmaceutical ingredient and specialty chemical sectors. Executive Director Harsh Patel said demand from the United States was also high, while Europe was slightly subdued.
On the India glass-lined business, management said H1 FY27 revenue was about ₹110 crore and EBITDA margins were in the high single digits. Harsh Patel said this was better than the prior year and that H2 performance was expected to improve based on order-book visibility. Management indicated an FY27 revenue expectation of ₹260 crore to ₹280 crore for this business.
Management further said the India glass-lined business could deliver EBITDA margins of 16% to 18% at around ₹300 crore of revenue. The stated factors behind this potential margin level were improved realisations from the Thaletec range and cost discipline. This is a management view rather than a reported FY27 outcome.
Got a follow-up? Ask IRIS
How are Thaletec and European businesses positioned?
Thaletec Germany reported H1 FY27 revenue of about ₹192 crore, with an EBITDA margin slightly above 11%, according to management. For the full prior year, Thaletec Germany had revenue of about ₹343 crore and EBITDA margin slightly below 11%. Management described the H1 run rate as implying a pro-rata increase of roughly 12% to 13%.
HLE Glascoat said its European businesses benefit from the established manufacturing base in India. Management stated that customer resistance to equipment made outside Europe is easing as end users seek more efficient capital expenditure. It expects sourcing of non-critical components from India to increase, while adding that critical applications are likely to continue requiring European-made equipment in the medium term.
The company also said it remained on track for its ₹2,000 crore revenue target. Management attributed that objective to existing products, new products and the new India plant for Omeras products. The provided material does not state a target year for the ₹2,000 crore revenue objective.
What does the quarter mean for investors and the industry?
The Q2 results show a substantial sequential recovery in EBITDA, with profit rising faster than revenue and margin reaching 11.2%. But the first-half figures provide necessary context: H1 EBITDA was still 23% below the prior-year level despite 2% growth in revenue from operations. Investors will therefore be able to assess the quarter both as an improvement from Q1 and against the slower first-half earnings performance.
The disclosed demand commentary points to stronger conditions in Indian API and specialty chemical markets and in the United States, while Europe remains comparatively softer. For HLE Glascoat, this geographic mix matters because it operates across domestic and European equipment businesses and is seeking greater use of its India manufacturing base for appropriate components.
No share-price movement, order-book value or formal financial guidance was included in the supplied material. The company made the audio recording of its November 3, 2026 earnings call available on its website, following the call covering the quarter and half year ended September 30, 2026.
Conclusion
HLE Glascoat's Q2 FY27 performance was marked by ₹39 crore of EBITDA and a 72.3% sequential increase in operating profit, supported by higher quarterly revenue and growth in glass-lined equipment. The quarter improved on Q1, but H1 EBITDA of ₹61.6 crore remained below the ₹80 crore reported in H1 FY26.
The next points to watch are the India glass-lined business's progress toward management's ₹260 crore to ₹280 crore FY27 revenue expectation, the stated H2 improvement supported by order-book visibility, and execution toward the company's ₹2,000 crore revenue target through existing products, new products and the Omeras plant.