










Inox Green maps 12.5-GWp O&M growth through contracts and deals
Key highlights
- Inox Green reported an approximately 12.5-GWp O&M portfolio in September 2026, including about 10.4 GW of wind assets.
- The 4.5-GW Wind World India O&M business generated Rs 580 crore of revenue in FY26.
- Wind World India financials are due for line-by-line consolidation from Q3 FY27.
- Inox Green reported Q2 FY27 revenue of Rs 113 crore, EBITDA of Rs 62.5 crore and machine availability of 96.2%.
powered by IRIS
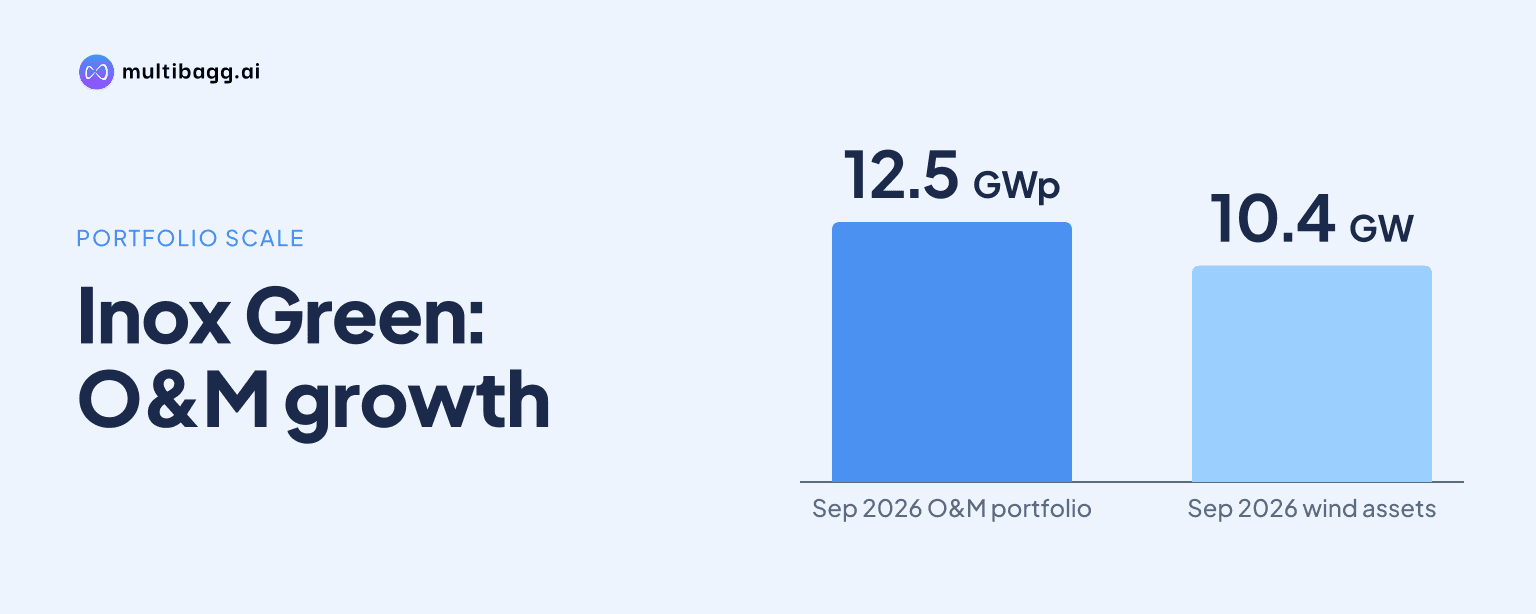
Inox Green Energy Services Limited is building its renewable operations and maintenance, or O&M, business around a 12.5-gigawatt-peak portfolio as of September 2026, supported by contracts lasting five to 20 years and the acquired 4.5-gigawatt Wind World India O&M business, which generated Rs 580 crore of revenue in FY26.
Know Inox Green Energy Services inside out
Results, valuation, peers and who's buying, in one view.
How large is Inox Green's O&M portfolio?
Inox Green manages an approximately 12.5-GWp renewable O&M portfolio, comprising about 10.4 GW of wind assets and 2.1 GWp of solar assets. The portfolio covers wind turbine generators, or WTGs, solar projects, hybrid projects and common infrastructure for renewable facilities across states including Gujarat, Maharashtra, Karnataka, Rajasthan, Tamil Nadu and Andhra Pradesh.
The portfolio grew from 0.09 GWp in 2013 to 12.50 GWp in 2025, and remained at 12.50 GWp in September 2026. The presentation says the current number includes the Wind World India portfolio and investment to acquire another approximately 2 GW of wind O&M assets. It also says the total was affected by non-renewal of certain solar O&M contracts that did not meet Inox Green's margin criteria.
Inox Green reported pan-India average machine availability of 96.2% in Q2 FY27. The company attributes its service approach to 24x7 centralised asset monitoring, performance analysis, supervisory control and data acquisition, or SCADA, analysis, and an emphasis on preventive rather than reactive maintenance.
How do long-term contracts support Inox Green's O&M model?
Inox Green's recurring-revenue model is based on long-term O&M contracts for wind farms, WTGs, solar plants and common renewable-project infrastructure. The company says contracts generally run for five to 20 years, while a separate key-metrics disclosure states that contract tenors can extend up to 25 years and that the portfolio has multi-year residual duration.
The company offers annual maintenance contracts, annual O&M contracts, semi-comprehensive O&M contracts and comprehensive O&M contracts. Its asset-light positioning follows the completed demerger of the power-evacuation business, with its stated focus now on long-term service contracts and associated cash flows rather than the evacuated-power infrastructure business.
In Q2 FY27, Inox Green reported revenue of Rs 113 crore and earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 62.5 crore. The presentation does not split these figures between wind, solar, common-infrastructure O&M or value-added services, so the contribution from each service category is not disclosed.
Inox Green is also upgrading to SAP HANA and developing a mobile-based O&M management tool. These initiatives sit alongside centralised monitoring and performance analysis, although the presentation gives no completion date, implementation cost or quantified financial benefit for the digital programme.
What does the Wind World India acquisition add to Inox Green?
The Wind World India transaction adds a 4.5-GW wind O&M business that generated Rs 580 crore of revenue in FY26 and has contracted annual price escalation of approximately 5%. Inox Green completed payment for the transfer through its subsidiary Vibhav Energy Private Limited under a Business Transfer Agreement executed with Wind World India.
The transfer was completed through a National Company Law Tribunal process, and Inox Green says line-by-line financial consolidation will begin in Q3 FY27. The acquired assets are located across Karnataka, Maharashtra, Tamil Nadu, Rajasthan, Gujarat, Madhya Pradesh and Andhra Pradesh, increasing the company's wind-service coverage across established wind states.
The acquired portfolio serves customers including Tata Group, ReNew, Greenko Group, Araapava Energy and Hindustan Zinc. Management says integration initiatives are under way and identifies enhanced service offerings, price optimisation, cost optimisation and operational efficiencies as opportunities, but it does not disclose the transaction price, expected savings or a profitability target.
Got a follow-up? Ask IRIS
How does Inox Green plan to grow through group-linked contracts?
Inox Green plans organic expansion through new long-term O&M agreements with customers purchasing Inox Wind WTGs, contracts from the Inox Clean platform, resets of existing contracts, turbine-overhaul packages and value-added services. The overhaul packages are intended to extend turbine life and improve output, while the stated value-added offerings include refurbishment, booster sales and carbon-credit trading.
The presentation provides two Inox Wind order-book measures. Its key-metrics page reports a net order book of approximately 3.6 GW, while its organic-growth page cites an approximately 4.4-GW order book as providing visibility for potential O&M contracts. Inox Green does not reconcile the two figures, give dates for either measure, or state how much capacity will convert into signed O&M contracts.
Inox Clean is targeting 14 GW of hybrid renewable capacity, including wind, solar and battery energy storage systems, by FY29. That target belongs to the group platform rather than Inox Green's contracted portfolio, but the presentation identifies Inox Clean capacity additions as a potential source of future O&M work for Inox Green.
The company also identifies revision or reset of existing O&M contracts as an organic lever. The September 2026 portfolio note shows why renewal terms matter: solar contracts that did not meet its margin criteria were not renewed, offsetting part of the expansion from wind-related additions.
Where could Inox Green find further acquisitions or contract takeovers?
Inox Green identifies expiring customer contracts and captive O&M portfolios held by large independent power producers and developers as its main inorganic opportunities. Management says it sees potential to enter contracts where incumbent agreements have expired or are close to expiry, and to take over portfolios that developers currently manage internally.
The completed Wind World India transfer is the only specified transaction in the presentation, at 4.5 GW. Inox Green does not name further targets, disclose an acquisition pipeline, quantify available captive portfolios or provide a timetable for another transaction.
The current 12.5-GWp portfolio combines approximately 10.4 GW of wind with 2.1 GWp of solar, while the disclosed 4.5-GW Wind World India acquisition is entirely wind O&M. The disclosed growth activity is therefore weighted toward wind, even as Inox Green offers O&M for solar and hybrid facilities as well.
Conclusion
Inox Green's expansion plan combines a 12.5-GWp O&M base, contracts lasting five to 20 years, group-linked opportunities and acquisition-led portfolio additions. The most defined near-term contributor is the 4.5-GW Wind World India business, whose Rs 580 crore FY26 revenue carries approximately 5% contracted annual price escalation, while Inox Green reported 96.2% machine availability in Q2 FY27.
The next disclosed event is line-by-line consolidation of the Wind World India business from Q3 FY27 and progress on its integration initiatives. Further developments to watch are whether Inox Green converts Inox Wind's disclosed 3.6-GW or 4.4-GW order-book references into O&M contracts, and whether capacity additions linked to Inox Clean's 14-GW FY29 target generate service agreements.