










HGS India cash flow halves as inventory absorbs Rs 7.37 crore
Key highlights
- HGS India’s FY26 net operating cash flow fell 56% to Rs 6.14 crore from Rs 14.09 crore in FY25.
- Inventory absorbed Rs 7.37 crore of cash in FY26, reversing a Rs 4.42 crore cash release in FY25.
- HGS India’s FY26 profit for the year rose to Rs 11.64 crore from Rs 10.51 crore despite revenue declining to Rs 45.16 crore.
- Inventory increased further to Rs 45.78 crore by April 30, 2026, while one-month operating cash inflow was Rs 3.28 crore.
powered by IRIS
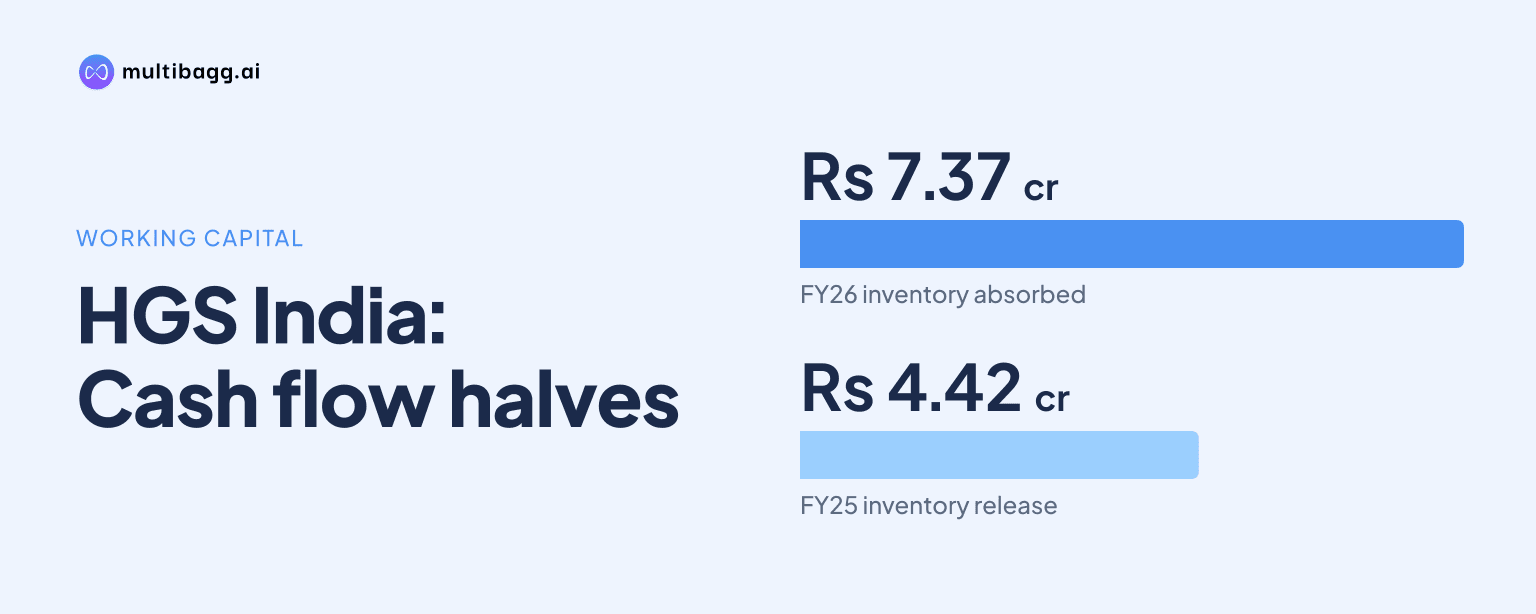
HGS India’s net cash flow from operating activities fell 56% to Rs 6.14 crore in FY26 from Rs 14.09 crore in FY25, despite profit for the year rising to Rs 11.64 crore from Rs 10.51 crore. A Rs 7.37 crore inventory increase was the largest working-capital cash outflow.
Why did HGS India cash flow halve in FY26?
HGS India cash flow halved because working-capital changes and higher cash-tax payments outweighed an increase in operating profit before working-capital changes. Net cash from operating activities declined by Rs 7.95 crore, from Rs 14.09 crore in FY25 to Rs 6.14 crore in FY26. The restated consolidated cash-flow statement uses the indirect method, which begins with profit before tax and adjusts it for non-cash items, working-capital movements and income taxes paid.
Profit before tax increased to Rs 15.42 crore in FY26 from Rs 13.82 crore in FY25. After adjustments including depreciation and amortisation of Rs 1.47 crore, foreign-currency translation effects of Rs 0.15 crore and other stated items, operating profit before working-capital changes increased to Rs 17.07 crore from Rs 13.95 crore. Working capital is the balance of short-term operating assets and liabilities, and its movements determine how much accounting profit becomes cash.
The profit and cash-flow trends also differed from the revenue trend. Revenue from operations declined to Rs 45.16 crore in FY26 from Rs 49.08 crore in FY25, while total income declined to Rs 48.91 crore from Rs 53.45 crore. Total expenses fell to Rs 33.50 crore from Rs 39.63 crore, allowing profit for the year to increase by Rs 1.13 crore even as operating cash flow declined.
How much cash did inventory absorb at HGS India?
HGS India’s inventory absorbed Rs 7.37 crore of cash in FY26, reversing a Rs 4.42 crore cash release in FY25. The FY26 inventory outflow was larger than the company’s Rs 6.14 crore net operating cash flow for the year. Under the indirect cash-flow method, an inventory increase is a use of cash because funds are committed to goods before they are sold or converted into customer receipts.
Consolidated inventory stood at Rs 45.33 crore at March 31, 2026, compared with Rs 37.96 crore at March 31, 2025. The Rs 7.37 crore increase in the balance-sheet inventory was recorded as a Rs 7.37 crore use of cash in FY26. Inventory therefore rose by about 19% while revenue from operations declined by about 8% over the same annual comparison; the financial statements do not disclose the operational reason for the increase.
The inventory cash-flow movement changed by Rs 11.79 crore between FY25 and FY26, shifting from a source of operating cash to a use of it. A recovery in cash conversion would require inventory to be sold, reduced or otherwise converted into cash without comparable increases in receivables, advances or other current assets. The supplied statements do not set out an inventory-reduction plan.
Got a follow-up? Ask IRIS
Which other working-capital movements affected HGS India cash flow?
HGS India’s other working-capital movements partly offset the inventory outflow but did not eliminate it. Trade receivables used Rs 0.97 crore in FY26, compared with a Rs 1.36 crore use in FY25. Other current liabilities supplied Rs 1.30 crore in FY26 after reducing cash by Rs 0.97 crore in FY25, helping limit the fall in cash generated from operations to Rs 9.71 crore from Rs 16.28 crore.
Trade payables reduced FY26 operating cash by Rs 0.18 crore, compared with a Rs 0.81 crore contribution in FY25. On the consolidated balance sheet, payables to parties other than micro and small enterprises were Rs 0.82 crore at March 31, 2026, versus Rs 1.13 crore a year earlier, while payables to micro and small enterprises rose to Rs 18.76 lakh from Rs 5.99 lakh. Other current liabilities increased to Rs 3.67 crore from Rs 2.42 crore.
Short-term loans and advances provided Rs 0.39 crore in FY26, after using Rs 0.52 crore in FY25. Other current assets used Rs 0.51 crore in FY26, compared with Rs 2 lakh in FY25. Alongside smaller changes in long-term loans and advances and other non-current assets, these movements reduced FY26 operating profit before working-capital changes of Rs 17.07 crore to cash generated from operations of Rs 9.71 crore.
Did income taxes further reduce HGS India operating cash flow?
HGS India paid Rs 3.57 crore in income taxes in FY26, reducing cash generated from operations of Rs 9.71 crore to net operating cash flow of Rs 6.14 crore. Income taxes paid were Rs 2.19 crore in FY25, when cash generated from operations was Rs 16.28 crore and net operating cash flow was Rs 14.09 crore. Cash-tax payments therefore increased by Rs 1.38 crore year on year.
Cash taxes are distinct from the tax expense reported in the profit and loss statement because the two measures reflect different timing and accounting items. HGS India recorded FY26 total tax expense of Rs 3.78 crore, comprising current tax of Rs 3.96 crore, a deferred-tax credit of Rs 14.60 lakh and a credit of Rs 3.81 lakh relating to earlier periods. The cash-flow statement records taxes paid, rather than tax expense, in arriving at operating cash flow.
What does the April 2026 update show about HGS India’s cash position?
HGS India reported Rs 3.28 crore of net operating cash inflow for the one-month period ended April 30, 2026, and cash and cash equivalents increased to Rs 6.34 crore from Rs 4.56 crore at March 31, 2026. Net investing cash outflow was Rs 1.51 crore and financing cash outflow was Rs 2,000, producing a Rs 1.78 crore increase in cash and cash equivalents during the period.
Inventory increased further to Rs 45.78 crore at April 30, 2026 from Rs 45.33 crore a month earlier. The cash-flow statement records a further Rs 45.82 lakh inventory use during April 2026, while trade receivables released Rs 2.10 crore and other current liabilities provided Rs 50.58 lakh. The one-month operating inflow was therefore supported by receivable collections despite the continued inventory increase.
Conclusion
HGS India’s FY26 results show that higher reported profit did not translate proportionately into operating cash. Profit for the year increased to Rs 11.64 crore, but the Rs 7.37 crore inventory build, other working-capital movements and Rs 3.57 crore of cash-tax payments reduced net operating cash flow to Rs 6.14 crore.
The next disclosed position is April 30, 2026, when inventory had increased by another Rs 45.82 lakh and operating cash inflow was Rs 3.28 crore. The unresolved issue in the supplied financial statements is whether the enlarged inventory balance will convert into cash without offsetting growth in receivables, advances or other current assets.