










Kanchi Karpooram Q1 Profit Rises 113% as Q2 Results Are Due
Key highlights
- Kanchi Karpooram reported Q1 FY27 net profit of ₹4.67 crore, up 113% year-on-year.
- Q1 FY27 revenue was reported at ₹42.77 crore, up 19% year-on-year.
- FY26 net profit fell 60.89% to ₹5.17 crore from ₹13.22 crore in FY25.
- Kanchi Karpooram’s board was scheduled to consider Q2 and half-year FY27 results on November 14, 2026.
powered by IRIS
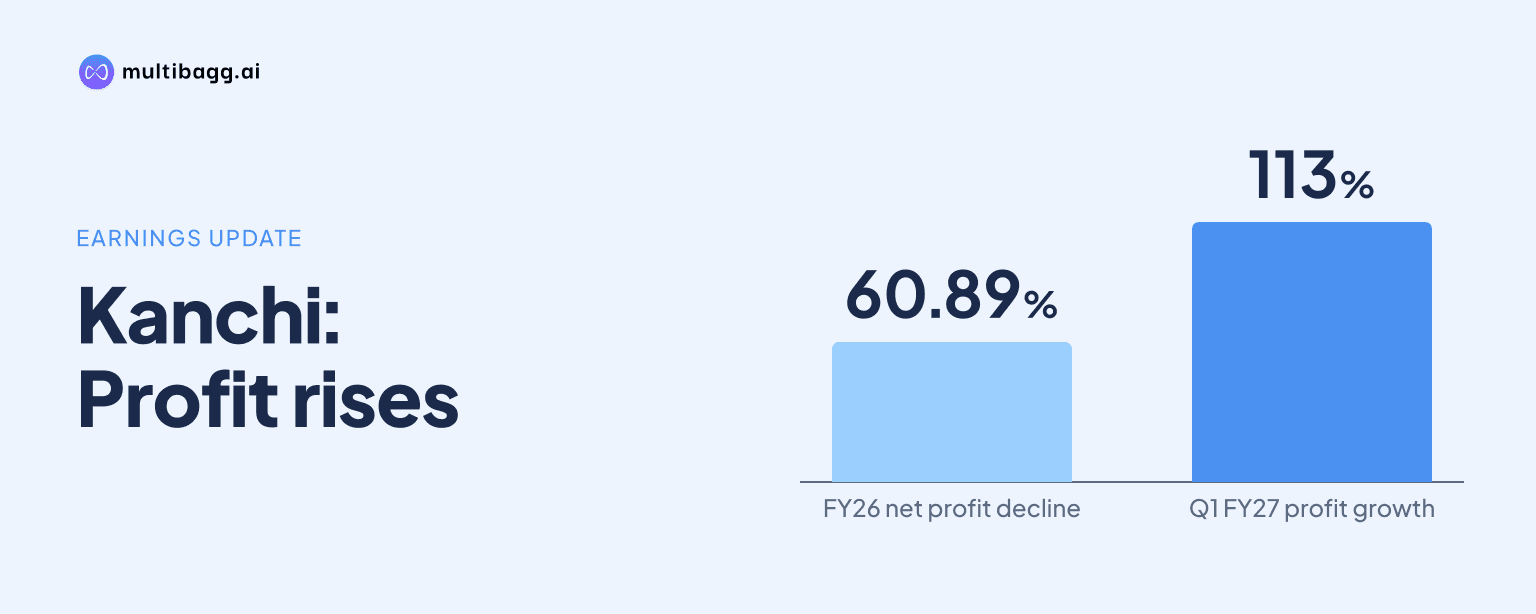
Kanchi Karpooram Limited reported a 113% year-on-year rise in net profit to ₹4.67 crore in the quarter ended June 2026, ahead of a board meeting scheduled for November 14, 2026 to consider its Q2 and first-half FY27 results. The June-quarter recovery followed a sharp decline in FY26 annual profitability.
Know Kanchi Karpooram inside out
Results, valuation, peers and who's buying, in one view.
What did Kanchi Karpooram report in Q1 FY27?
Kanchi Karpooram reported revenue of ₹42.77 crore, operating profit of ₹6.28 crore and net profit of ₹4.67 crore for the June 2026 quarter. Revenue rose 19% year-on-year according to the reported Q1 FY27 earnings summary, while net income increased 113% from the corresponding quarter of the previous year.
The company’s June-quarter operating margin was reported at 15.3%, while net profit margin was 11.2%. Earnings per share were reported at ₹10.75 in the Q1 FY27 earnings update. Another set of quarterly highlights cited EPS of ₹11.90 for June 2026, indicating a variation across the supplied financial-data sources.
On a sequential basis, the quarter showed a substantial improvement from March 2026. Revenue increased from ₹41.24 crore in March 2026 to ₹42.77 crore in June 2026, a 3.71% rise. Operating profit climbed from ₹1.09 crore to ₹6.28 crore, while net profit rose from ₹0.71 crore to ₹4.67 crore.
The supplied quarterly tables contain minor differences in reported sales figures for June 2026, including ₹41.16 crore and ₹41.74 crore in separate datasets. The company-level quarterly highlights and earnings summary, however, state revenue of ₹42.77 crore. Investors should refer to the exchange filing and approved financial statements for the final reported numbers.
Why are Kanchi Karpooram’s Q2 FY27 results important?
Kanchi Karpooram’s board was scheduled to meet on November 14, 2026 to approve the financial results for Q2 and the half year ended September 2026. The company had also stated that its trading window was closed from October 1 ahead of the results consideration.
The upcoming disclosure matters because the June-quarter profit recovery followed a difficult FY26. For the year ended March 2026, revenue declined 1.51% year-on-year to ₹153.09 crore from ₹155.44 crore in FY25. Operating profit fell 61.19% to ₹7.09 crore, and net profit dropped 60.89% to ₹5.17 crore.
The Q2 statement will show whether the stronger June-quarter operating performance continued into the September quarter. No Q2 FY27 revenue, profit, margin or EPS figures were included in the supplied information. Therefore, any assessment of the half-year trend must await the company’s approved results announcement.
Got a follow-up? Ask IRIS
What caused the decline in Kanchi Karpooram’s FY26 earnings?
Kanchi Karpooram operates in camphor and allied products and also trades in agro products. Its FY26 revenue was broadly stable, but profitability weakened sharply. The available information linked the pressure to elevated raw-material prices, which reduced EBITDA margin to 5.3% in FY26.
A credit-rating update cited the company’s exposure to raw-material price volatility and intense competition as constraints on its financial performance. The same update said revenue was stagnant in FY26 and noted that profitability remained susceptible to volatility.
The company’s annual figures illustrate the gap between sales and earnings performance. While revenue slipped only ₹2.35 crore year-on-year in FY26, operating profit fell by ₹11.18 crore and net profit declined by ₹8.05 crore. This indicates that cost and margin movements had a greater effect on the year’s earnings than the modest change in revenue.
Kanchi Karpooram has said it is seeking higher capacity utilisation, a wider customer base and improved margins in FY27. These operating priorities are relevant because they address both volume growth and the cost pressures that affected FY26 profitability.
How does the June-quarter performance affect investors and operations?
The June-quarter figures showed a marked improvement in quarterly profitability compared with the March 2026 quarter. Operating profit increased by ₹5.19 crore sequentially and net profit improved by ₹3.96 crore. The improvement also lifted operating margin to 15.3%, compared with 2.75% shown for March 2026 in the supplied quarterly table.
For investors, the key issue is whether this recovery can be sustained when the September-quarter results are released. A single quarter does not establish an annual trend, particularly for a company whose margins have been affected by input-price movements and competition. The Q2 results will provide a further data point on revenue, margin and profit direction.
The company’s credit rating was reaffirmed at CRISIL BBB-/Stable, according to the cited rating update. That update referred to low bank-limit utilisation and free cash balances of ₹42 crore as of March 31, 2026, while also noting the business risks from raw-material volatility.
For customers and industry participants, the financial performance reflects conditions in the camphor market rather than a disclosed change in product availability or operations. The supplied information does not identify any plant shutdown, supply disruption, pricing change or new capacity commissioning during the June quarter.
Conclusion
Kanchi Karpooram entered Q2 FY27 results season after reporting a significant recovery in Q1 net profit, with June-quarter profit rising 113% year-on-year to ₹4.67 crore. The result contrasted with FY26, when revenue was nearly flat but operating profit and net profit fell more than 60% because of margin pressure.
The next item to watch is the board-approved Q2 and half-year FY27 financial statement scheduled for consideration on November 14, 2026. Investors will look for reported revenue growth, operating-margin movement, raw-material cost effects and progress on management’s stated plans for higher capacity utilisation, customer expansion and improved margins.