










K.C.P. Sugar Defers Rs 18.64 Crore in Seasonal Costs
Key highlights
- K.C.P. Sugar deferred Rs 18.64 crore of off-season costs at September 30, 2026.
- Other expenditure accounted for Rs 17.48 crore of K.C.P. Sugar’s disclosed deferral.
- Depreciation accounted for Rs 1.17 crore of K.C.P. Sugar’s deferred costs.
- K.C.P. Sugar reported the same Rs 18.64 crore figure in standalone and consolidated review reports.
powered by IRIS
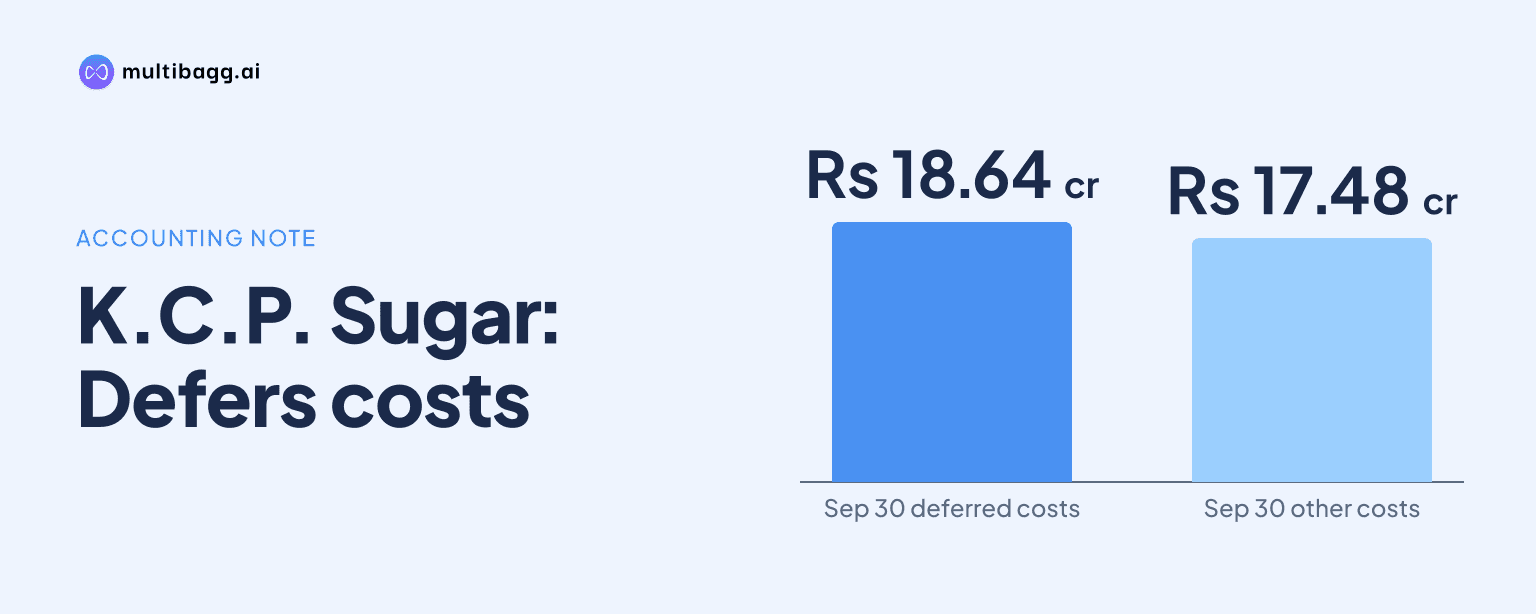
K.C.P. Sugar and Industries Corporation Limited deferred Rs 18.64 crore of off-season sugar and cogeneration costs for the quarter and six months ended September 30, 2026, comprising Rs 17.48 crore of other expenditure and Rs 1.17 crore of depreciation for recognition during the production season.
Know KCP Sugar & Industries Corporation inside out
Results, valuation, peers and who's buying, in one view.
Why did K.C.P. Sugar defer seasonal costs?
K.C.P. Sugar deferred the costs because its sugar unit and attached cogeneration unit are seasonal, while the sugar season does not correspond with the company’s April-to-March financial year. Management told the auditors that recording all off-season expenditure in the period incurred could substantially distort financial results across the quarters of a financial year.
For the quarter and six months ended September 30, 2026, K.C.P. Sugar recognised staff costs, manufacturing expenses within other expenses, and depreciation only to the extent linked to sugar manufactured and electric energy generated during that period. The remaining costs were treated as relating to sugar and electricity expected to be produced in the balance of the current sugar season.
The treatment changes the timing of expense recognition rather than removing the underlying expenditure. K.C.P. Sugar described this as a consistent practice of identifying off-season costs attributable to the coming season and recognising them in the season period; the consolidated review report says the remaining expenses will be absorbed at the end of the last quarter of the current sugar season.
What costs did K.C.P. Sugar defer at September 30, 2026?
K.C.P. Sugar deferred Rs 18.64 crore in disclosed costs at September 30, 2026, with other expenditure of Rs 17.48 crore representing the larger component and depreciation of Rs 1.17 crore making up the balance. The figures appear in both the standalone and consolidated auditors’ review reports.
K.C.P. Sugar’s disclosure says the other-expenditure category includes the relevant manufacturing expenses, while the narrative also refers to staff costs incurred during the off-season. The filing does not split the Rs 17.48 crore between staff costs and manufacturing expenses, so it does not establish the amount deferred for either underlying cost type.
Depreciation of Rs 1.17 crore was subject to the same production-linked approach for the September 2026 period. K.C.P. Sugar recognised depreciation attributable to sugar and electric energy produced in the quarter, while deferring the balance considered related to future output in the current season.
Does the policy apply to standalone and consolidated results?
K.C.P. Sugar disclosed the same Rs 18.64 crore deferred-cost amount in its standalone and consolidated review reports for September 30, 2026. In both reports, the policy applies specifically to the sugar unit and the incidental cogeneration unit attached to that sugar operation.
The standalone report refers to K.C.P. Sugar as the company and says the deferred expenses relate to sugar yet to be produced and electric energy yet to be generated. The consolidated report uses the term holding company, but reports the identical Rs 17.48 crore of other expenditure and Rs 1.17 crore of depreciation.
The consolidated accounts cover entities beyond the sugar and cogeneration operations. The filing lists KCP Sugars Agricultural Farms Limited and THE EIMCO-K.C.P Limited as subsidiaries, alongside Quality Engineering as a step-down subsidiary, meaning the identical seasonal-deferral figure does not indicate that all group costs and earnings are identical to standalone results.
For one step-down subsidiary, the consolidated auditor relied on another auditor’s review report for financial information that included total income of Rs 50.50 lakh and net profit before consolidation adjustments of Rs 3.17 lakh for the quarter ended September 30, 2026. The auditor said its conclusion was not modified in respect of reliance on that other auditor’s work.
Got a follow-up? Ask IRIS
How does the deferral affect September 2026 result comparisons?
K.C.P. Sugar’s recognised sugar and cogeneration costs for the September 2026 period exclude the Rs 18.64 crore deferred under the stated allocation method. Comparisons with a production-season quarter therefore need to distinguish between costs tied to output in the September period and costs incurred off-season but scheduled for recognition later.
The relevant comparison is between the off-season period ended September 30, 2026 and the later production period, rather than between a recurring cost and a cancelled charge. Under K.C.P. Sugar’s policy, expense recognition is shifted into the season period when the sugar and electric energy to which those costs relate are produced.
The standalone cash-flow statement provides a different measure from the expense-recognition disclosure. For the half year ended September 30, 2026, K.C.P. Sugar reported profit before tax of Rs 95.91 crore and net cash generated from operations of Rs 57.17 crore, while cash and cash equivalents were Rs 12.18 crore at September 30, 2026, compared with Rs 12.18 crore at March 31, 2026.
On a consolidated basis, profit before tax was Rs 100.48 crore for the half year ended September 30, 2026 and net cash generated from operations was Rs 86.02 crore. Consolidated cash and cash equivalents increased to Rs 19.75 crore at September 30, 2026 from Rs 14.85 crore at March 31, 2026, but the cash-flow statements do not present the seasonal deferral as a separate cash-flow adjustment.
What did the auditors say about K.C.P. Sugar’s accounting treatment?
K.C.P. Sugar’s auditors, B. Purushottam & Co., said that after considering the seasonal expense-recognition practice, nothing had come to their attention indicating that the standalone September 2026 results contained a material misstatement or failed to make required disclosures. The standalone review report was dated November 12, 2026.
The consolidated review report reached the same conclusion on the financial information for the quarter and six months ended September 30, 2026. It specifically considered the practice of deferring costs relating to future sugar production and electric-energy generation, including the Rs 17.48 crore other-expenditure amount and Rs 1.17 crore depreciation amount.
The work was a review under Standard on Review Engagements 2410, not a full audit. B. Purushottam & Co. stated that a review mainly involves enquiries and analytical procedures, provides moderate assurance, and does not result in an audit opinion under the Companies Act, 2013.
Conclusion
K.C.P. Sugar’s September 2026 disclosure means Rs 18.64 crore of off-season costs were not recognised immediately in sugar and cogeneration expenses. The disclosed amount consists of Rs 17.48 crore of other expenditure and Rs 1.17 crore of depreciation, and it was reported identically in the standalone and consolidated review reports.
The next point to watch is the end of the last quarter of the current sugar season, when the consolidated review report says the remaining deferred expenses will be absorbed. That recognition timing will determine the period in which the Rs 18.64 crore affects reported sugar and cogeneration costs.