










KS Smart Technologies approves Rs 1,324.5486 crore unit absorption
Key highlights
- KSSTL approved the absorption of wholly owned KSSPL on November 14, 2026.
- KSSPL reported FY 2025-26 turnover of Rs 1,324.5486 crore and total assets of Rs 1,733.3156 crore.
- KSSTL reported FY 2025-26 standalone turnover of Rs 2.0563 crore and total assets of Rs 224.7941 crore.
- The scheme provides for no new KSSTL shares, no cash consideration and no change in KSSTL's shareholding pattern.
powered by IRIS
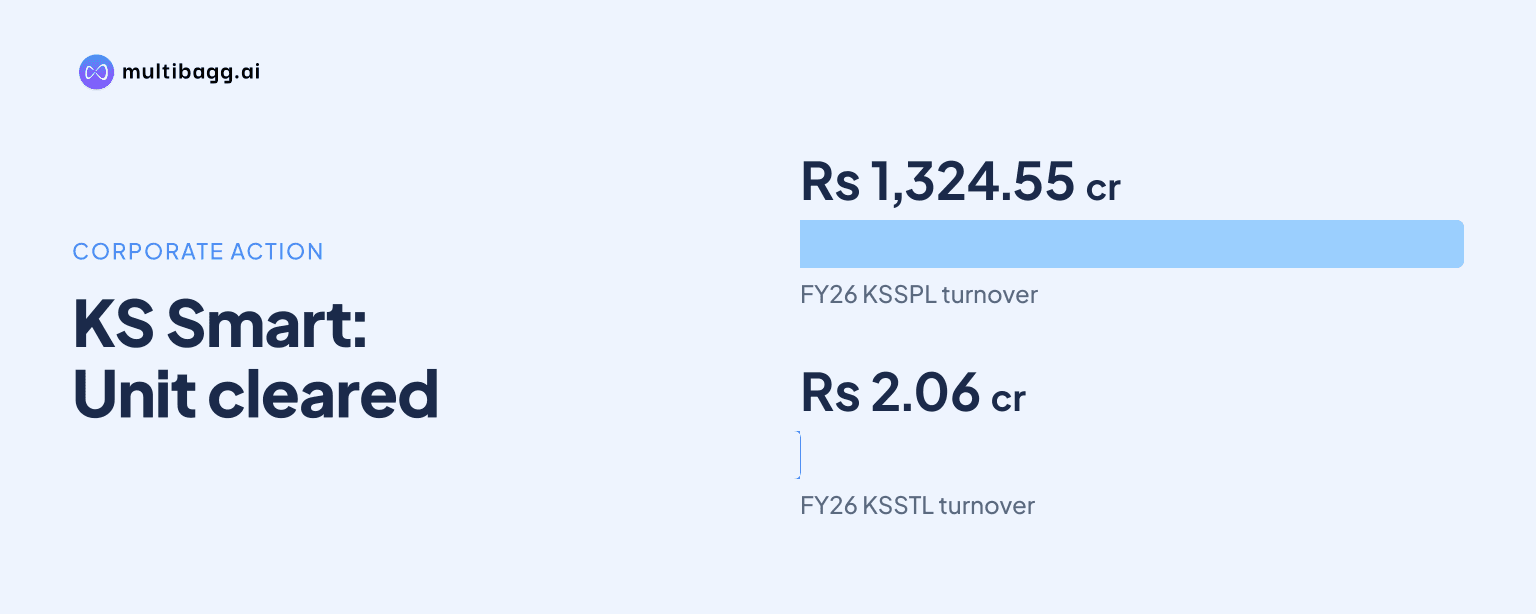
KS Smart Technologies Limited approved on November 14, 2026 the absorption of wholly owned KS Smart Solutions Private Limited, whose FY 2025-26 turnover was Rs 1,324.5486 crore, into the listed parent without issuing shares or paying consideration. The scheme remains subject to necessary approvals and cites April 1, 2026, or another NCLT-approved date, for effect.
Know KS Smart Technlogies inside out
Results, valuation, peers and who's buying, in one view.
What did KSSTL approve on November 14, 2026?
KSSTL approved a Scheme of Amalgamation under Sections 230 and 232 of the Companies Act, 2013, to merge KS Smart Solutions Private Limited, or KSSPL, into KSSTL. The board approved the proposal at its November 14, 2026 meeting, disclosed to BSE Limited under Regulation 30 of the Securities and Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015. KSSPL is the transferor company and KSSTL is the transferee company.
The board approval does not itself make the scheme effective because the filing says it remains subject to necessary approvals. KSSTL states that the scheme will take effect from April 1, 2026, or another date approved by the National Company Law Tribunal (NCLT). The disclosure does not provide a completion deadline or identify each approval required before implementation.
How does KSSPL compare with KSSTL in FY 2025-26?
KSSPL reported FY 2025-26 turnover of Rs 1,324.5486 crore, compared with Rs 2.0563 crore reported by KSSTL on the disclosed standalone financial basis. The transferor’s turnover was therefore substantially higher than that of the listed transferee in the same audited financial year. The figures in the filing are based on audited statements for FY 2025-26.
KSSPL also reported total assets of Rs 1,733.3156 crore, against Rs 224.7941 crore for KSSTL, while its net worth was Rs 294.7227 crore versus Rs 221.8516 crore. The proposed absorption would therefore bring an entity with higher disclosed turnover, assets and net worth into KSSTL, although the difference in net worth was narrower than the differences in turnover and assets.
Why is KSSTL merging KSSPL into the parent?
KSSTL says the merger is intended to generate operational synergies, optimise resources and rationalise costs following its October 2025 acquisition of KSSPL’s entire share capital. According to the filing, that acquisition was intended to strengthen KSSTL’s market position and its ability to deliver innovative solutions. The proposed amalgamation is the subsequent restructuring step disclosed after that October 2025 acquisition.
Management’s stated rationale also covers economies of scale, enhanced management efficiency, consolidation of human capital and organisational capabilities, and lower administrative, regulatory and compliance costs. KSSTL says the merger by absorption is expected to help realise the businesses’ potential and create value for shareholders, customers, creditors and employees. The filing provides no target for cost savings, earnings, cash flow or integration expenses.
Both companies offer hardware and software solutions, information technology infrastructure services, skill development and training, manpower solutions, and smartphones and tablets with value-added services. Their disclosed activities also include augmented reality (AR), virtual reality (VR), smart-city solutions, e-commerce, retail and digital marketing, as well as facilitating projects tendered by State and Union Government bodies and other organisations.
Got a follow-up? Ask IRIS
Will the KSSPL merger change KSSTL shares or ownership?
KSSTL says the merger will not change its shareholding pattern, and it will not issue any new shares. Because KSSPL is wholly owned by KSSTL, the filing says no shares of KSSTL will be allotted and no cash or other consideration will be paid for KSSTL’s holding in KSSPL.
This structure means the scheme does not disclose a share-exchange ratio or payment to outside KSSPL shareholders. KSSTL already owns KSSPL’s entire share capital, so the proposal is an internal absorption of the subsidiary rather than an acquisition from minority holders. The filing specifically states that no dilution will arise through the issue of new KSSTL shares.
KSSTL identifies the transaction as involving a related party because KSSPL is its wholly owned subsidiary. However, the company says the related-party requirements under Section 188 of the Companies Act do not apply, citing a Ministry of Corporate Affairs general circular dated July 17, 2014. It also says Regulation 23 related-party provisions do not apply to transactions between a holding company and a wholly owned subsidiary where the subsidiary’s accounts are consolidated with the holding company.
What will change after KSSPL is absorbed?
The scheme would place the assets, turnover and operations now held in KSSPL within KSSTL once it becomes effective. On the disclosed FY 2025-26 figures, the transferor brings Rs 1,733.3156 crore of total assets and Rs 1,324.5486 crore of turnover, rather than remaining a separately incorporated wholly owned subsidiary. KSSTL frames this legal consolidation as supporting resource optimisation and lower duplicated administrative, regulatory and compliance activity.
The filing does not disclose a pro forma post-merger balance sheet, projected profit, employee count, integration-cost estimate or quantified savings. It also does not state how the operations will be reorganised after the legal absorption. The available disclosure therefore sets out the entities’ audited FY 2025-26 scale and management’s stated rationale, but not a quantified forecast of the merger’s financial effects.
The scheme’s cited effective date of April 1, 2026 precedes the board approval date of November 14, 2026. KSSTL expressly allows for another date if approved by the NCLT, making the approval process relevant to final timing. Until necessary approvals are received and the scheme takes effect, KSSPL remains the wholly owned transferor subsidiary identified in the announcement.
Conclusion
KSSTL has approved an internal absorption that would move a FY 2025-26 Rs 1,324.5486 crore-turnover subsidiary into the listed parent without issuing shares, paying consideration or changing the stated shareholding pattern. KSSPL’s Rs 1,733.3156 crore asset base, compared with Rs 224.7941 crore at KSSTL, shows that the proposal materially changes the group’s legal operating structure.
The next disclosed matter to watch is the necessary approval process, particularly the NCLT’s approval of the scheme and its effective date. KSSTL cites April 1, 2026 as the date from which the scheme is to take effect, while allowing the NCLT to approve another date; the filing gives no quantified integration savings, post-merger forecast or completion deadline.