










MAN Industries (India) Ltd: NPC added ₹531.9 crore revenue
Key highlights
- NPC contributed ₹531.9 crore of revenue to MAN from 21 May to 30 September 2026.
- NPC added ₹93.6 crore of EBITDA and ₹78.6 crore of PAT in the post-acquisition period.
- NPC reported ₹485.6 crore of revenue and ₹87.5 crore of EBITDA in Q3 CY26.
- The acquisition added 430,000 MTPA of Saudi pipe capacity to MAN.
powered by IRIS
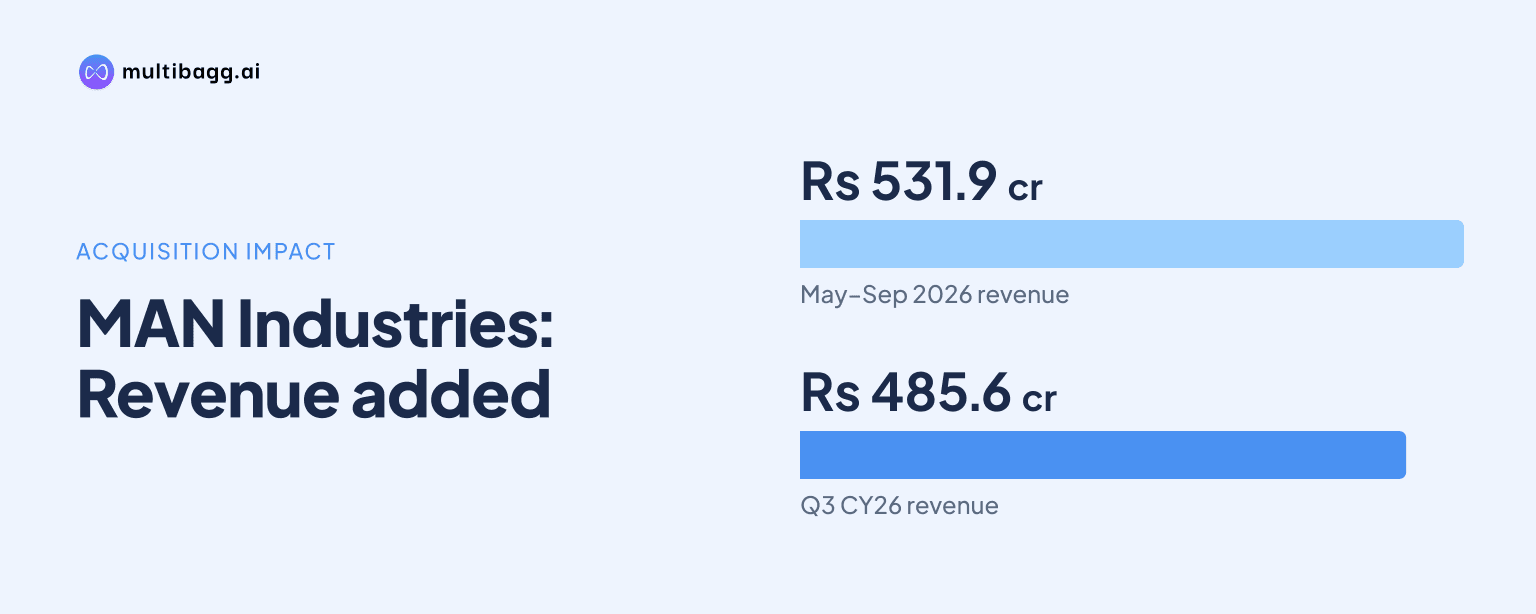
MAN added ₹531.9 crore of revenue, ₹93.6 crore of earnings before interest, tax, depreciation and amortisation (EBITDA), and ₹78.6 crore of profit after tax (PAT) from National Pipe Company (NPC) between 21 May and 30 September 2026. The Saudi acquisition's reported contribution carried a 17.6% EBITDA margin and a 14.8% PAT margin.
Know Man Industries (India) inside out
Results, valuation, peers and who's buying, in one view.
How much did NPC add to MAN after the acquisition?
NPC added ₹531.9 crore of revenue and ₹78.6 crore of PAT to MAN between the 21 May 2026 acquisition and 30 September 2026. The presentation calculates this contribution by deducting NPC's performance from 1 January to 21 May 2026 from its year-to-date calendar-year results through September, rather than attributing all nine months to MAN.
NPC also contributed ₹110.5 crore of gross profit, ₹93.6 crore of EBITDA and ₹95.6 crore of profit before tax (PBT) in the post-acquisition period. Revenue of ₹531.9 crore produced a 20.8% gross margin, a 17.6% EBITDA margin and a 14.8% PAT margin, based on the presentation's stated revenue-margin calculations.
The ₹78.6 crore PAT figure was 83.9% of the ₹93.6 crore EBITDA reported for the acquired-period contribution, while PBT was ₹95.6 crore. These are reported operating and profit measures from NPC's management sheet, converted using the presentation's implied period-average exchange rate of ₹25.57 per Saudi riyal for the year-to-date and post-acquisition columns.
What did NPC report in the July-September 2026 quarter?
NPC reported ₹485.6 crore of revenue and ₹76.8 crore of PAT in Q3 CY26, defined in the presentation as July to September 2026. It generated ₹87.5 crore of EBITDA, ₹99.9 crore of gross profit and ₹89.2 crore of PBT during the quarter, which management described as the first full quarter after the acquisition.
Q3 CY26 EBITDA margin was 18.0%, compared with 17.6% for the 21 May to 30 September contribution period, a difference of 0.4 percentage points. Gross margin was 20.6% in Q3 versus 20.8% for the acquired-period contribution, while PAT margin was 15.8% in Q3 compared with 14.8% over the contribution period.
Q3 revenue of ₹485.6 crore represented 45.8% of NPC's ₹1,060.5 crore revenue for January to September 2026, although the periods are not directly comparable because one covers three months and the other nine. Q3 PAT of ₹76.8 crore was 45.0% of the ₹170.6 crore reported for the year to date, with the Q3 PAT margin of 15.8% below the year-to-date margin of 16.1%.
Got a follow-up? Ask IRIS
How did NPC's acquired-period profitability compare with year-to-date results?
NPC's 17.6% EBITDA margin for MAN's 21 May to 30 September contribution was 0.6 percentage points below its 18.2% year-to-date CY26 margin. Its 14.8% PAT margin was 1.3 percentage points below the 16.1% margin reported for January to September, while gross margin was 20.8%, compared with 21.6% year to date.
In absolute terms, NPC reported ₹192.9 crore of EBITDA and ₹170.6 crore of PAT for YTD CY26, against the ₹93.6 crore EBITDA and ₹78.6 crore PAT attributed to MAN since 21 May. The presentation applies an implied ₹25.57 per Saudi riyal to the YTD and acquired-period figures, while Q3 figures use an implied ₹25.41 rate.
The acquired-period figures account for ₹531.9 crore of NPC's ₹1,060.5 crore YTD revenue, or roughly half of the nine-month total. That relationship reflects the 21 May acquisition cut-off and does not identify the revenue or profit generated by NPC from 1 January to 21 May, which is excluded from MAN's stated contribution.
What capacity and market position came with MAN's Saudi acquisition?
MAN acquired 430,000 metric tonnes per annum (MTPA) of pipe capacity through NPC in Saudi Arabia. The asset comprises 250,000 metric tonnes of HSAW capacity and 180,000 metric tonnes of LSAW capacity.
NPC is an Aramco-approved vendor and, according to the presentation, is the only company in Saudi Arabia with manufacturing facilities for both LSAW and HSAW pipes. MAN's Indian pipe capacity is stated as more than 1.2 million MTPA across Anjar, Gujarat and Pithampur, Madhya Pradesh, compared with the acquired Saudi capacity of 430,000 MTPA.
The Saudi manufacturing footprint is in Dhahran and is identified as NPC-MSIC in MAN's presentation, while the NPC office is in Al Khobar. In addition to the acquired facility, MAN has targeted March 2027 production for a 4 million square metre Dammam coating plant offering three-layer polyethylene, fusion-bonded epoxy and internal coating, which the company says would add a value-added margin layer.
Conclusion
The disclosed post-acquisition contribution shows that NPC added ₹531.9 crore of revenue and ₹78.6 crore of PAT to MAN between 21 May and 30 September 2026, with a 17.6% EBITDA margin. Q3 CY26, the first full quarter after the transaction, delivered ₹485.6 crore of revenue and ₹87.5 crore of EBITDA, providing the principal reported quarter for assessing the acquired operation's scale.
What to watch next is management's expectation that NPC will continue to contribute meaningfully now that integration is complete. The next disclosed operating milestones are the targeted March 2027 start for the Dammam coating plant and April 2027 production start for MAN's 22,000-MTPA Jammu stainless-steel seamless pipe facility, where ₹350 crore had been incurred through Q2 FY27 against planned capex of about ₹600 crore.