










MMTC consolidated results exclude four unavailable entities
Key highlights
- MMTC excluded MTPL and three joint ventures from consolidated results for the half year ended 30 September 2026.
- MMTC’s Rs 3.14 crore investment in liquidating subsidiary MTPL was fully provided for at 30 September 2026.
- MMTC PAMP India contributed Rs 26.21 crore of joint-venture profit in the September 2026 half year, down from Rs 44.81 crore a year earlier.
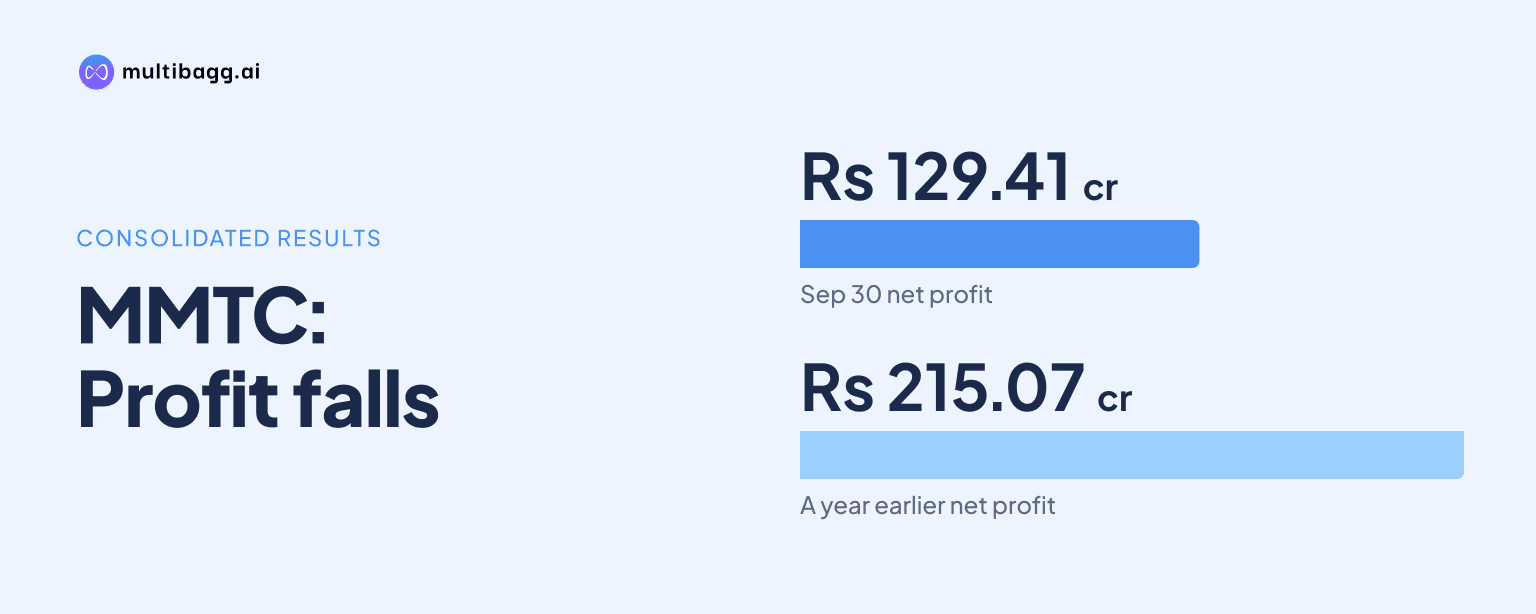
- MMTC reported consolidated net profit of Rs 129.41 crore for the September 2026 half year, versus Rs 215.07 crore a year earlier.
powered by IRIS
MMTC Limited’s consolidated results for the half year ended 30 September 2026 exclude four entities whose current financial information was unavailable, including liquidating Singapore subsidiary MMTC Transnational Pte. Ltd. (MTPL); MMTC has fully provided for its Rs 3.14 crore MTPL investment and fully impaired or provided for the three excluded joint ventures.
Know MMTC inside out
Results, valuation, peers and who's buying, in one view.
Which MMTC entities are excluded from the consolidated results?
MMTC excluded MTPL and three joint ventures, MMTC Gitanjali Limited, Sical Iron Ore Terminal Ltd. and Free Trade Warehousing Pvt. Ltd., from its consolidated results for the quarter and half year ended 30 September 2026. The company said it had not received financial results from the three joint ventures, while MTPL’s financial information was unavailable after control passed to liquidators.
The exclusions do not cover every joint venture. MMTC included its share of results from MMTC PAMP India Private Limited, for which reviewed interim financial information was available. MMTC PAMP India contributed Rs 15.70 crore of net profit after tax in the quarter ended 30 September 2026 and Rs 26.21 crore in the half year ended on that date.
The scope limitation extends to reported segment information as well as the consolidated income statement and balance sheet. MMTC stated that MTPL’s financials were excluded from both consolidated financial results and segment-wise information for the half year ended 30 September 2026. The filing does not state MTPL’s unavailable revenue, profit, assets or liabilities for that period.
Why is MTPL absent from MMTC’s September 2026 results?
MTPL is absent because the High Court of the Republic of Singapore appointed Deloitte & Touche LLP, Singapore as joint and several liquidators at a liquidation hearing on 27 October 2023, when a winding-up order was passed. MMTC said control of the subsidiary subsequently transferred to the liquidators, leaving it without financial inputs for the quarter and half year ended 30 September 2026.
MMTC said its Rs 3.14 crore book-value investment in MTPL had been fully provided for as at 30 September 2026. That provision addresses the carrying value of the investment in MMTC’s accounts, but the filing does not provide financial information from MTPL for the current reporting period. The liquidation process was still continuing under Singapore law when the results were approved on 10 November 2026.
MMTC also disclosed a complaint filed with the Central Bureau of Investigation, or CBI, on 4 October 2023 over alleged financial irregularities and fraud at MTPL. The CBI registered a preliminary enquiry on 3 April 2024 and a regular case on 15 October 2024. The announcement does not quantify any financial impact from those proceedings beyond the Rs 3.14 crore investment provision.
What happened to the three excluded joint ventures?
MMTC had already fully impaired or provided for its investments in the three excluded joint ventures before the 30 September 2026 reporting date. Its Rs 2.99 crore equity investment in MMTC Gitanjali was fully impaired during 2017-18, and MMTC said it had served notice to exit that venture. Sical Iron Ore Terminal and Free Trade Warehousing each had 100% provisions, according to the company’s notes.
Impairment and provisioning do not replace the missing current-period financial statements. Consequently, MMTC’s consolidated results exclude the three ventures’ current share of profit or loss, other comprehensive income, and movements in assets and liabilities for the September 2026 quarter and half year. The independent reviewer specifically identified the non-receipt of their financial results for both periods.
The treatment differs from MMTC PAMP India, which remained in the consolidated results using the equity method. MMTC’s share of profit from that venture fell to Rs 26.21 crore in the half year ended 30 September 2026 from Rs 44.81 crore in the corresponding half year of 2025. Thus, the reported joint-venture profit for the period reflects the available results of one venture rather than all of MMTC’s joint-venture interests.
Got a follow-up? Ask IRIS
How did MMTC’s reported consolidated figures change year on year?
MMTC reported consolidated profit before tax of Rs 161.71 crore for the half year ended 30 September 2026, down from Rs 483.02 crore in the corresponding 2025 half year. Consolidated net profit declined to Rs 129.41 crore from Rs 215.07 crore. Both periods’ reported figures should be read with the stated absence of MTPL and the three joint ventures from the latest reporting scope.
Revenue from operations decreased by Rs 0.51 crore year on year, while the reported share of joint-venture profit declined by Rs 18.60 crore. Other comprehensive income was negative Rs 26.44 crore in the September 2026 half year, compared with positive Rs 6.09 crore a year earlier, contributing to the change in total comprehensive income. These numbers do not establish what the four excluded entities would have contributed because their current financial data were not included in the filing.
MMTC’s consolidated other equity was Rs 2,114.52 crore at 30 September 2026, compared with Rs 1,970.72 crore at 31 March 2026. Total consolidated assets were Rs 2,959.80 crore at 30 September 2026, versus Rs 2,795.87 crore at 31 March 2026. The segment and consolidated balance-sheet figures exclude MTPL’s financial information under the stated scope limitation.
What did the independent reviewer conclude about the omissions?
R S P H & Associates did not modify its conclusion because of the excluded subsidiary and three joint ventures. The reviewer included the matter as an emphasis of matter, noting MTPL’s liquidation and the non-receipt of results from MMTC Gitanjali, Sical Iron Ore Terminal and Free Trade Warehousing for the quarter and half year ended 30 September 2026.
The reviewer’s qualified conclusion related instead to the separate Anglo Coal matter. It said MMTC had recognised Rs 87.76 crore of an estimated Rs 170.58 crore present obligation as at 17 November 2025, leaving Rs 82.82 crore unrecognised in the accounts and included in contingent liabilities. The reviewer said recognition of that amount would have increased provisions and reduced other equity by Rs 82.82 crore as at 30 September 2026.
The review was conducted under Standard on Review Engagements 2410, which provides moderate assurance and is less extensive than an audit. MMTC’s Board approved the unaudited quarter and half-year results on 10 November 2026 without Audit Committee review because independent directors had not been appointed, according to the filing. The reviewer said its conclusion on the MTPL and joint-venture omissions was not modified.
Conclusion
MMTC’s reported September 2026 consolidated numbers have a defined reporting boundary: MTPL and three joint ventures were excluded because current financial information was unavailable, while MMTC PAMP India remained included and contributed Rs 26.21 crore of half-year joint-venture profit. The investment carrying amounts were addressed through full impairment or provisions, but the filing does not quantify the excluded entities’ current operational or balance-sheet contribution.
The next disclosures to watch are whether the Singapore liquidation that began with the 27 October 2023 winding-up order produces further accounting information on MTPL, and whether the three joint ventures submit results. MMTC also disclosed a 3 December 2026 Delhi High Court hearing in the Anglo Coal matter on foreign-exchange rate and withholding-tax questions, which remain unresolved.