










NBCC says Rs 100 crore marketing fee lifted Q2 EBITDA margin
Key highlights
- NBCC reported an 8% EBITDA margin in Q2 after reporting 9% in Q1.
- NBCC said it recorded approximately Rs 100 crore of marketing fees in the half year.
- NBCC cited consolidated revenue of Rs 3,400 crore in Q2 versus Rs 2,260 crore in Q1.
- NBCC expects to book about Rs 433 crore from two land-parcel sales in the current quarter.
powered by IRIS
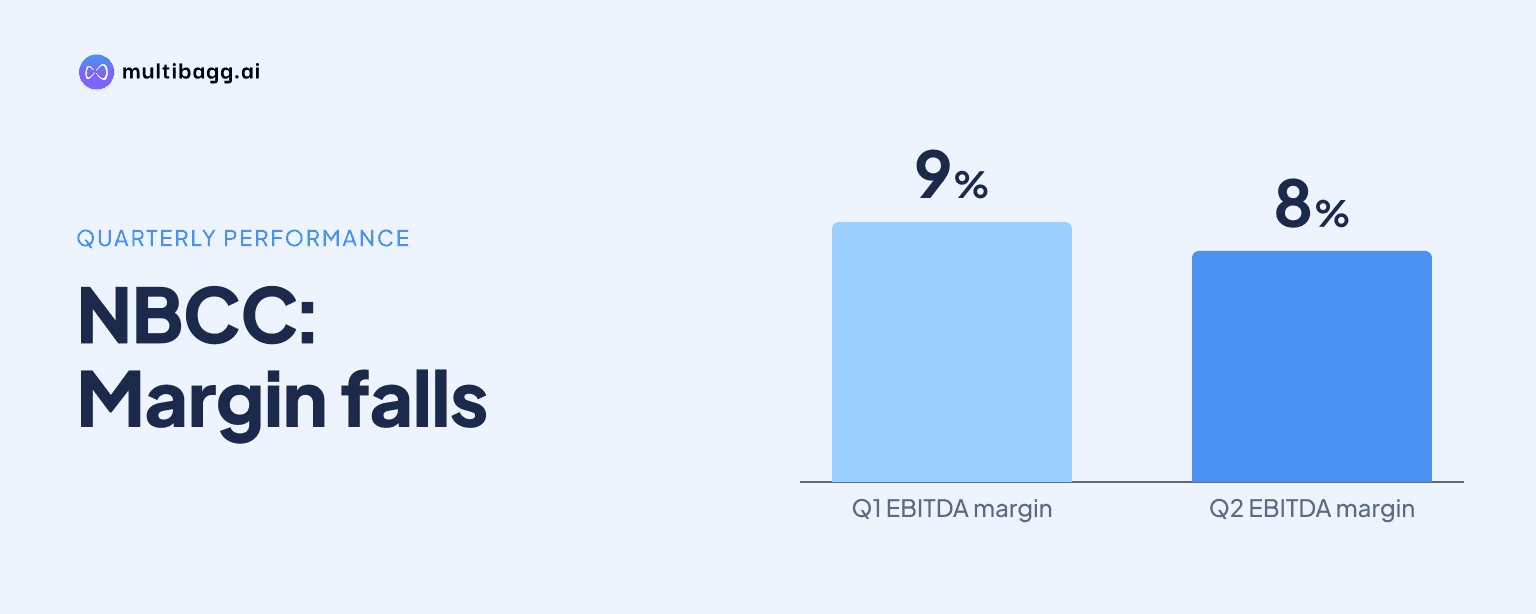
NBCC (India) Limited said its earnings before interest, tax, depreciation and amortisation (EBITDA) margin was 8% in the second quarter (Q2), after 9% in the first quarter (Q1), because it recorded about Rs 100 crore of marketing fees in the half year and benefited from higher revenue against a fixed cost base. Management said the movement was not solely an execution-margin improvement.
Know NBCC (India) inside out
Results, valuation, peers and who's buying, in one view.
What lifted NBCC's EBITDA margin to 8% in Q2?
NBCC said approximately Rs 100 crore of marketing fee recorded in the half year was the primary identified factor behind the EBITDA increase. Finance Director Anjeev Kumar Jain said the fee arose from selling a self-sustainable project on behalf of the Ministry of Housing and Urban Affairs, while the reported EBITDA margin was 8% in Q2 and 9% in Q1.
Management had previously described EBITDA as generally being in a 5-6% range. The disclosed Rs 100 crore fee therefore adds an income stream linked to marketing and sale activity, rather than construction execution alone, to the reported 8-9% margin range. NBCC did not disclose a numerical split between the effect of the fee and the effect of revenue-led fixed-cost absorption.
How did higher revenue affect NBCC's Q2 margin?
NBCC said higher revenue improved EBITDA because its cost structure is largely fixed. Jain said revenue increased in both Q2 and the half year, allowing costs to be spread over a larger revenue base, and management described that income mechanism as perennial rather than an unspecified one-off.
Management cited a Rs 67 crore increase in one set of revenue figures, to Rs 1,890 crore in Q2 from Rs 1,823 crore in Q1. It also cited a Rs 1,140 crore increase in consolidated revenue, to Rs 3,400 crore in Q2 from Rs 2,260 crore in Q1, in explaining the greater fixed-cost absorption.
The Q1-to-Q2 comparison shows that both marketing income and revenue volume featured in management's explanation. Q2 EBITDA margin was 8%, one percentage point below Q1's 9%, despite the larger Q2 consolidated revenue figure of Rs 3,400 crore. The transcript does not provide an execution-only margin for either quarter.
Will NBCC's marketing-fee income recur?
NBCC management said the marketing-income mechanism is perennial because it stems from the company's role in sales of self-sustainable projects. However, the only disclosed amount was approximately Rs 100 crore for the half year, and management gave no annual target or schedule for further marketing-fee recognition.
The redevelopment portfolio provides the context for this income stream. NBCC said it sold 8.8 lakh square feet of residential apartments at Avenue Towers, Sarojini Nagar, New Delhi, for Rs 5,191 crore through an open e-auction, while redevelopment projects had Rs 9,200 crore of balance workload and all major packages were running.
NBCC also outlined land monetisation that could affect reported revenue, although its accounting characteristics may differ from marketing fees. Management said it had sold two land parcels in Q3 and expected to book about Rs 433 crore of revenue from those sales in the current quarter; two further land-parcel requests for proposal were in the pipeline.
Got a follow-up? Ask IRIS
What could affect NBCC's second-half profitability?
NBCC maintained management guidance for FY27 consolidated revenue of Rs 15,000-16,000 crore and profit after tax of Rs 1,100-1,200 crore. It also maintained standalone revenue guidance of Rs 13,000-14,000 crore, saying the first and second quarters are usually slower than the later part of the year.
Management said Rs 15,000-16,000 crore of work could be awarded during the year, including Supertech and Jammu & Kashmir projects, with turnover from those projects expected from the next quarter onwards. NBCC also said about Rs 33,000 crore of projects were running and that another Rs 16,000-17,000 crore could be added next year.
Delhi construction sites face a specific execution risk when the air quality index triggers restrictions, although management said operations elsewhere in India were progressing. It also cited funding, approvals and tender processes as reasons for delays at MAHAPREIT and Jammu & Kashmir, while saying MAHAPREIT was expected to start during the year.
How does NBCC's project mix shape its earnings?
NBCC said redevelopment accounts for about 60% of its own order mix and project management consultancy (PMC) accounts for 40%. On a consolidated basis, management put the mix at 53% redevelopment and 47% PMC, making redevelopment-related sales and marketing activity relevant to the broader earnings composition.
Management expects Rs 50,000-60,000 crore of work orders during the year, including a potential Rs 30,000-35,000 crore from five General Pool Residential Accommodation projects. It said the five-project award could arrive in the current or next quarter, subject to the approval process.
Revenue recognition may not coincide with sales or cash collections in every project. For the Dubai operation, NBCC said first-phase sales were planned by the end of December or in January 2027, but revenue would be recognised only after completion and possession. That timing distinction also matters when assessing announced land monetisation and project sales.
Conclusion
NBCC's reported 8% Q2 EBITDA margin and 9% Q1 margin reflected a combination of approximately Rs 100 crore of half-year marketing fees and operating leverage from higher revenue over a fixed cost base. Management's explanation means the margin movement cannot be attributed to construction execution economics alone.
The next disclosures to watch are whether NBCC books the expected Rs 433 crore of land-sale revenue in the current quarter, how the planned Rs 15,000-16,000 crore of annual awards convert into execution, and whether the five General Pool Residential Accommodation approval process progresses within the current or next quarter.