










Polyspin associate supplied nearly half of first-half profit
Key highlights
- Polyspin reported Rs 3.66 crore consolidated profit after tax for the six months ended 30 September 2026.
- Lankaspin contributed Rs 1.81 crore of associate profit in the first half, compared with Rs 1.03 crore a year earlier.
- The auditor cited Rs 1.89 crore of associate profit using management-furnished results it did not review.
- Polyspin recorded negative Rs 7.02 crore operating cash flow as inventories increased by Rs 12.15 crore.
powered by IRIS
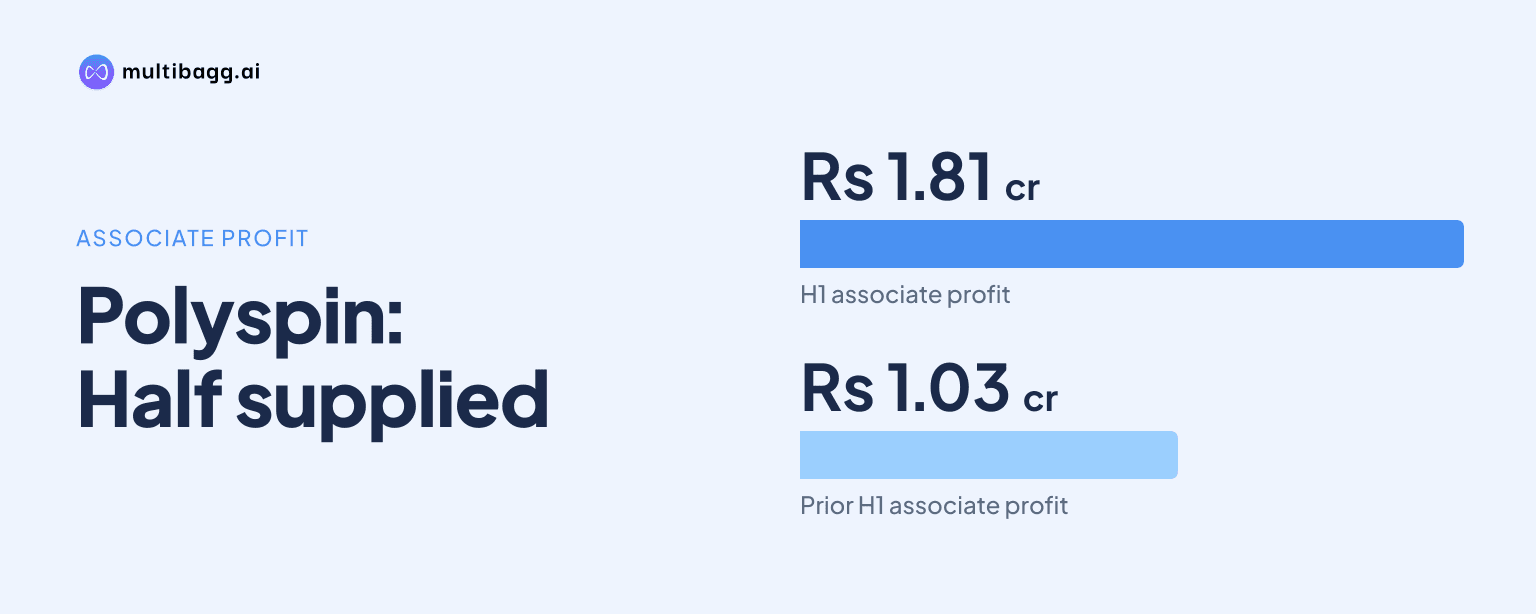
Polyspin Exports Limited reported a Rs 1.81 crore share of associate profit for the six months ended 30 September 2026, accounting for about half of its Rs 3.66 crore consolidated profit after tax. Its auditor did not review the Sri Lankan associate’s unaudited results and considered management-furnished information for those amounts.
Know Polyspin Exports inside out
Results, valuation, peers and who's buying, in one view.
How much did Lankaspin contribute to Polyspin’s first-half profit?
Lankaspin Private Limited contributed Rs 1.81 crore to Polyspin’s consolidated profit after tax for the six months ended 30 September 2026. The amount, reported as the share of profit of associates net of tax, rose from Rs 1.03 crore in the corresponding six months ended 30 September 2025, while total consolidated profit after tax fell to Rs 3.66 crore from Rs 3.82 crore.
The Rs 1.81 crore associate-profit share was about 49.6% of Polyspin’s reported first-half profit after tax of Rs 3.66 crore. Profit after tax from continuing operations, before the associate share, declined to Rs 1.84 crore from Rs 2.79 crore a year earlier. The higher associate contribution therefore partly offset the Rs 0.95 crore decline in profit from continuing operations.
Lankaspin’s contribution was also material in the September quarter. Polyspin reported Rs 1.07 crore as its share of associate profit for the quarter ended 30 September 2026, compared with Rs 0.75 crore in the June 2026 quarter and Rs 0.77 crore in the September 2025 quarter. Consolidated profit after tax was Rs 2.15 crore in the latest quarter, up from Rs 1.50 crore in the preceding quarter.
Why did Polyspin’s auditor rely on management-furnished associate results?
Polyspin’s auditor relied on results furnished by management because it did not review the unaudited financial results of Lankaspin for the six months ended 30 September 2026. Krishnan and Raman Chartered Accountants said its conclusion on the associate-related amounts and disclosures was based on management reports and the review procedures it performed under the applicable framework.
The auditor identified Lankaspin as an associate in Sri Lanka and said its financial statements reflected Polyspin’s share of net profit after tax of Rs 1.89 crore for the six-month period. It also cited Rs 1.89 crore as Polyspin’s share of the associate’s total comprehensive income. The auditor said its conclusion was not modified in respect of this matter.
The review report dated 11 November 2026 explains that a limited review provides moderate assurance and is narrower in scope than an audit. It involves inquiries of personnel responsible for financial and accounting matters, alongside analytical and other review procedures, and does not result in an audit opinion. The auditor also said it performed procedures required under Regulation 33 of the Securities and Exchange Board of India framework to the extent applicable.
Why do Polyspin’s associate-profit disclosures show different amounts?
Polyspin’s detailed consolidated results show Rs 1.81 crore as the first-half share of profit of associates, while the auditor’s report cites Rs 1.89 crore as its share of Lankaspin’s net profit after tax and total comprehensive income. The difference is Rs 8 lakh for the same six months ended 30 September 2026.
The filing does not reconcile the Rs 1.81 crore shown in the consolidated profit-and-loss statement with the Rs 1.89 crore stated in the auditor’s report. It does not identify whether the Rs 8 lakh difference results from a consolidation adjustment, presentation difference or another accounting item. The results statement reports the associate line as profit net of tax, whereas the audit report separately describes net profit after tax and total comprehensive income.
Polyspin reported total comprehensive income of Rs 2.87 crore for the first half, lower than its Rs 3.66 crore total profit after tax because other comprehensive income was negative Rs 0.78 crore. In the September 2026 quarter, other comprehensive income included Rs 0.42 lakh of mark-to-market profit on export forward contracts, recognised under Indian Accounting Standard 109 cash-flow hedge accounting. That note does not explain the associate-figure difference.
Got a follow-up? Ask IRIS
How did Polyspin’s continuing operations perform without the associate?
Polyspin’s revenue from operations rose to Rs 118.72 crore in the six months ended 30 September 2026 from Rs 116.23 crore a year earlier, but profit before tax from continuing operations declined to Rs 2.62 crore from Rs 3.39 crore. Total income increased to Rs 121.75 crore from Rs 117.84 crore, including other income of Rs 3.04 crore against Rs 1.60 crore in the prior-year period.
Cost movements were mixed across the first half. Material costs were Rs 76.01 crore, against Rs 75.88 crore a year earlier, while employee-benefit expense fell to Rs 19.73 crore from Rs 20.60 crore and finance cost declined to Rs 2.33 crore from Rs 3.12 crore. Other expenses increased to Rs 25.22 crore from Rs 21.42 crore, exceeding the Rs 3.91 crore rise in total income.
The continuing operations reported in the consolidated results entirely relate to flexible intermediate bulk container, or FIBC, operations. Polyspin said it had discontinued its textile division and completely disposed of its assets during the second quarter of financial year 2024-25. It therefore does not report textile-segment performance under Indian Accounting Standard 108.
What changed in Polyspin’s cash flow and borrowings?
Polyspin recorded negative operating cash flow of Rs 7.02 crore for the six months ended 30 September 2026, compared with positive operating cash flow of Rs 32.40 crore for the year ended 31 March 2026. The first-half cash outflow followed a Rs 12.15 crore increase in inventories and a Rs 5.25 crore increase in trade receivables, against operating profit before working-capital changes of Rs 6.58 crore.
Current borrowings rose to Rs 68.53 crore at 30 September 2026 from Rs 49.04 crore at 31 March 2026. Non-current borrowings moved in the other direction, declining to Rs 16.58 crore from Rs 21.83 crore. Financing cash flow was positive Rs 12.47 crore in the first half, including Rs 16.76 crore of working-capital borrowings net of repayments.
Cash and cash equivalents increased to Rs 1.06 crore at 30 September 2026 from Rs 0.29 crore at 31 March 2026. Polyspin also reported Rs 19.97 crore of other bank balances at the September reporting date, versus Rs 16.97 crore at the preceding financial year-end, while total assets rose to Rs 185.91 crore from Rs 162.97 crore.
Conclusion
Polyspin’s consolidated first-half outcome depended materially on Lankaspin, whose Rs 1.81 crore reported profit contribution represented about half of the Rs 3.66 crore consolidated profit after tax. Revenue increased by Rs 2.49 crore year on year, but the decline in continuing-operations profit and the negative Rs 7.02 crore operating cash flow give important context to the higher associate contribution.
The next disclosed matter to watch is Tamil Nadu’s notification of rules on the minimum floor wage under the labour-code framework. Polyspin said management would conduct a detailed impact study after that notification and make changes to employee-cost structures if necessary; management’s present view is that no material provision is needed for the year under review.