










Rajesh Exports Ltd. Board Meets November 14 for Q2 Results
Key highlights
- Rajesh Exports Ltd. will consider Q2 FY27 unaudited results on November 14, 2026.
- Rajesh Exports reported Q1 FY27 revenue of ₹2,40,336 crore and net profit of ₹47 crore.
- Q2 FY26 revenue was ₹1,75,212 crore, while net profit was ₹104 crore.
- Rajesh Exports filed its board-meeting intimation on November 12, 2026.
powered by IRIS
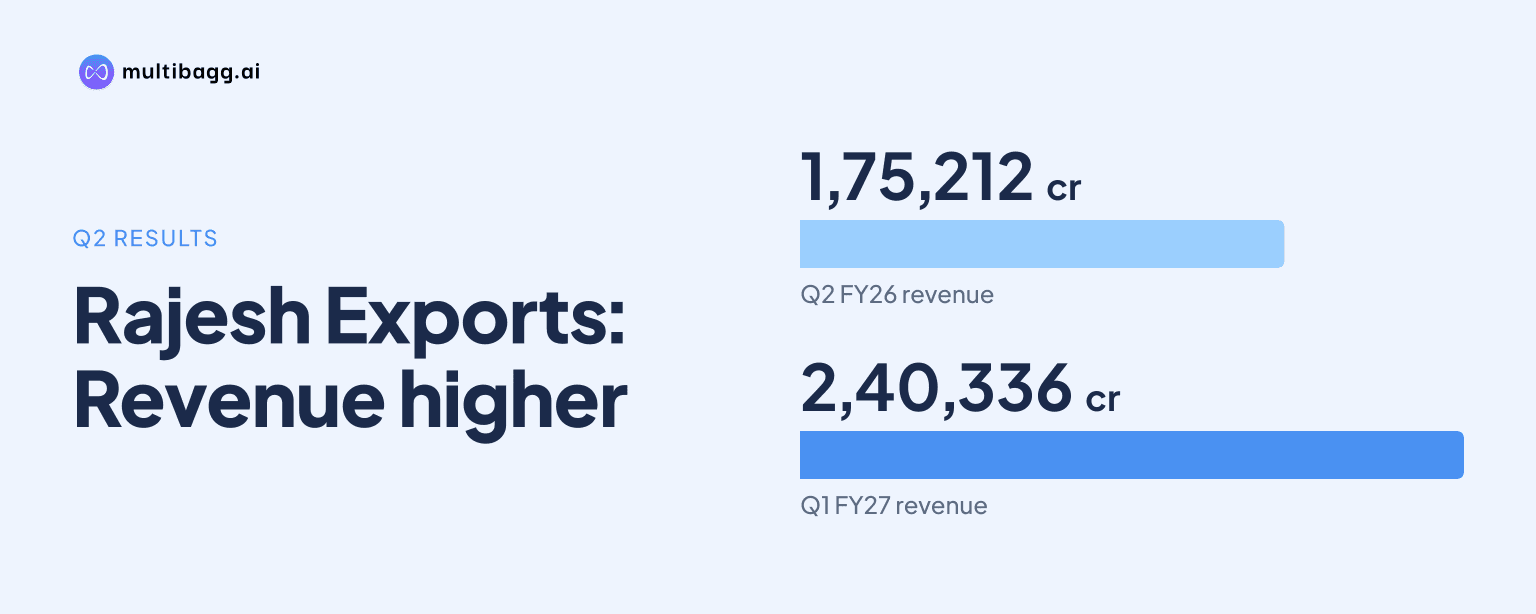
Rajesh Exports Ltd. is scheduled to consider its Q2 FY27 unaudited results on November 14, 2026, following Q1 FY27 revenue of ₹2,40,336 crore and net profit of ₹47 crore. The meeting matters because the September-quarter filing will provide the next formal update on the company's financial performance and disclosures.
Know Rajesh Exports inside out
Results, valuation, peers and who's buying, in one view.
When will Rajesh Exports announce Q2 FY27 results?
Rajesh Exports Ltd. has informed the exchanges that its Board of Directors will meet on Saturday, November 14, 2026, at the registered office in Bengaluru. The stated agenda is to consider and take on record the unaudited financial results for the quarter ended September 30, 2026.
The company filed the board-meeting intimation on November 12. At the time of the notice, it had not disclosed revenue, operating profit, net profit, margins, or any other financial figures for the July-September period. The board meeting is therefore a procedural step before the public release of the quarterly accounts.
The Q2 FY27 period covers July 1, 2026 to September 30, 2026. Under the timeline cited in the source material, listed companies are required to publish September-quarter results within 45 days of the quarter end, placing November 14 as the outer reporting deadline.
What financial base will Rajesh Exports face in Q2 FY27?
Rajesh Exports will report Q2 FY27 against revenue of ₹1,75,212 crore and net profit of ₹104 crore reported for Q2 FY26, according to the supplied results preview. These are the key year-on-year comparison figures for investors assessing the September-quarter filing.
The company's immediately preceding quarter reported revenue of ₹2,40,336 crore in Q1 FY27, up 82.71% from ₹1,31,542 crore in Q1 FY26. Q1 FY27 net profit was ₹47 crore, compared with a net loss of ₹10 crore in the year-earlier quarter.
The source does not provide a verified analyst revenue or profit estimate for Q2 FY27. As a result, no numerical earnings expectation can be treated as confirmed before Rajesh Exports files its unaudited results and accompanying notes to accounts.
What has Rajesh Exports disclosed about its reporting schedule?
Rajesh Exports has historically filed results between 45 and 139 days after the relevant quarter ended, based on the seven quarters cited in the source material. Its July-September results were filed on November 14 in both 2024 and 2025.
That history makes the November 14, 2026 board meeting consistent with the timing of the company's two previous September-quarter disclosures. However, the timing pattern does not indicate what the financial outcome will be, as the current notice contains no performance guidance or operating commentary.
Rajesh Exports was incorporated in 1989 and is described in the source as a manufacturer of gold and gold products. Its operations span refining through its Swiss subsidiary Valcambi SA, bullion trading, jewellery manufacturing and wholesale activity, as well as retail jewellery showrooms in Karnataka.
Got a follow-up? Ask IRIS
Why are regulatory disclosures relevant to Rajesh Exports investors?
Regulatory disclosures are relevant because Sebi has confirmed interim restrictions on Rajesh Exports and its promoter, Rajesh Mehta, over allegations of financial misrepresentation and fund routing. The source states that the regulator identified issues around reported consolidated revenue of ₹15,40,000 crore.
The same source says that revenue reported by subsidiary Valcambi SA was ₹3,027.3 crore, and that Sebi found the company and promoter had not adequately rebutted its preliminary findings despite opportunities to respond. These are regulatory allegations and findings described in the supplied material, not a new financial result.
The Q2 filing may therefore be assessed not only for revenue and profit but also for the accounting notes, exceptional items, related disclosures and any company communication attached to the results. The November 14 notice itself does not provide an update on the regulatory matter.
How does the Q2 filing affect Rajesh Exports shareholders?
For shareholders, the filing will establish the reported financial performance for the September quarter and allow comparison with the ₹1,75,212 crore revenue and ₹104 crore profit base from Q2 FY26. The immediate information gap is substantial because no Q2 FY27 figures were included in the board-meeting announcement.
The Q1 FY27 figures also show that revenue growth and profit movement did not move in the same proportion: revenue increased 82.71% year-on-year, while net profit was ₹47 crore. Investors will be able to review the September results for changes in profitability alongside sales and operating profit disclosures.
The board meeting does not by itself confirm a dividend, capital allocation decision, or outlook. The source mentions no dividend proposal or management forecast for Q2 FY27, so such matters cannot be inferred from the results-meeting intimation.
Conclusion
Rajesh Exports Ltd. will consider its Q2 FY27 unaudited financial results on November 14, 2026, with the September-quarter outcome to be measured against ₹1,75,212 crore revenue and ₹104 crore profit in Q2 FY26. The announcement is significant because it will provide the next reported financial update after Q1 FY27 revenue of ₹2,40,336 crore and profit of ₹47 crore.
The key item to watch is the formal exchange filing after the board meeting, including revenue, operating profit, net profit and notes to accounts. Investors may also monitor whether the company provides any additional disclosure related to the Sebi matter, as the present meeting notice is limited to approval of unaudited quarterly results.