










Refex auditor cites material doubt after net worth erosion
Key highlights
- Refex’s auditor said fully eroded net worth at September 30, 2026 created material going-concern uncertainty.
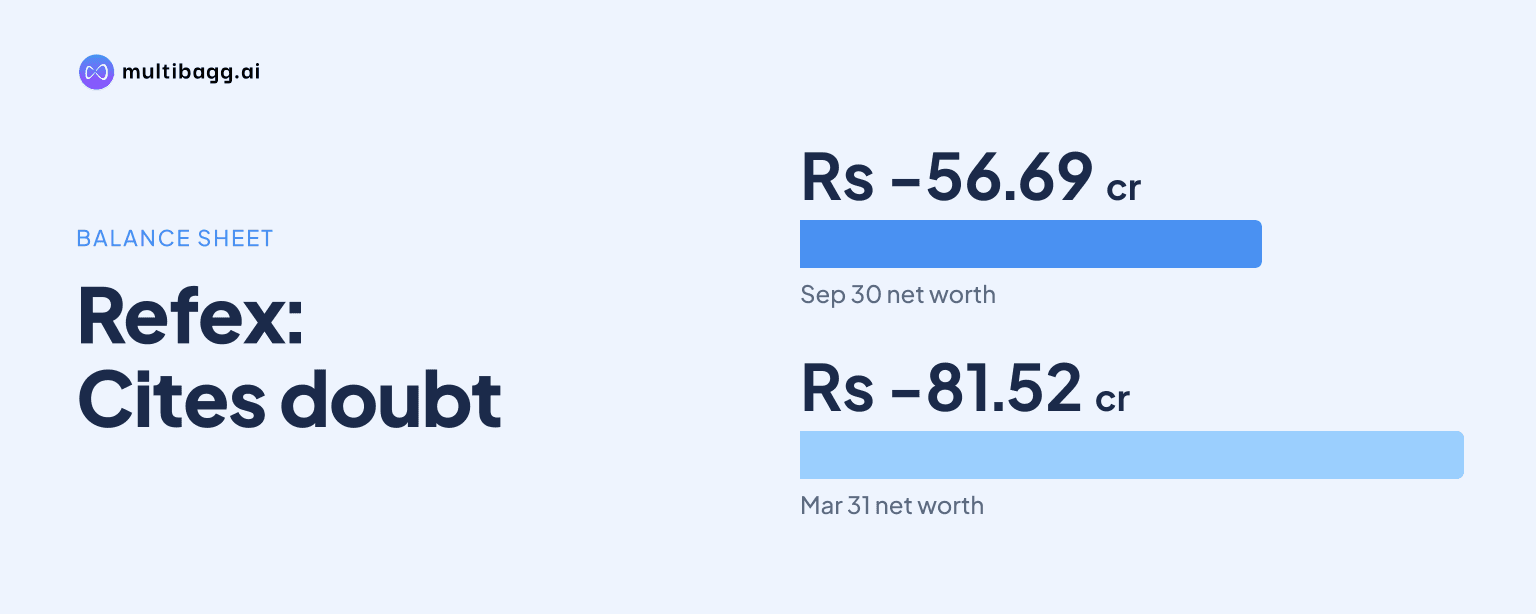
- Refex reported total equity of negative Rs 56.69 crore at September 30, 2026, compared with negative Rs 81.52 crore at March 31, 2026.
- Refex reported Rs 23.73 crore September-quarter profit after tax, including Rs 23.78 crore of exceptional items.
- Refex plans a preferential equity issue of up to Rs 16.2 crore and disclosed two 80 megawatt wind projects with 25-year power purchase agreements.
powered by IRIS
Refex Renewables & Infrastructure Limited’s auditor said the group’s fully eroded net worth at September 30, 2026 created a material uncertainty that may cast significant doubt on its ability to continue as a going concern, despite reporting Rs 23.73 crore profit after tax for the quarter ended that date.
Know Refex Renewables & Infrastructure inside out
Results, valuation, peers and who's buying, in one view.
Why did Refex’s auditor cite a going-concern uncertainty?
Refex’s auditor cited a going-concern uncertainty because the group’s net worth had been fully eroded as of September 30, 2026. The auditor said that condition, although accompanied by a quarterly profit, indicated a material uncertainty that may cast significant doubt on the group’s ability to continue as a going concern.
The auditor did not modify its review conclusion because of the matter. It said Refex had prepared the September 30, 2026 consolidated results on a going-concern basis, while management had disclosed that the reported asset and liability amounts could require adjustment if the group could not continue as a going concern.
The November 4, 2026 report was a limited review under Standard on Review Engagements 2410, rather than an audit. The auditor said such a review is substantially narrower than an audit and does not provide assurance that all significant matters that an audit might identify would be found.
What does Refex’s balance sheet show about the erosion?
Refex reported total equity of negative Rs 56.69 crore at September 30, 2026, compared with negative Rs 81.52 crore at March 31, 2026. Equity attributable to shareholders was negative Rs 55.46 crore, consisting of Rs 4.5 crore of share capital and negative Rs 59.96 crore of other equity.
The improvement in total equity from March did not change management’s disclosure that accumulated losses had completely eroded net worth. Total assets stood at Rs 541 crore on September 30, while total liabilities were Rs 597.69 crore, with negative equity accounting for the difference between those amounts.
Non-current borrowings increased by Rs 20.94 crore from March 31, 2026 to Rs 474.68 crore at September 30, while current borrowings declined by Rs 19.09 crore to Rs 13.58 crore. Cash and cash equivalents rose by Rs 2.01 crore during the six months ended September 30 to Rs 7.86 crore.
Refex generated Rs 24.98 crore from operating activities in the six months ended September 30, 2026, against Rs 6.27 crore in the comparable 2025 period. Investing activities used Rs 22.5 crore, including Rs 16.12 crore of capital work in progress, while financing activities used Rs 0.47 crore.
How did Refex perform in the September 2026 quarter?
Refex reported Rs 23.73 crore profit after tax for the quarter ended September 30, 2026, compared with a Rs 3.14 crore loss in the June 2026 quarter and a Rs 14.32 crore loss a year earlier. However, the September result included Rs 23.78 crore of exceptional items, while profit before exceptional items and tax was Rs 1.85 crore.
Management said the exceptional item related to write-backs of liabilities and gains on trademark and investment transactions under a restructuring agreement involving Refex, Sherisha Solar LLP, Ishaan Solar Power Private Limited and SILRES Energy Solutions Private Limited. Other income also included Rs 12.67 crore from the disposal of loss-making subsidiaries.
Revenue from operations fell by Rs 5.47 crore quarter on quarter to Rs 16.73 crore in September 2026. Commercial and Industrial revenue declined to Rs 13.89 crore from Rs 17.56 crore, while Compressed Bio Gas revenue fell to Rs 2.78 crore from Rs 4.51 crore.
Compared with the September 2025 quarter, Compressed Bio Gas revenue rose from Rs 1.11 crore to Rs 2.78 crore. Commercial and Industrial revenue increased from Rs 12.99 crore to Rs 13.89 crore over the same period, while the segment result remained negative Rs 3.04 crore in the September 2026 quarter.
Got a follow-up? Ask IRIS
What support does Refex cite for preparing accounts on a going-concern basis?
Refex cited new business opportunities, a proposed preferential equity issue of up to Rs 16.2 crore and a promoter support letter as grounds for preparing its accounts on a going-concern basis. Management said the promoter shareholder’s letter provided relevant and appropriate financial support to enable the company’s business to continue seamlessly.
During the September 2026 quarter, Refex Green Power Limited, a wholly owned subsidiary, secured two 80 megawatt wind-power projects through competitive bidding by Solar Energy Corporation of India Limited and SJVN Limited. Management said each project carries a 25-year power purchase agreement, but the filing did not quantify project revenue, commissioning dates or capital expenditure.
Refex also changed its group structure on August 14, 2026 by transferring its entire holding in Ishaan Solar Power Private Limited to SILRES for Rs 3.93 crore. Because Ishaan Solar held the entire share capital of SEI Tejas Private Limited, both entities ceased to be wholly owned subsidiaries from that date.
Refex Green Power also acquired 100% stakes in Refex Vayu SPV 1 Private Limited and Refex Vayu SPV 3 Private Limited, plus a 49% stake in Refex Vayu SPV 2 Private Limited. The first two became step-down subsidiaries, while Refex Vayu SPV 2 became an associate.
What unresolved operating matter could affect Refex?
Refex disclosed that operations at the compressed biogas plant of Refex CBG Kolhapur Limited in Kodoli, Kolhapur, had been severely affected by restricted access and utilities. The restrictions were imposed by Warana Sugar Limited in relation to alleged dues of Rs 18.48 crore, which the subsidiary disputes.
Refex CBG Kolhapur said the dues had been fully settled when it acquired the plant in August 2025, while Warana Sugar has taken a different position. Both parties have initiated legal proceedings, and the auditor said the matter was sub judice as of the November 4, 2026 review report.
Management said it could not presently quantify the financial implications of the dispute, including the effect of the potential cessation of plant operations. The plant is part of Refex’s Compressed Bio Gas segment, which generated Rs 2.78 crore of revenue in the September 2026 quarter.
Conclusion
The auditor’s going-concern statement places Refex’s Rs 23.73 crore September-quarter profit in the context of negative Rs 56.69 crore total equity and fully eroded net worth. The quarterly profit was supported by Rs 23.78 crore of exceptional items, while revenue fell to Rs 16.73 crore from Rs 22.2 crore in the preceding quarter.
The next disclosed developments to watch are completion terms for the proposed Rs 16.2 crore preferential equity issue, delivery of the two 80 megawatt wind projects with 25-year power purchase agreements, and the legal dispute affecting the Kodoli compressed biogas plant. Management has not quantified the financial effect of the plant disruption or the future contribution of the wind projects.