










Repono Limited deployed Rs 18.56465 crore of IPO funds by September
Key highlights
- Repono expensed Rs 18.56465 crore from projected IPO utilisation of Rs 26.68032 crore by September 30, 2026.
- Repono held Rs 8.11567 crore of IPO proceeds in bank FDRs, including Rs 4.773 crore earmarked for equipment.
- Repono spent Rs 9.07265 crore on working capital and Rs 6.67 crore on general corporate purposes.
- Repono reported no deviations or variations from the IPO objects stated in its offer document.
powered by IRIS
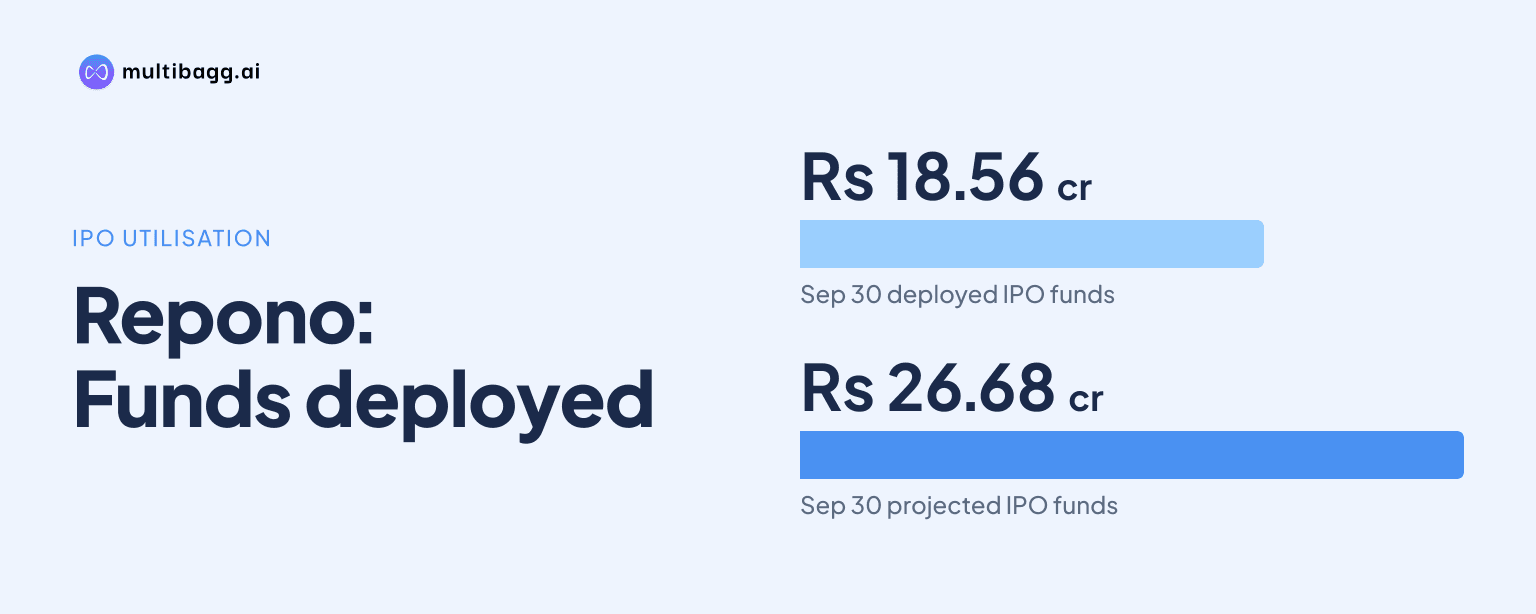
Repono expensed Rs 18.56465 crore of its Rs 26.68032 crore projected initial public offering utilisation by September 30, 2026, while Rs 8.11567 crore was held in bank fixed deposits. The fund-utilisation certificate records expenditure on equipment, warehouse packing systems, warehouse-management software, working capital and general corporate purposes, with no reported deviation from the offer-document objects.
Know Repono inside out
Results, valuation, peers and who's buying, in one view.
How much of Repono's IPO money had been used by September?
Repono had expensed Rs 18.56465 crore, or about 69.6% of the Rs 26.68032 crore projected IPO utilisation, as of September 30, 2026. The certificate separately shows Rs 8.11567 crore in bank fixed deposits, shown as FDRs, and the two amounts total the projected utilisation. The unutilised bank-balance column contains no reported amount.
The certificate for the period ended September 30, 2026 was addressed to Repono's board and Wealth Mine Networks Private Limited and issued by V S Bapna & Associates, Chartered Accountant. It confirms that the IPO funds had been used in accordance with the offer-document objects and that there were no deviations or variations. The certificate does not state that every project was completed by September 30, 2026.
The Rs 18.56465 crore expensed amount was concentrated in working capital and general corporate purposes. Working capital accounted for Rs 9.07265 crore, while general corporate purposes accounted for Rs 6.67 crore. Together, the two objects represented Rs 15.74265 crore of spending, leaving Rs 2.822 crore expensed on equipment and software-related objects.
Which Repono IPO objects received the most spending?
Repono spent the most on working-capital requirements, expensing Rs 9.07265 crore against a projected allocation of Rs 10.11432 crore by September 30, 2026. The remaining Rs 1.04167 crore for that object was reported as FDRs with a bank. The working-capital spending was higher than the expenditure recorded for equipment, packing systems and software.
The allocation for forklifts, hand pallet trolleys and reach stackers was Rs 7.241 crore, of which Rs 2.468 crore had been expensed and Rs 4.773 crore remained in FDRs. Repono's certificate identifies the equipment categories, but it does not disclose the number of units acquired, suppliers, locations or commissioning dates. That prevents a comparison of the spending with physical deployment milestones.
For warehouse-management software, Repono expensed Rs 35.40 lakh from a Rs 1.0502 crore allocation and held Rs 69.62 lakh in FDRs. In contrast, no expense was reported against the Rs 1.6048 crore warehouse packing-system allocation, with the entire amount shown in FDRs. The filing does not specify whether the packing-system project had begun or provide a deployment timetable.
General corporate purposes was the only listed object that was fully expensed by the reporting date. Repono recorded Rs 6.67 crore of expense against the Rs 6.67 crore projected allocation, with no amount reported in FDRs. The utilisation certificate does not provide a line-item breakdown of the expenditure included under general corporate purposes.
Why were Rs 8.11567 crore of IPO proceeds in FDRs?
Repono held Rs 8.11567 crore in bank FDRs because the certificate classified unexpensed amounts for four specified IPO objects as “FDR with Bank” on September 30, 2026. Equipment represented Rs 4.773 crore of that balance, the largest portion, followed by Rs 1.6048 crore allocated to the warehouse packing system. The certificate does not disclose the banks, deposit maturities, interest rates or a release schedule.
Working capital accounted for Rs 1.04167 crore of FDRs and warehouse-management software accounted for Rs 69.62 lakh. This object-wise presentation means the FDR balance was assigned to stated uses rather than presented simply as an unallocated residual. The blank unutilised bank-balance field does not have an explanatory note in the certificate.
The FDR disclosure is distinct from Repono's consolidated cash and cash equivalents. Its September 30, 2026 balance sheet reported cash and cash equivalents of Rs 10.03 lakh, down from Rs 12.62 lakh on March 31, 2026. The certificate does not reconcile the object-wise FDR amounts with the cash-and-cash-equivalents line in the consolidated balance sheet.
Got a follow-up? Ask IRIS
What do Repono's September financial statements show alongside the certificate?
Repono reported capital work in progress of Rs 23.7941 crore on September 30, 2026, compared with Rs 3.789 crore on March 31, 2026. Property, plant and equipment declined to Rs 12.1903 crore from Rs 13.1925 crore over the same period, while intangible assets declined to Rs 31.30 lakh from Rs 35.95 lakh. These movements provide context on capital activity but are not a direct reconciliation to IPO-object spending.
For the period ended September 30, 2026, Repono's consolidated cash-flow statement recorded Rs 20.058 crore of capital expenditure on fixed assets, including capital advances. The same statement reported Rs 10.1415 crore from investment or redemption in fixed deposits. The filing does not identify what share of either consolidated cash-flow line arose from IPO proceeds, so the fund-utilisation certificate remains the specific object-wise disclosure.
Repono reported revenue from operations of Rs 35.4162 crore and profit after tax of Rs 2.0477 crore for the period ended September 30, 2026. The provided comparator is the full year ended March 31, 2026, when revenue was Rs 65.2668 crore and profit after tax was Rs 6.5782 crore, making the periods not directly comparable. The board approved the unaudited September-period financial results on November 13, 2026.
Does Repono report a deviation from its IPO-use plan?
Repono reported no deviations or variations in the utilisation of IPO proceeds from the objects stated in its offer document as of September 30, 2026. V S Bapna & Associates made that confirmation in the fund-utilisation certificate covering the Rs 26.68032 crore projected utilisation. The certificate therefore presents the Rs 18.56465 crore expensed and Rs 8.11567 crore in FDRs as being within the stated uses.
The absence of a reported deviation does not add project-level operating detail beyond the five stated objects. For example, the Rs 1.6048 crore packing-system allocation remained wholly in FDRs, and the Rs 4.773 crore equipment FDR balance exceeded the Rs 2.468 crore expensed on equipment. The certificate does not set target completion dates for those objects or state when the deposits will be used.
Conclusion
Repono's certificate shows that IPO deployment by September 30, 2026 was led by working capital and general corporate purposes, which together absorbed Rs 15.74265 crore of the Rs 18.56465 crore expensed. The remaining Rs 8.11567 crore was held in FDRs and was largely assigned to equipment and warehouse packing-system allocations, while the certificate reported no departure from the offer-document objects.
The next disclosure to watch is whether Repono records expenditure against the Rs 4.773 crore equipment, Rs 1.6048 crore warehouse packing-system and Rs 69.62 lakh software FDR balances. The September 30, 2026 certificate provides no timetable for deployment, project completion, deposit maturity or release of those balances.