










SCI reports Rs 112.62 crore LNG venture loss, concern flagged
Key highlights
- SCI recorded a Rs 112.62 crore share of loss from four LNG joint ventures in the half year ended September 30, 2026.
- SCI’s joint-venture share was a Rs 24.48 crore profit in the half year ended September 30, 2025.
- Auditors cited material going-concern uncertainty at ILT 1, ILT 2 and ILT 3.
- SCI’s non-current loans declined to Rs 26.66 crore at September 30, 2026 from Rs 249.20 crore at March 31, 2026.
powered by IRIS
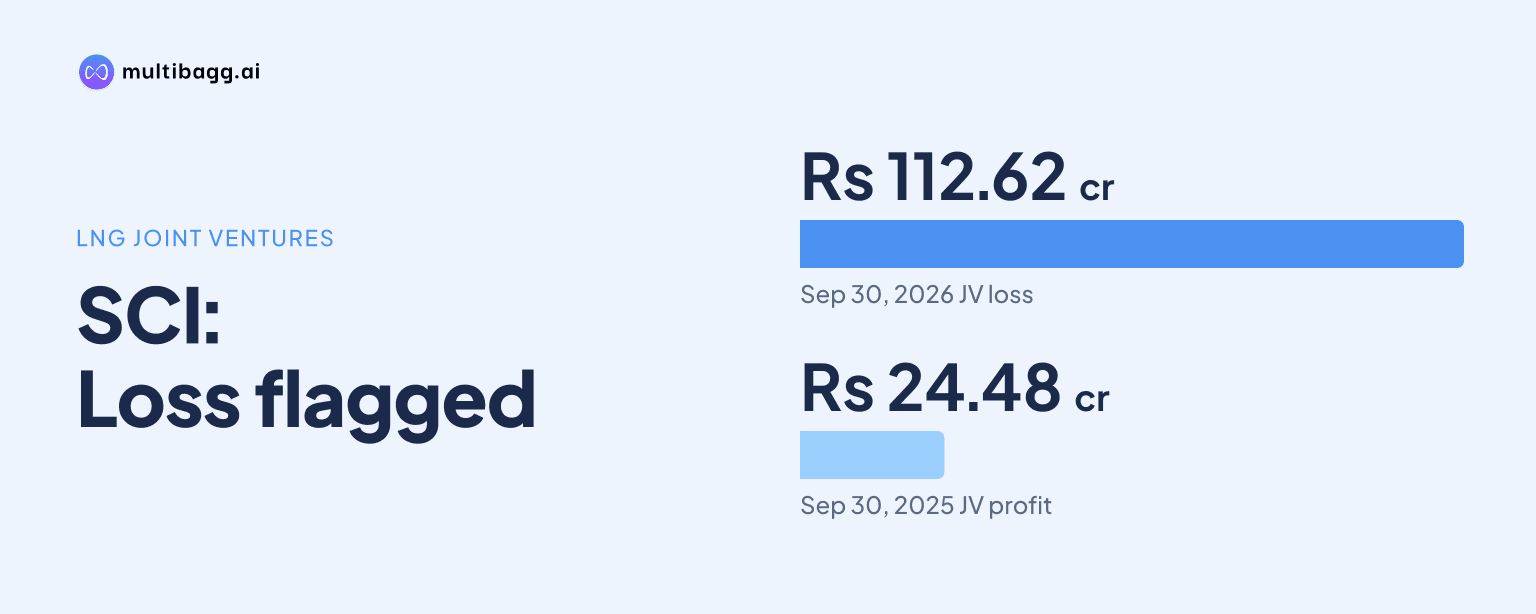
The Shipping Corporation of India Limited recorded a Rs 112.62 crore share of net loss from four LNG joint ventures in the half year ended September 30, 2026, reversing a Rs 24.48 crore profit a year earlier, while the ventures’ auditors reported material going-concern uncertainty at ILT 1, ILT 2 and ILT 3.
Know Shipping Corporation of India inside out
Results, valuation, peers and who's buying, in one view.
What did SCI report from its LNG joint ventures?
SCI reported a Rs 112.62 crore share of net loss from its four LNG joint ventures for the half year ended September 30, 2026. The ventures are India LNG Transport Co. No.1 Ltd. (ILT 1), India LNG Transport Co. No.2 Ltd. (ILT 2), India LNG Transport Co. No.3 Ltd. (ILT 3) and India LNG Transport Co. No.4 Pvt. Ltd. (ILT 4), whose results SCI includes through the equity method.
The half-year loss compared with a Rs 24.48 crore share of profit from associates and joint ventures in the half year ended September 30, 2025. In the September 2026 quarter, SCI recorded a Rs 67.58 crore share of loss, following a Rs 45.04 crore loss in the June 2026 quarter and contrasting with a Rs 13.38 crore profit in the September 2025 quarter.
SCI’s share of total comprehensive income from the ventures was negative Rs 49.07 crore in the September quarter and negative Rs 91.78 crore for the half year. The Rs 20.84 crore half-year other comprehensive income did not offset the Rs 112.62 crore net loss.
Why did auditors flag going-concern uncertainty at SCI ventures?
SCI’s auditors said the auditors of ILT 1, ILT 2 and ILT 3 had included a material-uncertainty paragraph on going concern in their respective independent review reports. The disclosure appeared in the November 4, 2026 limited-review report for SCI’s unaudited consolidated results for the quarter and half year ended September 30, 2026.
The supplied filing does not state the financial conditions, borrowings, charter arrangements, counterparties or recovery plans underlying the three going-concern paragraphs. It says the joint ventures’ interim results were reviewed by other auditors, prepared under accounting principles applicable in their respective countries, and then converted to Indian Accounting Standards, or Ind AS, for consolidation.
SCI’s statutory auditors also said the joint ventures were not material at the consolidated level and did not modify their review conclusion. They reported that nothing had come to their attention to indicate that SCI’s consolidated statement for September 30, 2026 failed to meet applicable Ind AS recognition, measurement and disclosure requirements.
Did SCI disclose a Rs 240 crore ILT 3 provision?
No, the supplied filing does not disclose a Rs 240 crore provision against an ILT 3 loan. It also does not attribute an impairment, provision or joint-venture loss to Middle East developments, despite identifying ILT 3 as one of the ventures with a material going-concern uncertainty paragraph.
SCI reported non-current loans of Rs 26.66 crore at September 30, 2026, compared with Rs 249.20 crore at March 31, 2026. The Rs 222.54 crore reduction is not explained by borrower, and the filing does not say whether any loan related to ILT 3 or whether the movement reflected repayment, settlement, reclassification or provisioning.
Investments accounted for using the equity method fell to Rs 589.96 crore at September 30, 2026 from Rs 681.74 crore at March 31, 2026. The Rs 91.78 crore decline matches SCI’s negative half-year share of total comprehensive income from associates and joint ventures, but the filing does not allocate that movement among ILT 1, ILT 2, ILT 3 and ILT 4.
Got a follow-up? Ask IRIS
How did the joint-venture loss affect SCI profit?
The Rs 112.62 crore joint-venture loss reduced SCI’s half-year profit before tax to Rs 1,215.41 crore from Rs 1,328.03 crore before the equity-method share. In the corresponding half year of 2025, SCI had reported Rs 555.80 crore before that share and a Rs 24.48 crore positive contribution from associates and joint ventures, resulting in Rs 580.28 crore of profit before tax.
For the September 2026 quarter, SCI’s profit before tax was Rs 587.10 crore after the Rs 67.58 crore joint-venture loss, compared with Rs 654.68 crore before that item. Consolidated profit after tax was Rs 577.76 crore for the quarter and Rs 1,197.10 crore for the half year, versus Rs 189.16 crore and Rs 543.33 crore respectively a year earlier.
The tanker segment generated Rs 2,877.61 crore of half-year revenue, the largest of SCI’s operating segments, and Rs 1,266.63 crore of profit before interest and tax. A year earlier, tanker revenue was Rs 1,770.86 crore and its profit before interest and tax was Rs 424.80 crore, while the joint ventures moved from a Rs 24.48 crore half-year profit to a Rs 112.62 crore loss.
SCI’s consolidated total assets were Rs 14,367.38 crore at September 30, 2026, up from Rs 13,318.50 crore at March 31, 2026. Total equity rose to Rs 10,304.92 crore from Rs 9,096.29 crore, while total liabilities fell to Rs 4,062.46 crore from Rs 4,222.21 crore; these balances do not provide separate liquidity or debt data for the four ventures.
What remains undisclosed about SCI’s LNG ventures?
SCI has not disclosed the individual results or financial positions of ILT 1, ILT 2, ILT 3 and ILT 4 in the supplied filing. The Rs 112.62 crore aggregate half-year loss is not split by venture, and there are no disclosed figures for their revenue, assets, liabilities, debt maturities, vessel operations or charter commitments.
The filing was signed on November 4, 2026 and compares the September 2026 period with June 2026, September 2025 and the year ended March 31, 2026. It says earlier figures were regrouped or rearranged where necessary or practicable for presentation, but provides no restatement or venture-specific explanation for the shift from a Rs 24.48 crore half-year profit to a Rs 112.62 crore loss.
Conclusion
SCI’s consolidated results show that its LNG joint ventures changed from a Rs 24.48 crore share of profit in the September 2025 half year to a Rs 112.62 crore loss in the September 2026 half year. That reversal reduced reported profit before tax even as tanker segment profit before interest and tax increased to Rs 1,266.63 crore from Rs 424.80 crore.
The next disclosure to watch is whether SCI provides venture-level data on ILT 1 through ILT 4, including the circumstances behind the going-concern uncertainty at ILT 1, ILT 2 and ILT 3. The supplied filing also leaves unresolved the borrower-level explanation for the fall in SCI’s non-current loans from Rs 249.20 crore at March 31, 2026 to Rs 26.66 crore at September 30, 2026.