










Shanthala FMCG leaves Rs 5.44 crore IPO funds unutilised
Key highlights
- Shanthala FMCG had Rs 5.44 crore of IPO proceeds unutilised at September 30, 2026.
- Shanthala FMCG used Rs 6.06 crore of the Rs 11.50 crore allocated for additional working-capital funding.
- Shanthala FMCG fully utilised the Rs 4.57 crore earmarked for corporate IPO general purposes, including apportioned expenses.
- The Rs 5.44 crore unused balance was held in short-term deposits and bank balances.
powered by IRIS
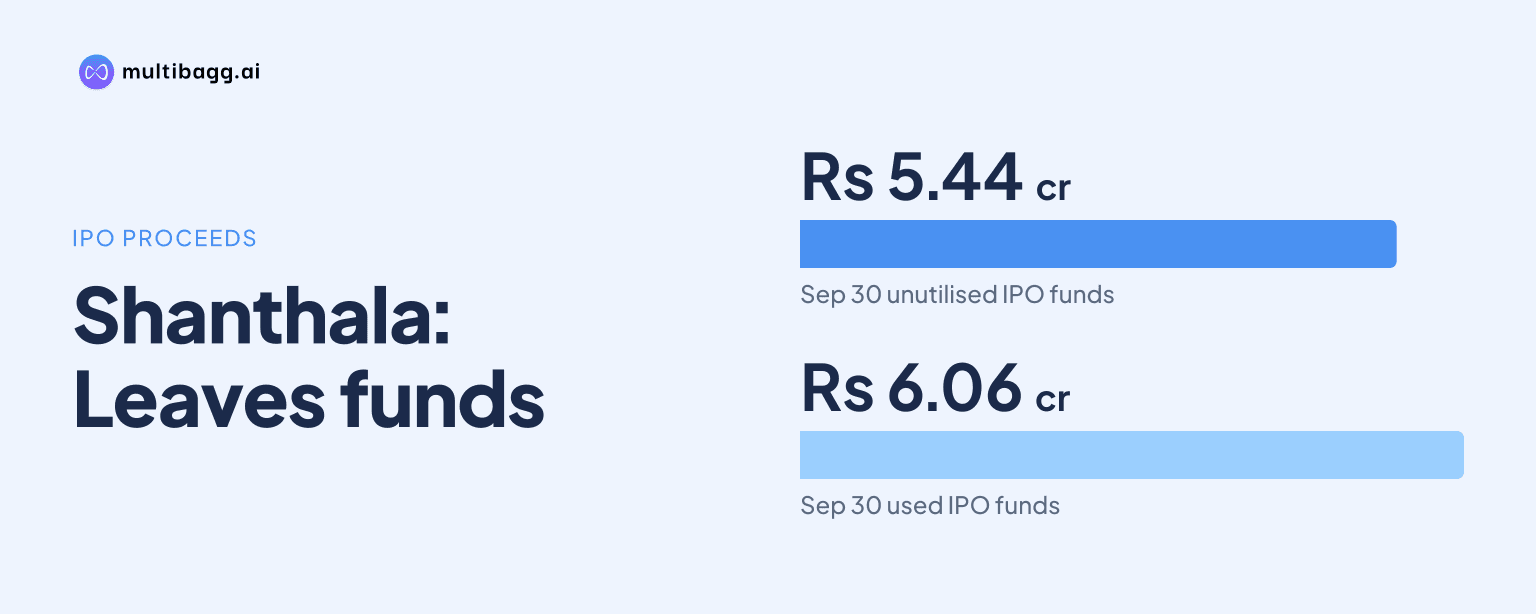
Shanthala FMCG Products Limited had Rs 5.44 crore of initial public offering, or IPO, proceeds unutilised at September 30, 2026, after applying Rs 6.06 crore of its Rs 11.50 crore allocation for additional working-capital funding. The balance was held in short-term deposits and bank balances, according to the utilisation certificate dated November 14, 2026.
Know Shanthala FMCG Products inside out
Results, valuation, peers and who's buying, in one view.
How much of Shanthala FMCG’s IPO proceeds remained unutilised?
Shanthala FMCG had Rs 5.44 crore of unutilised IPO proceeds at September 30, 2026, equal to the remaining balance from disclosed IPO uses of Rs 16.07 crore. The certificate records total utilisation of Rs 10.64 crore, meaning proceeds had been only partially applied by that reporting date.
The unutilised balance represented about 34% of the Rs 16.07 crore total disclosed uses, based on the certificate’s figures. Of the Rs 10.64 crore applied, Rs 6.06 crore went to additional working-capital funding and Rs 4.57 crore to corporate IPO general purposes, including apportioned expenses.
The certificate covers the period ending September 30, 2026 and was issued by Kale Malde & Co. on November 14, 2026. It states that Shanthala FMCG had partially applied IPO proceeds for the purposes disclosed in its offer document.
Which IPO objective accounts for Shanthala FMCG’s unused balance?
Additional working-capital funding accounts for all of Shanthala FMCG’s Rs 5.44 crore unutilised balance. The company had allocated Rs 11.50 crore to that purpose and utilised Rs 6.06 crore by September 30, 2026.
This means roughly 53% of the working-capital allocation had been used, while about 47% remained available at the reporting date. By contrast, Shanthala FMCG reported no residual amount under the Rs 4.57 crore corporate IPO general-purpose allocation.
The certificate separates the two stated IPO objects rather than treating the proceeds as one pooled balance. It lists additional capital funding for working requirements and corporate IPO general purposes, including apportioned expenses, with no third use category shown in Annexure A.
The filing does not specify which working-capital items received the Rs 6.06 crore already applied by September 30, 2026. It also does not give a deadline, deployment schedule or itemised plan for applying the remaining Rs 5.44 crore.
Where was Shanthala FMCG holding its unutilised IPO money?
Shanthala FMCG held the Rs 5.44 crore unutilised IPO balance in short-term deposits and bank balances as of September 30, 2026. Kale Malde & Co. stated that those balances were reflected in the company’s financial statements.
The certificate does not provide a division of the Rs 5.44 crore between deposits and bank balances. It also does not disclose deposit maturities, interest rates, banking counterparties or the dates on which funds may be moved into working-capital use.
Shanthala FMCG’s unaudited consolidated cash-flow statement showed cash and cash equivalents of Rs 11.57 lakh at September 30, 2026, against Rs 3.00 crore at March 31, 2026. That line is not a direct reconciliation to the Rs 5.44 crore IPO balance because the certificate refers to both short-term deposits and bank balances, while the cash-flow statement uses the separate classification of cash and cash equivalents.
For the half year ended September 30, 2026, Shanthala FMCG reported Rs 2.13 crore of net cash used in operating activities and Rs 1.05 crore of net cash used in financing activities. It reported Rs 30.09 lakh of cash generated from investing activities, consisting of interest received, but the filing does not link those movements to specific IPO-proceeds accounts.
Got a follow-up? Ask IRIS
What assurance does Shanthala FMCG’s utilisation certificate provide?
Kale Malde & Co. said it examined Shanthala FMCG’s books of account and relevant records and documents connected with IPO-fund utilisation. The firm’s certificate says the work was performed under the Institute of Chartered Accountants of India Guidance Note on Reports or Certificates for Special Purposes, revised in 2016.
The firm said its role was to provide reasonable assurance that the utilisation statement agreed with books of account maintained by Shanthala FMCG. The certificate, dated November 14, 2026, carries UDIN 26138034AFGOJA5553 and refers to IPO proceeds raised for the stated objects in the offer document.
The document limits its stated use to verification of statutory records and books of account for IPO utilisation aligned with purposes disclosed in the prospectus. It says the certificate is intended for submission to the National Stock Exchange, or NSE, and should not be used for another purpose or by another person without prior written consent.
Shanthala FMCG’s unaudited consolidated results for the half year ended September 30, 2026 were also reviewed by its statutory auditors, whose qualified review report was taken on record by the board on November 14, 2026. The IPO-utilisation certificate does not state that the qualified review changes the Rs 5.44 crore unutilised balance.
How does the IPO balance compare with Shanthala FMCG’s other disclosures?
Shanthala FMCG had fully deployed its Rs 4.57 crore general-purpose allocation but had applied only Rs 6.06 crore of the Rs 11.50 crore working-capital allocation at September 30, 2026. The difference between those two utilisation rates explains why the whole Rs 5.44 crore residual amount relates to working capital.
The financial-results notes describe Shanthala FMCG as primarily engaged in marketing and distribution of fast-moving consumer goods, or FMCG, and treat this as a single reportable business segment. The filing does not provide a segment-level schedule that traces the Rs 6.06 crore of utilised working-capital proceeds through inventory, receivables, suppliers or other operating items.
The same notes refer to a forensic audit and investigation report dated October 9, 2026. They state that Rs 33.57 lakh collected in cash from customers during the half year ended September 30, 2026 was not deposited in company bank accounts and was recognised as recoverable from the chief financial officer under a board resolution.
Shanthala FMCG also recognised an impairment loss of Rs 33.57 lakh under exceptional items in its unaudited standalone statement of profit and loss for the half year. The auditors said they lacked sufficient appropriate evidence on recoverability of that amount, but the IPO-utilisation certificate does not connect this matter with the Rs 5.44 crore of unutilised proceeds.
Conclusion
Shanthala FMCG had applied Rs 10.64 crore of Rs 16.07 crore in disclosed IPO uses by September 30, 2026, leaving Rs 5.44 crore unutilised. The residual amount was entirely within the additional working-capital allocation, while corporate IPO general purposes, including apportioned expenses, had been fully funded and used.
The next disclosure to watch is whether Shanthala FMCG reports further use of the Rs 5.44 crore toward the working-capital purpose in its offer document. The November 14, 2026 certificate gives no completion target or deployment schedule, while confirming that the balance was held in short-term deposits and bank balances at September 30, 2026.