










Shriram Properties Q2 EBITDA rises 235% as revenue grows
Key highlights
- Shriram Properties reported Q2 FY27 EBITDA of Rs 62.4 crore, up 235% from Rs 18.6 crore.
- SPL's Q2 FY27 total revenue rose 19% to Rs 272.3 crore while cost of revenues fell 7% to Rs 133.9 crore.
- SPL generated H1 FY27 operating cash flow of Rs 101 crore and ended the period with Rs 357 crore of cash.
- SPL's net debt increased to Rs 761 crore in September 2026 from Rs 432 crore in June 2026 after JV acquisitions.
powered by IRIS
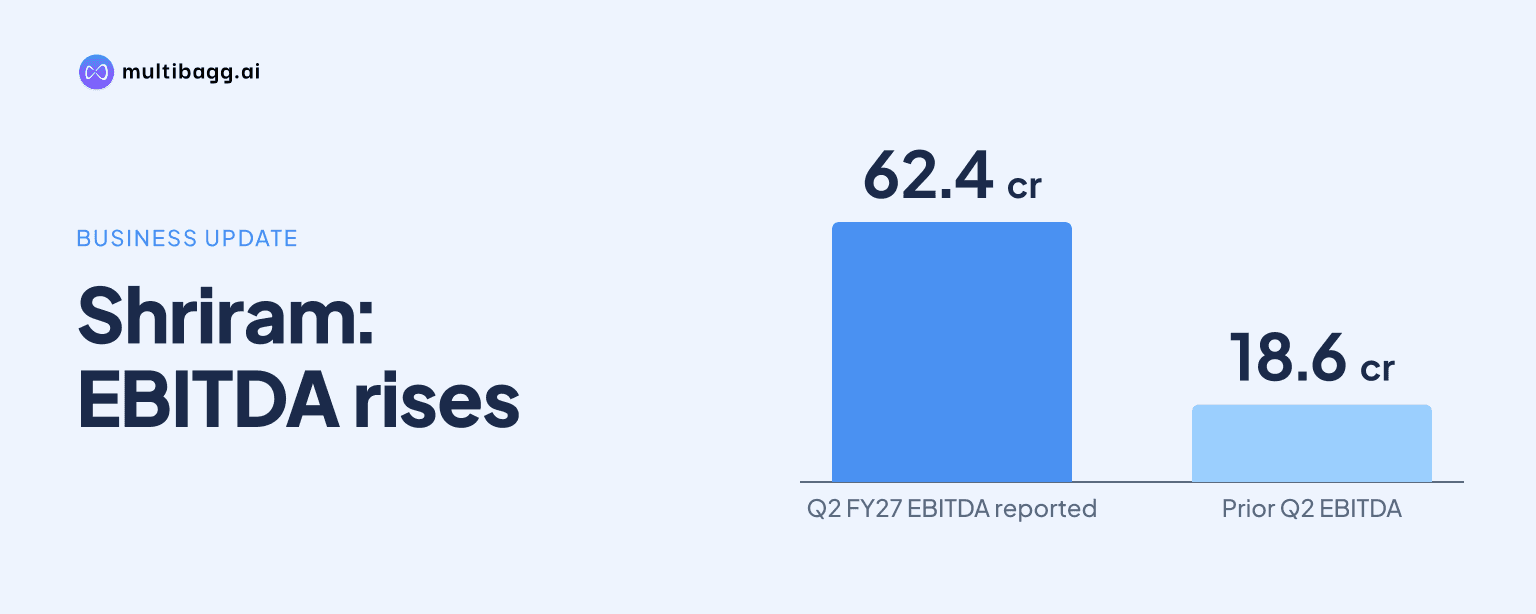
Shriram Properties reported Q2 FY27 EBITDA of Rs 62.4 crore, up 235% from Rs 18.6 crore a year earlier, as total revenue rose 19% to Rs 272.3 crore and cost of revenues fell 7% to Rs 133.9 crore. Handovers from completed and recently completed projects supported operating-revenue growth.
Know Shriram Properties inside out
Results, valuation, peers and who's buying, in one view.
How did SPL's Q2 FY27 EBITDA rise?
SPL's Q2 FY27 EBITDA rose because revenue increased while project-related costs and total expenses did not rise. EBITDA reached Rs 62.4 crore, versus Rs 18.6 crore in Q2 FY26, while total expenses were Rs 209.9 crore compared with Rs 210.4 crore. The company reported EBITDA and profit-before-tax margins of 23% and 10%, respectively, for the quarter.
Operating revenue increased 21% year on year to Rs 266.1 crore in Q2 FY27, and other income was Rs 6.2 crore, taking total revenue to Rs 272.3 crore. Cost of revenues fell by Rs 10 crore to Rs 133.9 crore, employee benefit expense was nearly unchanged at Rs 28.6 crore, and other expenses increased to Rs 47.4 crore from Rs 38 crore.
SPL attributed Q2 operating-revenue growth to handovers carried over from projects completed in FY26 and from recently completed projects. Park 63 and Shankari in Chennai, along with Grand One and Sunshine in Kolkata, contributed the most to Q2 FY27 operating revenue. The company handed over 760 units in Q2 and 1,450 units in H1 FY27.
What happened to SPL's profit after finance costs?
SPL reported Q2 FY27 profit before tax of Rs 29.6 crore and net profit of Rs 21.6 crore, compared with a pre-tax loss of Rs 1.1 crore and net profit of Rs 8.6 crore in Q2 FY26. Finance costs increased 44% to Rs 31.6 crore from Rs 22 crore, partly offsetting the Rs 43.8 crore increase in EBITDA.
Management attributed the higher finance cost to the acquisition of five joint ventures, or JVs, into wholly owned subsidiaries. Interest expense and other finance costs made up the full Rs 31.6 crore in Q2 FY27, while Q2 FY26 included Rs 20.3 crore of interest and Rs 1.7 crore of non-cash unwinding impact linked to Government of West Bengal royalty.
Depreciation was Rs 2.7 crore in Q2 FY27 against Rs 2.4 crore a year earlier, while SPL's share of JV profit declined to Rs 1.5 crore from Rs 4.7 crore. Tax expense was Rs 8 crore, compared with a tax credit of Rs 9.7 crore in Q2 FY26. Net profit nevertheless rose 151% because the operating-profit increase exceeded higher financing, depreciation and tax charges.
How did SPL perform in H1 FY27?
SPL generated H1 FY27 EBITDA of Rs 104.3 crore, up 73% from Rs 60.2 crore in H1 FY26, on total revenue growth of 11% to Rs 543.3 crore. The half-year EBITDA increase was below Q2's 235% rise, but it showed that the cost and handover effects extended beyond a single quarter.
H1 operating revenue was Rs 529.6 crore, up 11% from Rs 475.2 crore, while cost of revenues edged down 1% to Rs 302.2 crore. Total expenses increased 2% to Rs 439.1 crore, including employee benefit expense of Rs 55.5 crore and other expenses of Rs 81.4 crore. Management said cost of revenues, employee expenses and other expenses remained largely stable during the half year.
Profit before tax increased 111% to Rs 43.8 crore from Rs 20.8 crore, while net profit rose 12% to Rs 32.6 crore from Rs 29.2 crore. Finance costs rose 19% to Rs 52.8 crore, and SPL recorded a Rs 2.4 crore share of JV losses after a Rs 9.6 crore share of JV profits in H1 FY26. Management said the loss primarily reflected pre-acquisition marketing costs, which will be consolidated after the JVs' conversion into subsidiaries.
Got a follow-up? Ask IRIS
What do SPL's cash flow and debt figures show?
SPL generated operating cash flow of Rs 101 crore in H1 FY27, compared with Rs 76 crore in H1 FY26, while it invested Rs 105 crore in new projects. Net free cash flow was Rs 184 crore, compared with an outflow of Rs 34 crore a year earlier, and closing cash and cash equivalents were Rs 357 crore.
Operating inflows increased to Rs 505 crore from Rs 485 crore, while operating outflows fell to Rs 404 crore from Rs 409 crore. Construction spending declined to Rs 223 crore from Rs 247 crore, whereas marketing and administrative overheads rose to Rs 126 crore from Rs 115 crore. Q2 FY27 collections were Rs 431 crore, comprising Rs 265 crore from own and joint-development-agreement projects, Rs 108 crore from JVs and Rs 58 crore from development-management projects.
The JV acquisitions increased consolidated gross external debt to Rs 1,118 crore in September 2026 from Rs 651 crore in June 2026. Net debt rose to Rs 761 crore from Rs 432 crore, and net debt to equity increased to 0.51 times from 0.29 times. SPL also reported Rs 245 crore of undrawn limits and a cost of debt of about 11%.
What could support SPL's H2 FY27 profitability?
SPL expects significantly higher H2 handovers to support its full-year target, and management said projects reaching occupancy-certificate stage should add revenue and profitability momentum. The company reported Q2 sales volume of 0.91 million square feet and sales value growth of 20% quarter on quarter, despite limited launches in H1 FY27.
Management disclosed an H2 launch pipeline of nine projects with 5.25 million square feet of supply potential, subject to approvals progressing across regions. SPL also said 8.8 million square feet of business-development additions were progressing and could be added in Q3 or H2, with gross development value of more than Rs 7,500 crore. These are pipeline plans rather than reported revenue or earnings.
Conclusion
SPL's Q2 FY27 profit recovery reflected a 19% rise in total revenue and a 7% decline in cost of revenues, lifting EBITDA to Rs 62.4 crore from Rs 18.6 crore. H1 EBITDA rose 73% to Rs 104.3 crore, while higher finance costs and a shift from JV profits to losses moderated the increase in half-year net profit to 12%.
The next items to watch are the higher H2 handovers flagged by management, the nine projects with 5.25 million square feet of planned launch supply, and the potential 8.8 million square feet of business-development additions. SPL's September 2026 net debt of Rs 761 crore and the consolidation of acquired JVs will also shape subsequent reported financial results.