










SMR Jewels uses Rs 44.68 crore; construction funds remain
Key highlights
- SMR Jewels used Rs 44.68 crore of its Rs 51.20 crore fresh issue by September 30, 2026.
- SMR Jewels fully utilised Rs 30.00 crore for working capital and Rs 6.50 crore for borrowing repayment.
- The Rs 6.40 crore allocation for factory civil construction remained entirely unutilised.
- Total unutilised fresh-issue proceeds stood at Rs 6.52 crore as of September 30, 2026.
powered by IRIS
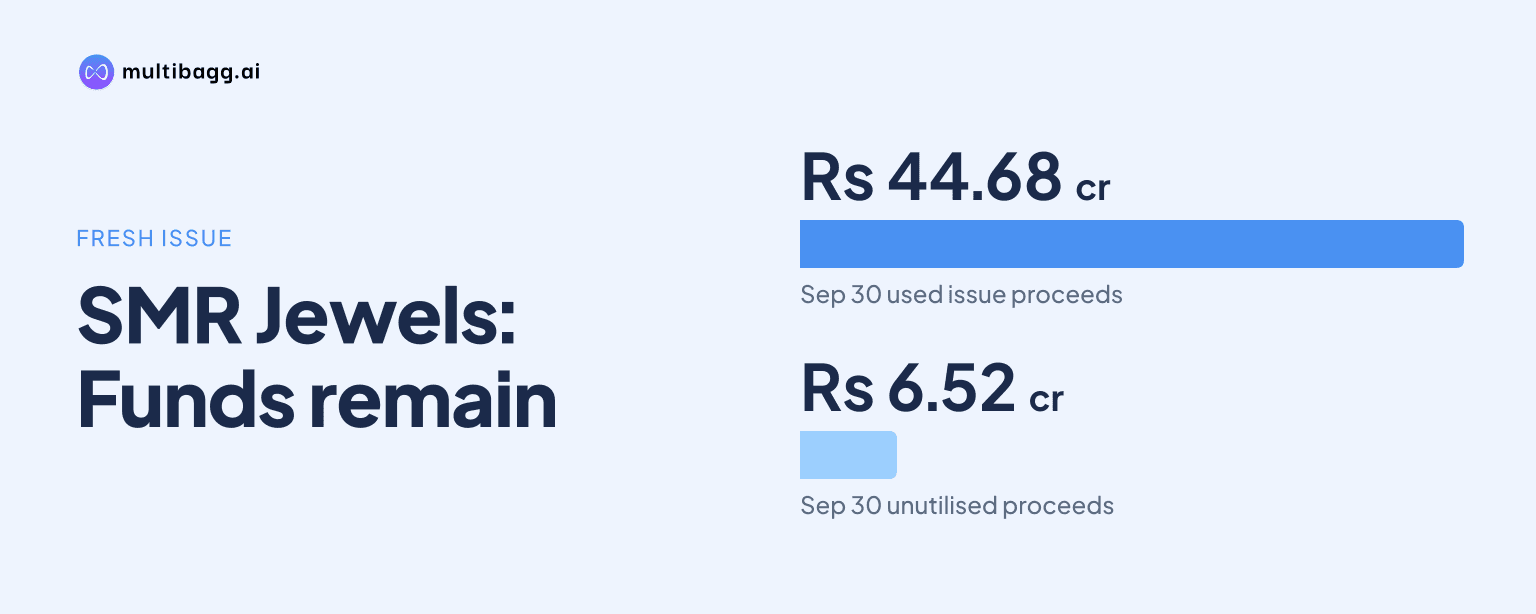
SMR JEWELS Limited deployed Rs 44.68 crore of its Rs 51.20 crore fresh-issue proceeds by September 30, 2026, while the full Rs 6.40 crore allocated for civil construction at its existing factory remained unutilised. The balance of Rs 6.52 crore also included unspent amounts for general corporate purposes and issue expenses.
Know SMR Jewels inside out
Results, valuation, peers and who's buying, in one view.
How much of SMR Jewels’ IPO proceeds had been used?
SMR Jewels had used Rs 44.68 crore of its Rs 51.20 crore fresh issue as of September 30, 2026, leaving Rs 6.52 crore unutilised. The object-wise utilisation certificate dated November 2, 2026 recorded the balance across factory construction, general corporate purposes and issue-related expenses.
The Rs 44.68 crore utilised represented about 87.3% of the Rs 51.20 crore disclosed for fresh-issue objects. The certificate treats money as utilised only when it has actually been deployed for an object set out in the offer document, rather than when it is transferred from the public issue or escrow account to the company’s bank account.
SMR Jewels’ initial public offering, or IPO, comprised 49,80,000 equity shares priced at Rs 128 each, aggregating to Rs 63.744 crore. This included a fresh issue of 40,00,000 shares worth Rs 51.20 crore and an offer for sale of 9,80,000 shares worth Rs 12.544 crore. The shares were allotted on June 4, 2026 and admitted to dealings on the BSE SME platform from June 8, 2026.
How did SMR Jewels use the deployed IPO money?
SMR Jewels fully deployed Rs 30.00 crore for working-capital requirements and Rs 6.50 crore for repayment, in full or in part, of certain outstanding borrowings. Together, those two objects accounted for Rs 36.50 crore of the Rs 44.68 crore used by September 30, 2026.
Working capital was the largest stated use of fresh-issue funds, receiving Rs 30.00 crore, compared with Rs 6.50 crore for borrowings. Both categories had no unutilised amount in the utilisation statement, unlike the factory construction allocation, where the entire disclosed sum was still unused.
SMR Jewels also used Rs 5.00 crore for general corporate purposes against Rs 5.02 crore disclosed for that object. The company deployed Rs 3.1786 crore of the Rs 3.2771 crore allotted for issue-related expenses, leaving Rs 9.85 lakh in that category and Rs 2.29 lakh under general corporate purposes.
The company’s financial results stated that total estimated offer expenses were Rs 4.08 crore. Of this, SMR Jewels was expected to bear Rs 3.2771 crore, while selling shareholders were expected to bear Rs 80.29 lakh. The utilisation certificate records only the company-borne issue-expense allocation among the fresh-issue objects.
Why was SMR Jewels’ factory-construction allocation unused?
SMR Jewels had not deployed any of the Rs 6.40 crore earmarked for capital expenditure towards civil construction work at its existing factory premises as of September 30, 2026. This was the largest component of the Rs 6.52 crore unutilised balance reported in the certificate.
The Rs 6.40 crore construction balance represented about 98.1% of total undrawn fresh-issue funds. The remaining Rs 12.14 lakh comprised Rs 9.85 lakh of issue-related expenses and Rs 2.29 lakh under general corporate purposes, rather than balances in working capital or borrowing repayment.
The filing does not disclose a construction commencement date, a spending timetable, a reason for the lack of deployment, or a revised cost for the civil-work project. It records the construction money as unutilised and does not state that the allocation had been moved to another disclosed object.
The use of the word “actual” in the certificate is material because it separates completed spending from cash movements. Surana Maloo & Co. stated that transfers from the escrow or public issue account to SMR Jewels’ bank account were not counted as utilisation unless the funds were actually deployed toward an offer-document object.
Got a follow-up? Ask IRIS
What does SMR Jewels’ IPO structure mean for the proceeds?
SMR Jewels’ Rs 51.20 crore fresh issue was the part of the IPO designated for the company’s disclosed objects, while the Rs 12.544 crore offer for sale related to selling shareholders. The utilisation certificate marks the offer-for-sale amount and selling-shareholder expenses as not applicable for object-wise deployment by the company.
The financial-results notes report gross fresh-issue proceeds of Rs 51.20 crore and net proceeds of Rs 47.9229 crore after company-borne offer expenses of Rs 3.2771 crore. The utilisation statement nevertheless presents Rs 51.20 crore across the five disclosed objects, including Rs 3.2771 crore for issue-related expenses.
The object-wise figures therefore distinguish operating and capital deployment from the offer-for-sale portion of the IPO. Rs 30.00 crore went to working capital, Rs 6.50 crore to specified borrowings, Rs 5.00 crore to general corporate purposes and Rs 3.1786 crore to issue expenses, while no spending was recorded for the Rs 6.40 crore factory civil-work object.
SMR Jewels’ cash-flow statement for the half year ended September 30, 2026 reported Rs 49.2645 crore as proceeds from issue of share capital, net, within financing activities. That cash-flow line is not presented as an object-wise deployment schedule, whereas the utilisation certificate identifies spending against the IPO objects.
How was SMR Jewels’ IPO utilisation checked?
Surana Maloo & Co., Chartered Accountants, certified the object-wise utilisation after examining SMR Jewels’ books of account, bank statements, relevant supporting documents, and information and explanations furnished to it. Its report was dated November 2, 2026 and covered the statement attached as Annexure 1.
The auditor said the utilisation details had been accurately extracted from unaudited financial statements, supporting documents and company records. The firm also said its examination was conducted under the Institute of Chartered Accountants of India’s Guidance Note on Reports or Certificates for Special Purposes.
The report was prepared at management’s request to enable submission of a statement of deviation and variation to the BSE SME Exchange. Surana Maloo & Co. said its scope was restricted to the details of issue proceeds and expenses recorded in the company’s books, and it made no representation about interpretations of utilisation requirements.
The source also identifies SMR Jewels as operating in manufacturing, trading and job work of jewellery and related accessories or products. It reports one business segment, meaning no separate segment-wise financial disclosures were provided alongside the IPO utilisation statement.
Conclusion
SMR Jewels had deployed most of its Rs 51.20 crore fresh issue by September 30, 2026, led by the full use of Rs 30.00 crore for working capital and Rs 6.50 crore for borrowings. The unutilised Rs 6.52 crore was concentrated in the Rs 6.40 crore factory civil-construction allocation, with only Rs 12.14 lakh remaining across general corporate purposes and issue expenses.
The next disclosed matter to watch is actual spending on the factory construction project. The November 2, 2026 certificate gives no construction schedule, explanation for the undrawn amount or revised project cost, while the Rs 12.14 lakh residual for general corporate purposes and issue expenses also remained unutilised at the reporting date.