










Suba Hotels Limited revenue rises 51% as GST cost moderates margins
Key highlights
- Suba Hotels reported H1 standalone revenue from operations of Rs 53.45 crore, up about 51% from Rs 35.28 crore a year earlier.
- Suba Hotels charged a Rs 3.29 crore GST input-tax-credit disallowance to H1 profit and loss after the 22 September 2025 rate revision.
- Suba Hotels’ H1 standalone profit after tax rose to Rs 2.50 crore from Rs 1.87 crore, while basic earnings per share were Rs 1.03.
- Suba Hotels reported Rs 45.94 crore of net cash generated from operating activities in the six months to 30 September 2026.
powered by IRIS
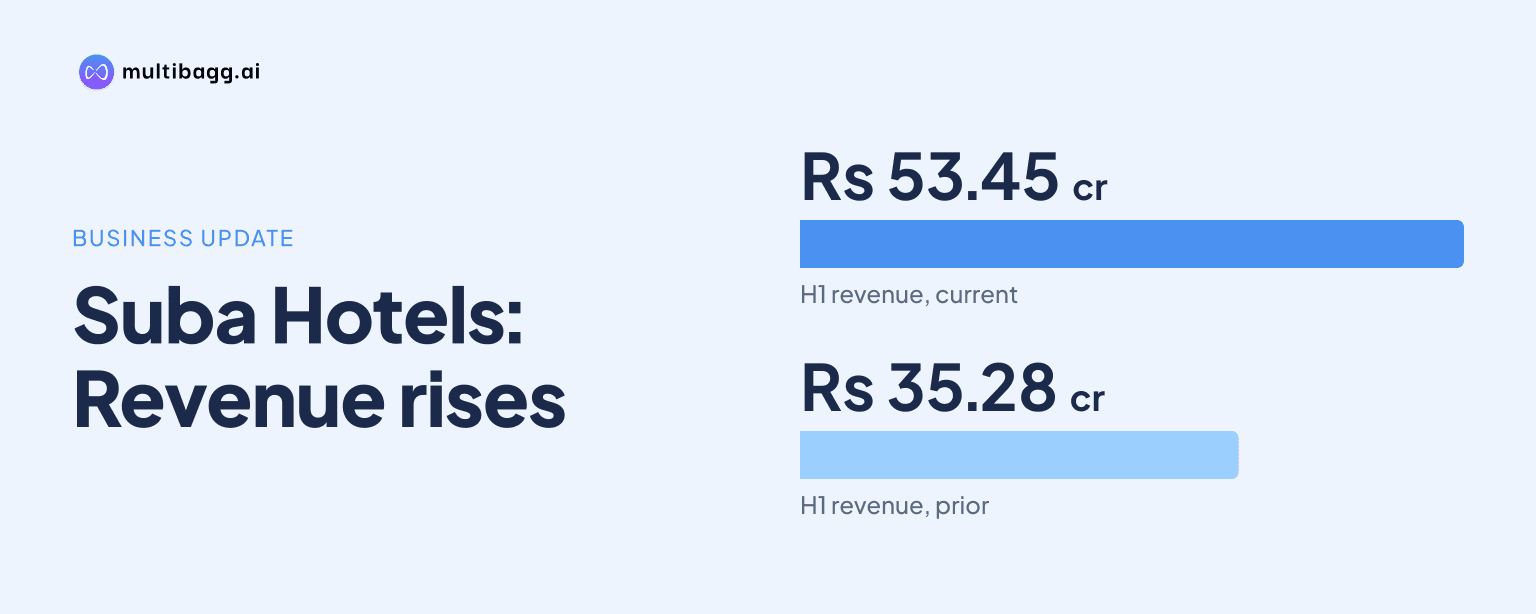
For the half year ended 30 September 2026, Suba Hotels Limited reported standalone operating revenue of Rs 53.45 crore, up about 51% year on year, but charged a Rs 3.29 crore goods and services tax input-tax-credit disallowance to profit and loss, which it said moderated margins.
Know Suba Hotels inside out
Results, valuation, peers and who's buying, in one view.
How fast did Suba Hotels’ H1 revenue grow?
Suba Hotels’ standalone revenue from operations increased to Rs 53.45 crore in April 2026 to September 2026, from Rs 35.28 crore in April 2025 to September 2025, a year-on-year rise of about 51%. Total income, including other income, rose to Rs 55.31 crore from Rs 35.51 crore over the same periods. Other income was Rs 1.86 crore in H1, compared with Rs 22.91 lakh a year earlier.
The H1 result was also broadly level with the immediately preceding October 2025 to March 2026 period, when operating revenue was Rs 53.15 crore and total income was Rs 54.45 crore. The company’s full-year standalone operating revenue for April 2025 to March 2026 was Rs 88.43 crore, meaning the April-to-September 2026 revenue exceeded half of that prior full-year amount.
The reported statement covers one hospitality segment, as Suba Hotels said segment reporting under Accounting Standard 17 was not applicable because its business falls within hospitality. The filing does not break the Rs 53.45 crore operating revenue into hotel properties, geographic markets, room revenue, food and beverage revenue, or other service lines.
What caused Suba Hotels’ margin moderation in H1?
Suba Hotels said a change in the goods and services tax, or GST, rate was the stated reason its margins moderated: specified hotel supplies moved from 12% with input tax credit, or ITC, to 5% without ITC from 22 September 2025. The company recorded a Rs 3.29 crore disallowance of ITC in the H1 profit and loss account.
Management described the Rs 3.29 crore charge as an incremental cost impact compared with H1 of the previous year. The filing does not quantify the profit outcome excluding that charge or specify which hotel supplies accounted for the disallowed credit. It does expressly connect the rate revision and lost ITC eligibility with the moderation in margins.
Profit before tax was Rs 3.60 crore in April 2026 to September 2026, compared with Rs 2.59 crore a year earlier, while profit after tax rose to Rs 2.50 crore from Rs 1.87 crore. Profit after tax therefore increased less rapidly than operating revenue. Basic and diluted earnings per share were both Rs 1.03, versus Rs 1.07 in the comparable H1, on a face value of Rs 10 per share.
Which H1 expense lines rose most for Suba Hotels?
Suba Hotels’ total expenses increased to Rs 51.71 crore in H1 from Rs 32.93 crore a year earlier, an increase of Rs 18.78 crore. Other expenses were the largest cost line at Rs 29.53 crore, up from Rs 15.87 crore. The filing places the GST input-credit disallowance in the H1 profit and loss account but does not separately identify the expense heading in which it was classified.
Employee benefit expense increased to Rs 13.54 crore from Rs 10.02 crore, while food and beverages consumed rose to Rs 5.85 crore from Rs 4.30 crore. Finance costs rose to Rs 1.41 crore from Rs 1.27 crore, whereas depreciation and amortisation declined to Rs 1.38 crore from Rs 1.48 crore. These movements occurred alongside revenue growth and the incremental GST-related cost.
Compared with the preceding October 2025 to March 2026 half-year, profit before tax fell from Rs 9.83 crore to Rs 3.60 crore and profit after tax fell from Rs 7.04 crore to Rs 2.50 crore. Total expenses were Rs 44.63 crore in that preceding half-year, while total income was Rs 54.45 crore, Rs 85.54 lakh below the latest H1 amount.
Got a follow-up? Ask IRIS
What changed in Suba Hotels’ balance sheet and cash flow?
Suba Hotels’ standalone total assets were Rs 202.50 crore at 30 September 2026, compared with Rs 199.67 crore at 31 March 2026. Property, plant and equipment rose to Rs 59.70 crore from Rs 50.16 crore, and capital work in progress increased to Rs 33.49 crore from Rs 25.50 crore.
Cash and cash equivalents increased to Rs 14.26 crore from Rs 5.56 crore, while other bank balances stood at Rs 10.83 crore at 30 September 2026. Trade receivables were Rs 23.18 crore, compared with Rs 22.43 crore at the preceding year-end. Short-term loans and advances declined to Rs 14.84 crore from Rs 23.24 crore, while other current assets fell to Rs 11.53 crore from Rs 45.81 crore.
Long-term borrowings increased to Rs 24.57 crore from Rs 19.15 crore, but short-term borrowings declined to Rs 20.08 crore from Rs 32.38 crore. The cash-flow statement reported Rs 45.94 crore of net cash generated from operating activities for the period, Rs 18.11 crore used in investing activities and Rs 19.02 crore used in financing activities, resulting in a net cash inflow of Rs 8.71 crore.
How were Suba Hotels’ H1 results reviewed?
Suba Hotels’ board approved the unaudited standalone results for the period ended 30 September 2026 on 13 November 2026 after review by the audit committee. The results were prepared under Accounting Standard 25, Interim Financial Reporting, as prescribed under Section 133 of the Companies Act, 2013, according to the filing.
The statutory auditor, Shah & Taparia, issued a limited review report dated 13 November 2026. It said nothing had come to its attention causing it to believe the standalone statement was not prepared in accordance with applicable accounting principles or that it contained a material misstatement. The auditor noted that a limited review provides moderate assurance and is less extensive than an audit.
Conclusion
Suba Hotels reported Rs 53.45 crore of standalone operating revenue in the six months to 30 September 2026, a 51% year-on-year increase, and profit after tax of Rs 2.50 crore, up from Rs 1.87 crore. However, profit growth did not match revenue growth, with the company identifying a Rs 3.29 crore GST input-tax-credit disallowance as an incremental cost that moderated margins.
The filing provides no forecast or capital-work completion timetable. Future disclosures can show the continuing effect of the 22 September 2025 GST-rate revision and the movement in capital work in progress, which was Rs 33.49 crore at 30 September 2026 versus Rs 25.50 crore at 31 March 2026.