










Sudal going-concern basis hinges on Supreme Court appeal
Key highlights
- Sudal’s September 30, 2026 going-concern basis depends on its pending Supreme Court appeal.
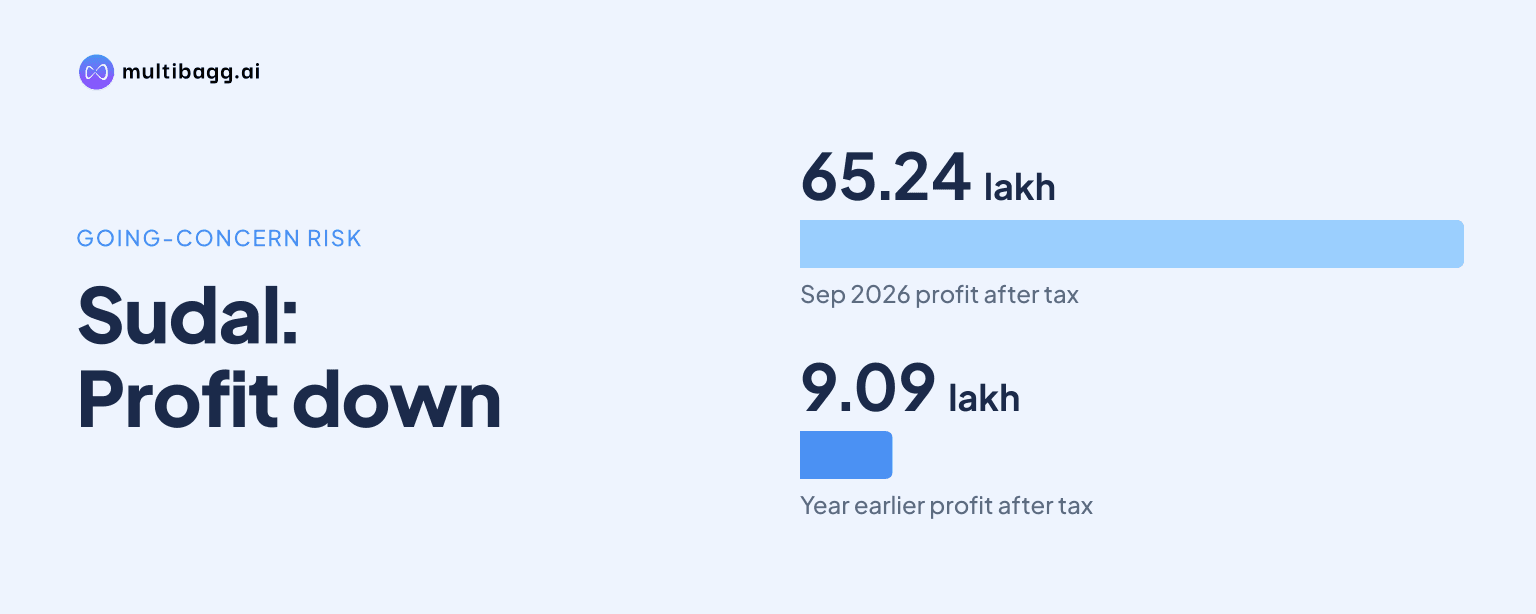
- Sudal reported Rs 9.09 lakh profit after tax in the September 2026 quarter, versus Rs 65.24 lakh a year earlier.
- Six-month revenue rose to Rs 109.97 crore from Rs 86.66 crore, while profit after tax rose to Rs 3.22 crore from Rs 1.06 crore.
- Sudal wrote back Rs 125.41 crore of creditor liabilities in the September 2023 quarter under its PIRP.
powered by IRIS
Sudal Industries Limited’s going-concern basis for the six months ended September 30, 2026 depends on its pending Supreme Court appeal, while the reviewer issued a qualified conclusion and could not quantify possible effects on reported profit, liabilities or equity; management cites expert legal opinion in expecting a favourable outcome.
Know Sudal Industries inside out
Results, valuation, peers and who's buying, in one view.
Why does Sudal’s going-concern basis depend on the appeal?
Sudal’s going-concern assumption depends on the outcome of its Supreme Court appeal concerning its pre-packaged insolvency resolution plan, according to the limited review report for the quarter and six months ended September 30, 2026. The reviewer identified a material uncertainty related to going concern because the legal matter remains sub judice, or under judicial consideration.
The reviewer said it could not comment on the possible effect of the litigation on Sudal’s net profit or loss for the September 2026 quarter and half year, or on liabilities and other equity at September 30, 2026. It issued a qualified conclusion, meaning the possible effects of the unresolved matter could not be quantified at the reporting date.
Management nevertheless considered it appropriate to prepare the results on a going-concern basis. Sudal said this judgement was based on expert legal opinion and management’s expectation of a favourable outcome from the appeal, rather than on a disclosed final court ruling as of November 14, 2026.
The Board approved the unaudited September 2026 results and considered the limited review report on November 14, 2026. The reviewer conducted its work under Standard on Review Engagements 2410, which involves limited procedures and provides moderate assurance rather than the assurance of a full audit.
What is the Supreme Court dispute over Sudal’s resolution plan?
The dispute concerns Sudal’s pre-packaged insolvency resolution plan, or PIRP, approved by the National Company Law Tribunal, or NCLT, Mumbai on August 10, 2023. The National Company Law Appellate Tribunal, or NCLAT, New Delhi subsequently set aside the NCLT order on July 22, 2024.
Sudal appealed the July 2024 NCLAT order to the Supreme Court, which stayed that order on October 4, 2024. Sudal said it has implemented the PIRP in line with the NCLT’s August 2023 directions, but the filing does not disclose a date for a final Supreme Court hearing or judgment.
Under the NCLT-approved plan, Sudal said it paid secured and unsecured financial creditors in full and wrote back Rs 125.41 crore of liabilities related to those creditors during the quarter ended September 30, 2023. The limited review report links the unquantified uncertainty over profit, liabilities and equity to the appeal over that plan.
The filing says the Supreme Court will pass a necessary order after submissions by the parties. It does not set out an alternative accounting outcome, quantify a potential reversal of the Rs 125.41 crore write-back, or estimate the effect on the September 30, 2026 balance sheet if the appeal does not produce the outcome management expects.
How did Sudal perform in the September 2026 quarter?
Sudal reported profit after tax of Rs 9.09 lakh for the quarter ended September 30, 2026, down from Rs 65.24 lakh a year earlier and Rs 3.13 crore in the quarter ended June 30, 2026. Revenue from operations increased to Rs 56.85 crore from Rs 44.97 crore in the September 2025 quarter and Rs 53.12 crore in the preceding quarter.
The September 2026 quarter recorded a loss before tax of Rs 48.73 lakh, compared with profit before tax of Rs 51.87 lakh a year earlier and Rs 4.65 crore in June 2026. A total tax credit of Rs 57.82 lakh, including a Rs 49.82 lakh credit for earlier years, resulted in the reported quarterly profit after tax.
Cost of materials consumed rose to Rs 51.12 crore in the September 2026 quarter from Rs 37.18 crore in September 2025, while other expenses increased to Rs 5.93 crore from Rs 4.95 crore. Total expenses of Rs 57.86 crore exceeded total income of Rs 57.37 crore, whereas the year-earlier quarter reported expenses of Rs 44.56 crore and total income of Rs 45.07 crore.
Finance costs were Rs 61.59 lakh for the September 2026 quarter, compared with Rs 62.41 lakh a year earlier and Rs 41.34 lakh in June 2026. Depreciation and amortisation declined to Rs 97.36 lakh from Rs 1.40 crore in the September 2025 quarter, while the filing does not attribute the overall change in pre-tax result to any single cost line.
Got a follow-up? Ask IRIS
How did Sudal’s half-year results compare with last year?
Sudal reported revenue from operations of Rs 109.97 crore for the six months ended September 30, 2026, up from Rs 86.66 crore in the corresponding six months of 2025. Profit after tax rose to Rs 3.22 crore from Rs 1.06 crore, while profit before tax increased to Rs 4.16 crore from Rs 1.24 crore.
Total income for the six-month period was Rs 110.56 crore, compared with Rs 86.84 crore a year earlier, while total expenses rose to Rs 106.39 crore from Rs 85.61 crore. The resulting pre-tax profit improved by Rs 2.93 crore year on year, although the September 2026 quarter itself recorded a pre-tax loss of Rs 48.73 lakh.
Materials cost for the six months was Rs 92.26 crore, against Rs 70.52 crore in the prior-year period. Finance costs declined to Rs 1.03 crore from Rs 1.28 crore, and depreciation and amortisation declined to Rs 1.92 crore from Rs 1.97 crore over the same comparison.
Sudal reported total comprehensive income of Rs 3.16 crore for the half year ended September 30, 2026, compared with Rs 1.06 crore in the year-earlier half year. The difference between profit after tax of Rs 3.22 crore and comprehensive income reflects an other comprehensive loss of Rs 6.36 lakh on remeasurement of defined-benefit plans after tax.
What business and accounting disclosures did Sudal make?
Sudal reports one operating segment, manufacturing aluminium extrusions and downstream or value-added products, under Indian Accounting Standard 108. The September 2026 filing therefore provides no separate revenue, profit or asset figures for extrusion products and downstream products.
The filing notes that the year ended March 31, 2026 included an impairment loss of Rs 2.67 crore on property, plant and equipment. That disclosure relates to the prior financial year, and Sudal’s note does not disclose a separate new impairment charge for the quarter or six months ended September 30, 2026.
Equity share capital was Rs 8.37 crore throughout the September 2026 quarter and the prior comparative periods shown in the results. Basic and diluted earnings per share for the September 2026 quarter were Rs 0.11, compared with Rs 0.78 in September 2025 and Rs 3.75 in June 2026; the company stated these quarterly figures were not annualised.
Conclusion
Sudal’s filing combines improved half-year revenue of Rs 109.97 crore and profit after tax of Rs 3.22 crore with a material legal uncertainty that affects the basis on which its September 2026 accounts were prepared. The qualified conclusion does not quantify an adjustment, but it makes the Supreme Court appeal central to the reported position on profit, liabilities and other equity.
The next disclosed matter to watch is the Supreme Court’s order after the parties complete their submissions on the appeal against the July 22, 2024 NCLAT order. Management expects a favourable outcome based on expert legal opinion, but Sudal has disclosed neither a decision timetable nor a quantified effect of any outcome on the Rs 125.41 crore creditor-liability write-back.