










Sumax Engineering Limited deploys Rs 21.77 crore IPO proceeds
Key highlights
- Sumax Engineering used Rs 21.77 crore of its Rs 43.34 crore IPO allocation by September 30, 2026.
- The proposed Haryana manufacturing unit received Rs 9.62 crore, while working capital received Rs 8.17 crore.
- Rs 21.57 crore of IPO proceeds remained unutilised at September 30, 2026.
- Sumax Engineering reported no deviation or variation from IPO objects for the September 2026 quarter.
powered by IRIS
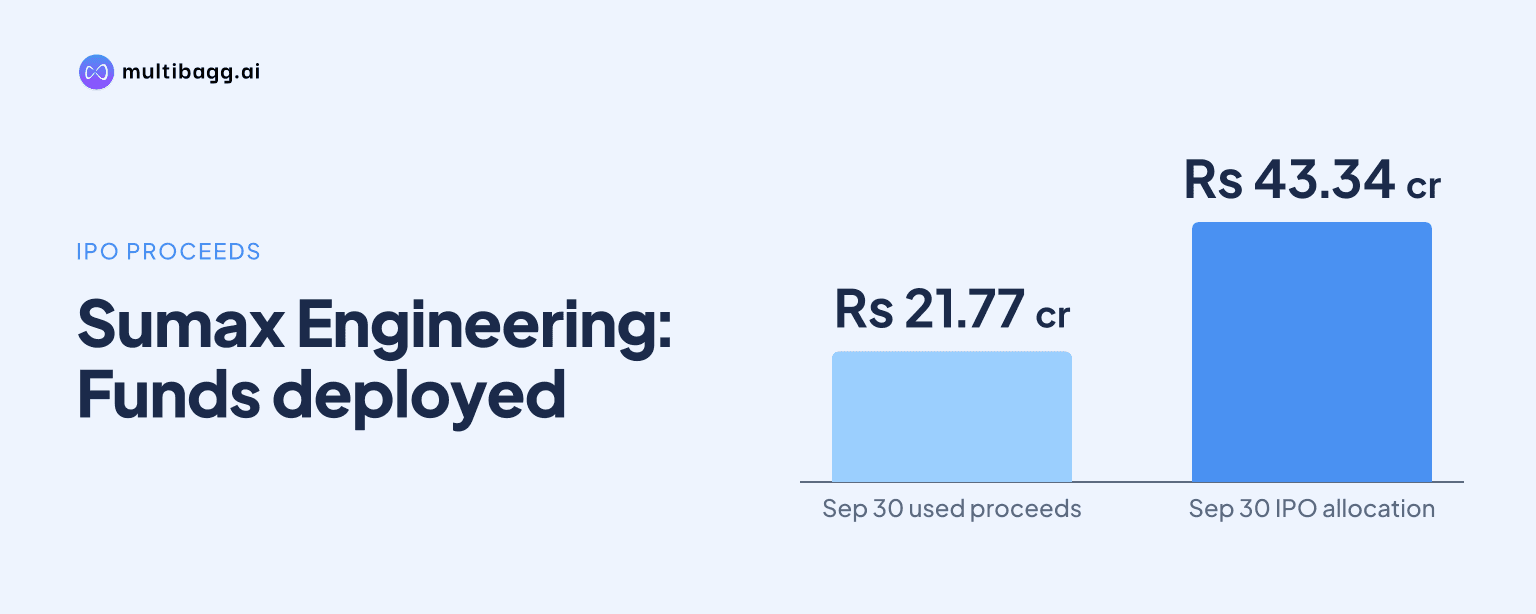
Sumax Engineering Limited used Rs 21.77 crore of its Rs 43.34 crore initial public offering (IPO) proceeds by September 30, 2026, following its September 2, 2026 listing on NSE Emerge. Sumax Engineering directed Rs 9.62 crore to its proposed Haryana manufacturing unit and Rs 8.17 crore to working capital, and reported no deviation from its prospectus objects.
Know Sumax Engineering inside out
Results, valuation, peers and who's buying, in one view.
How much of Sumax Engineering's IPO proceeds had been used?
Sumax Engineering had used Rs 21.77 crore of the Rs 43.34 crore allocated from its public issue as of September 30, 2026, leaving Rs 21.57 crore unutilised. The company issued 42,91,200 equity shares with a face value of Rs 10 each at a premium of Rs 91 each and listed on NSE Emerge on September 2, 2026.
The utilised amount was slightly more than half of the total Rs 43.34 crore allocation. The proceeds disclosure formed part of the unaudited standalone financial results for the half year ended September 30, 2026, which the board approved on November 6, 2026 after review by the audit committee.
Where did Sumax Engineering deploy the IPO money?
Sumax Engineering's largest disclosed IPO use was Rs 9.62 crore for construction of proposed manufacturing Unit II in Haryana. The project is planned at Plot No. P-32, Street No. B, Sector 11, Model Economic Township, Village Nimana, Tehsil Badli, District Jhajjar, and had a total allocation of Rs 16.62 crore.
Working-capital requirements received Rs 8.17 crore against a Rs 12.00 crore allocation, leaving Rs 3.83 crore to be used. Sumax Engineering also deployed Rs 2.95 crore of its Rs 4.03 crore issue-expense allocation and Rs 1.03 crore of the Rs 5.80 crore set aside for general corporate purposes.
No IPO amount had been used for the proposed Rajasthan Unit I as of September 30, 2026. The entire Rs 4.89 crore earmarked for construction at Plot No. E-185, RIICO Industrial Area, Karoli, Tehsil Tapukara, Rajasthan, remained unutilised at the reporting date.
Did Sumax Engineering change its IPO objects?
Sumax Engineering reported no deviation or variation in the use of IPO proceeds for the quarter ended September 30, 2026. Its Regulation 32 disclosure said the audit committee reviewed the statement at its November 6, 2026 meeting and that utilisation followed the objects clause in the prospectus.
The Rs 21.77 crore deployed by September 30 was allocated among the five stated purposes rather than an undisclosed use. The company said its Rs 21.57 crore unutilised balance was invested in a monitoring account, current account and fixed deposits, without providing a split across those three categories.
The allocation schedule separates manufacturing projects from operational funding and transaction costs. Unit I and Unit II together accounted for Rs 21.51 crore of the total Rs 43.34 crore allocation, compared with Rs 12.00 crore for working capital, Rs 5.80 crore for general corporate purposes and Rs 4.03 crore for issue-related expenses.
Got a follow-up? Ask IRIS
What do Sumax Engineering's September financial statements show?
Sumax Engineering reported cash and cash equivalents of Rs 22.26 crore at September 30, 2026, compared with Rs 1.80 crore at March 31, 2026. Its cash-flow statement recorded Rs 40.67 crore in proceeds from the issue of share capital during the half year ended September 30, 2026.
The same cash-flow statement showed Rs 18.08 crore of net cash used in investing activities during the half year, including Rs 11.09 crore spent on property, plant and equipment, including capital advances. Sumax Engineering recorded net cash generated from financing activities of Rs 35.86 crore, compared with Rs 4.73 crore for the year ended March 31, 2026.
Long-term loans and advances rose to Rs 9.50 crore at September 30, 2026 from Rs 0.43 crore at March 31, 2026. Capital work-in-progress increased to Rs 1.57 crore from Rs 0.44 crore, while property, plant and equipment was Rs 31.75 crore, compared with Rs 31.57 crore six months earlier.
How did Sumax Engineering perform in the September 2026 half year?
Sumax Engineering reported revenue from operations of Rs 76.93 crore for the half year ended September 30, 2026, compared with Rs 71.82 crore for the half year ended September 30, 2025. Profit after tax rose to Rs 8.44 crore from Rs 5.26 crore over the comparable prior-year half year.
Total income reached Rs 77.49 crore for the September 2026 half year, versus Rs 72.16 crore a year earlier, while total expenses increased to Rs 66.36 crore from Rs 64.37 crore. Finance costs declined to Rs 14.37 lakh from Rs 24.34 lakh, and basic and diluted earnings per share were Rs 4.44, compared with Rs 3.57 in the September 2025 half year.
The results identify the automotive sector as Sumax Engineering's single reportable segment. In its limited review report dated November 6, 2026, the statutory auditor said nothing had come to its attention to indicate that the financial statement disclosures did not meet applicable requirements or contained a material misstatement.
Conclusion
Sumax Engineering's September disclosure shows that project spending and working-capital funding accounted for most of the Rs 21.77 crore used from the IPO allocation. The Haryana Unit II project and working capital together received Rs 17.79 crore, while the Rajasthan Unit I allocation of Rs 4.89 crore had not yet been deployed.
The next point to watch is the use of the Rs 21.57 crore balance, particularly the remaining Rs 7.00 crore for Haryana Unit II and the full Rs 4.89 crore for Rajasthan Unit I. Until those proceeds are deployed, Sumax Engineering says they are held in a monitoring account, current account and fixed deposits.