










Sundram Fasteners expects H2 growth to match H1, exports lift margins
Key highlights
- Sundram Fasteners expects H2 growth to mirror H1 after 25% consolidated growth in H1 versus H1 FY26.
- Management expects a higher export share to expand H2 margins after a 2.5% contribution or gross-margin impact from raw-material pricing.
- Commercial vehicles grew 25% in H1, including 21% growth in medium- and heavy-commercial vehicles and 27% in light commercial vehicles.
- Wind-energy revenue is expected to exceed Rs 500 crore annually after the third investment phase.
powered by IRIS
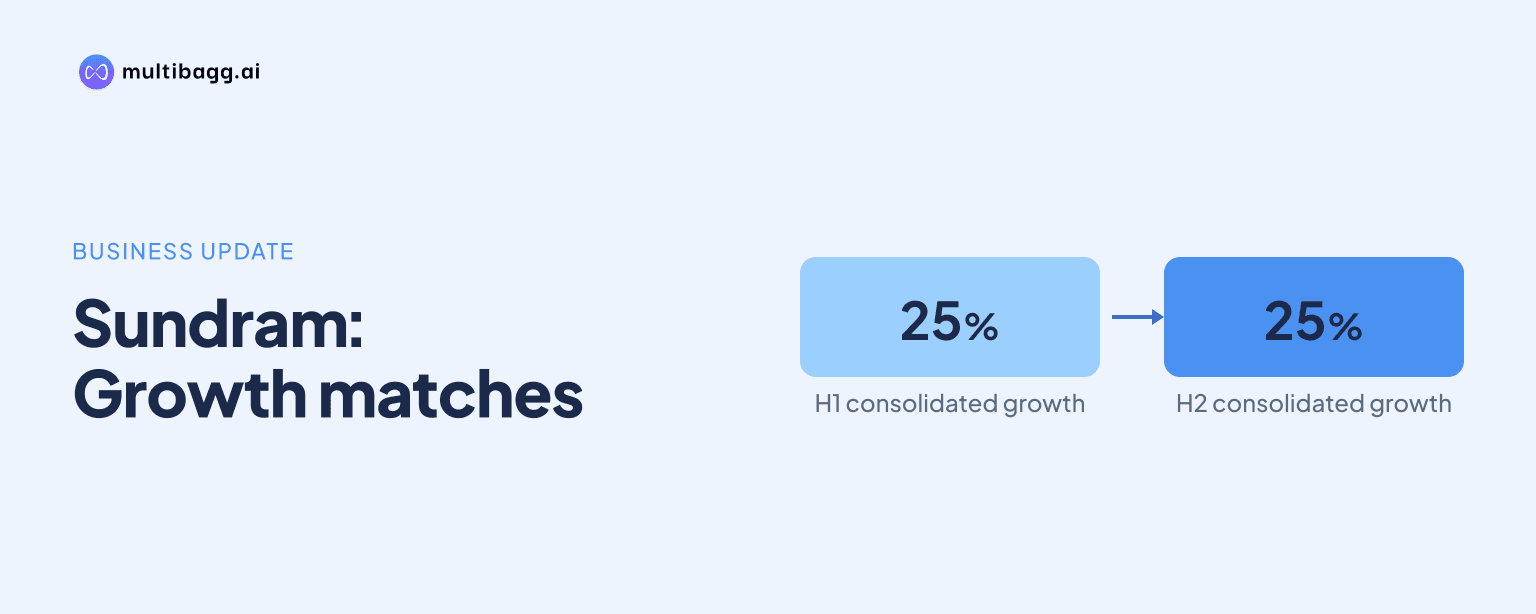
Sundram Fasteners expects second-half growth to mirror H1 after consolidated growth of 25% in H1 versus H1 FY26, while management expects a higher export share to expand margins. The outlook includes domestic H2 growth of about 3% to 5%, although tractor demand may soften during Q3 and remain moderate in Q4.
Know Sundram Fasteners inside out
Results, valuation, peers and who's buying, in one view.
Will Sundram Fasteners grow as quickly in H2 as H1?
Yes. Sundram Fasteners said H2 should “mirror a similar growth” to H1 based on current market indications, after an analyst referred to 25% consolidated growth in H1 versus H1 FY26. Management did not provide a formal full-year revenue target and said FY28 guidance was premature because of a volatile situation.
Management also said growth for the overall year should be almost at the same level as H1 growth, with slight improvement in its original-equipment, retail and export businesses. This is an outlook based on current market indications, not a quantified revenue forecast or a commitment to a specific full-year growth rate.
Quarterly tonnage growth was about 15% to 16%, compared with around 13% cited for the preceding quarter. The increase in tonnage growth supports management’s view that H2 can sustain the H1 trajectory, although the company did not disclose corresponding quarterly revenue or segment volumes.
What is expected to expand Sundram Fasteners’ H2 margins?
A higher export share is expected to expand Sundram Fasteners’ margins in H2. Management said margins should “definitely expand” and attributed that expectation primarily to exports occupying a higher share of the revenue mix, but it did not quantify either the expected change in export mix or the margin improvement.
Raw-material costs were the main reason for the H1 margin effect described on the call. Management said price revisions affected about 3.7% of revenue, while customer realisations were roughly 2.5%, leaving a gap of about 1%. It said the mathematical effect of these line items caused a decline of around 2.5% in contribution or gross margin.
Gas and petroleum-related input costs had risen from below Rs 100 to more than Rs 200 before moderating to around Rs 150. Management said these costs remained above the level before March 2026, but characterised indirect materials as negligible in the overall margin outcome. It said raw-material prices, rather than gas and other indirect costs, materially affected margins.
How does Sundram Fasteners expect domestic demand to develop in H2?
Sundram Fasteners expects domestic performance to be about 3% to 5% higher in H2, although growth rates will moderate from H1. Management said H2 activity in commercial vehicles, cars and sport-utility vehicles should remain higher in absolute terms than H1, despite a higher comparison base.
Commercial vehicles delivered 25% combined growth in H1, comprising 21% growth in medium- and heavy-commercial vehicles and 27% growth in light commercial vehicles. Management expects H2 commercial-vehicle growth in the mid-teens rather than another 25% increase, but said the segment’s absolute activity should be slightly higher than in H1.
Management expects cars and sport-utility vehicles to grow at low double-digit rates in H2. It cautioned that entry-level cars and sedans could face pressure if uneven monsoon conditions affect agricultural output, rural cash flows and demand. Even under that scenario, management said H2 numbers in the car and sport-utility vehicle segments should exceed H1.
Got a follow-up? Ask IRIS
Why is tractor demand Sundram Fasteners’ main H2 domestic risk?
Tractors are the only domestic segment where Sundram Fasteners said H2 volumes may be lower than H1 in absolute terms. Management expects demand to soften in Q3 and become moderately paced in Q4 because of the comparison base and an uneven monsoon outlook.
Management cited an India Meteorological Department forecast range of 88% to 112% of the normal average level as a source of concern for tractor demand. It indicated that tractor growth may be below 10%, potentially around 5% to 7%, while still expecting full-year tractor demand to remain above the prior year.
Export-linked Class 8 truck demand provides a separate area of support. Management said cumulative preliminary Class 8 orders in the past 12 months totalled 353,000 units, with original-equipment manufacturers’ order books full. Retail demand was down 5% year to date through September, but customers expected the year to end 3% to 5% above the prior year.
What are Sundram Fasteners’ non-auto and overseas plans?
Sundram Fasteners said non-auto business accounted for about 35% to 37% of overall business, up from around 30% in earlier years, against a stated aspiration of 50%. Growth has been supported by wind energy, aerospace, railways, industrial fasteners and aftermarket requirements.
The third phase of wind-energy investment is under execution and should take annual wind-energy revenue beyond Rs 500 crore, according to management. The indicated wind investment was Rs 70 crore to Rs 80 crore. Railway tenders and orders can be supplied from existing capacity, so management said it had not planned separate railway investment.
Aerospace generated Rs 50 crore last year and is expected to produce more than Rs 100 crore this year. Management is considering Rs 30 crore to Rs 40 crore of investment in testing and other equipment to support a future aerospace revenue level of Rs 200 crore.
Sundram Fasteners’ China subsidiary grew 10% to 12% in local-currency terms and 25% to 30% in rupee terms, supported by construction-equipment and commercial-vehicle supplies. Its United Kingdom subsidiary posted more than 20% growth in rupee terms, reflecting European truck-market activity. Management said both subsidiaries were profitable but did not disclose revenue, margins or their contribution to consolidated sales.
Conclusion
Sundram Fasteners’ H2 outlook combines management’s expectation of growth comparable with H1 and an expected margin expansion from a greater export contribution. Domestic demand is expected to remain positive by 3% to 5% in H2, with commercial vehicles, cars and sport-utility vehicles offsetting slower tractor demand.
The next disclosed milestones are completion of the current FY27 capital-expenditure programme, which management said could be slightly above its planned Rs 400 crore depending on customer requirements, and the Q3 business-planning process that should provide a clearer view of FY28 spending. Management also expects the ongoing wind investment to support annual revenue beyond Rs 500 crore and aerospace revenue to exceed Rs 100 crore this year.