










Tusaldah offer price trails BSE close by Rs 162.85 per share
Key highlights
- Tusaldah’s Rs 20 open-offer price was Rs 162.85 below the Rs 182.85 BSE close on October 5, 2026.
- Tusaldah’s independent valuer certified fair value at Rs 19.41 per share on September 25, 2026.
- Tusaldah’s BSE trading turnover was 2.67% of listed shares during September 2025 to August 2026.
- Tusaldah’s open offer seeks up to 37,83,000 shares for maximum consideration of Rs 7.57 crore.
powered by IRIS
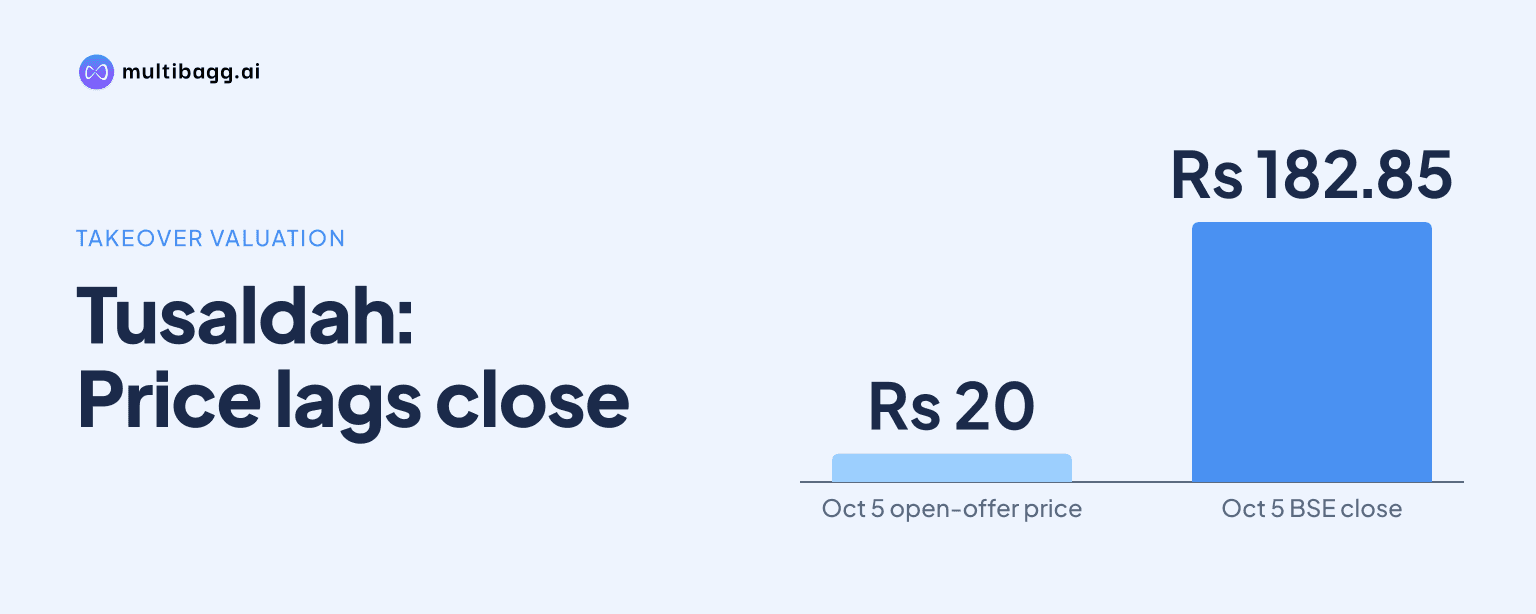
Tusaldah Limited’s Rs 20 per-share open-offer price was Rs 162.85 below the Rs 182.85 BSE closing price on October 5, 2026, even though it exceeded the Rs 19.41 independent fair value cited in the Letter of Offer. The price was determined under rules for an infrequently traded share with 2.67% annualised turnover.
Know Tusaldah inside out
Results, valuation, peers and who's buying, in one view.
Why is Tusaldah’s open-offer price Rs 20 per share?
Tusaldah’s Rs 20 offer price was the highest applicable price identified under Regulation 8(2) of the SEBI (Substantial Acquisition of Shares and Takeovers) Regulations, 2011. It is also the negotiated price at which equity shares and convertible warrants are proposed to be allotted to the acquirers through the preferential issue.
The 60-trading-day volume-weighted average market-price measure did not apply because Tusaldah’s shares were classified as infrequently traded on BSE. During the 12 months from September 2025 to August 2026, 62,555 shares were traded against 23,43,430 listed shares, resulting in annualised trading turnover of 2.67%.
Tusaldah reported that no acquisition by the acquirers during the 52 weeks or 26 weeks before the September 25, 2026 public announcement supplied another applicable price benchmark. The Letter of Offer also states that no corporate action, or reported information requiring adjustment, had changed the offer-price parameters.
A valuation report dated September 25, 2026 by Bhavesh M Rathod, a registered valuer, arrived at Rs 19.61 per share for the preferential issue. The negotiated preferential price was set at Rs 20 per share, or Rs 0.39 above that valuation, and the acquirers and manager to the offer describe Rs 20 as justified under the takeover regulations.
How far does Tusaldah’s offer price trail BSE prices?
Tusaldah’s Rs 20 offer price was below each of the four BSE closing prices disclosed around the public announcement, with the largest difference of Rs 162.85 on October 5, 2026. The BSE close rose from Rs 136.55 before the September 25 public announcement to Rs 182.85 on the detailed public statement date.
Tusaldah’s BSE close increased by Rs 46.30, or about 33.9%, between September 24 and October 5, while the offer price remained Rs 20 as of the Letter of Offer. The document does not apply the quoted BSE prices as the regulatory market benchmark because the shares were infrequently traded; it instead relies on the negotiated price and valuation measures.
The Letter of Offer sets out circumstances in which the Rs 20 price could change. If the acquirers buy shares during the offer period above Rs 20, the offer price would be revised upward under the regulations; purchases at a higher price during the 26 weeks after the tendering period may also require a difference payment to accepted shareholders within 60 days, subject to stated exceptions.
Got a follow-up? Ask IRIS
How was Tusaldah’s Rs 19.41 fair value calculated?
Tusaldah’s independent fair value was certified at Rs 19.41 per share by Karan Chetan Shah, a registered valuer, in a September 25, 2026 certificate. The valuer assigned 95% weight to the Comparable Companies Method, or CCM, and 5% to the Market Price Method.
The valuer said the 5% market-price weighting reflected the limited relevance of a listed but infrequently traded share. The CCM received 95% weight because comparable listed companies and market-based parameters were considered suitable for assessing Tusaldah’s position relative to peers.
The asset approach was not selected because the valuer said it is primarily suited to non-financial assets and would produce a per-share value below face value given Tusaldah’s losses. The Profit Earning Capacity Value, or PECV, method produced a negative Rs 5.14 per share and received no weight because the valuer said that outcome did not reflect the company’s continued net assets.
Tusaldah reported net worth of Rs 22.44 lakh at September 30, 2026, down from Rs 44.99 lakh at March 31, 2026 and Rs 1.07 crore at March 31, 2025. Its book value per share was Rs 0.96 at September 30, 2026, while its limited-reviewed loss for the half year ended that date was Rs 22.56 lakh.
What does Tusaldah’s open offer cover and how is it funded?
Tusaldah’s open offer covers up to 37,83,000 equity shares at Rs 20 each, for maximum consideration of Rs 7.57 crore if fully accepted. That quantity equals 26.00% of the expanded equity and voting share capital of 1,45,50,000 shares, which includes the proposed equity shares and convertible warrants.
Before the transaction, the acquirers held 7,83,164 shares, or 33.42%, of Tusaldah’s existing 23,43,430 shares. After the preferential allotment and assuming full acceptance in the open offer, their holding would be 1,14,75,463 shares, or 78.87% of expanded capital, while public ownership would be 30,74,537 shares, or 21.13%.
The acquirers deposited Rs 1.90 crore in cash into an escrow account with ICICI Bank on September 25, 2026, which the Letter of Offer says exceeded 25% of the maximum consideration. Navigant Corporate Advisors, the manager to the offer, confirmed that verifiable funding arrangements were in place and that the acquirers could fulfil the offer obligation.
Certificates dated August 12, 2026 stated that Acquirer-1 had net worth of Rs 28.28 crore and Acquirer-2 had net worth of Rs 17.93 crore, each measured as of June 12, 2026. The Letter of Offer names November 17, 2026 as the identified date for dispatch, while permitting eligible owners who hold shares any time before the offer closes to participate through BSE’s acquisition window.
Conclusion
Tusaldah’s Rs 20 offer price is supported in the Letter of Offer by the Rs 19.41 independent valuation, the Rs 19.61 preferential-issue valuation and the Rs 20 negotiated preferential price. However, it remained Rs 162.85 below the Rs 182.85 BSE close disclosed for October 5, 2026, following a Rs 46.30 rise in the quoted market price from September 24.
The next disclosed matters to watch are BSE’s in-principle approval for the proposed preferential issue, which remained awaited at the Letter of Offer date, and any higher-priced acquisition that could trigger an upward price revision. Investors can also monitor acceptance of the Rs 7.57 crore offer and the proposed conversion of 63,50,000 warrants, for which the acquirers say takeover-regulation obligations will apply if triggered.