










Tyche Industries Limited reports Rs 146.91 lakh turnover shortfall
Key highlights
- Tyche Industries Limited’s September 2026 quarterly turnover was understated by Rs 146.91 lakh after prior-period offsets.
- September 2026 quarterly net profit after tax and reserves were each understated by Rs 41.40 lakh.
- For the half year ended September 30, 2026, turnover was overstated by Rs 13.52 lakh and net profit after tax by Rs 7.25 lakh.
- The auditor reported nil comparable impact for the quarter and half year ended September 30, 2025.
powered by IRIS
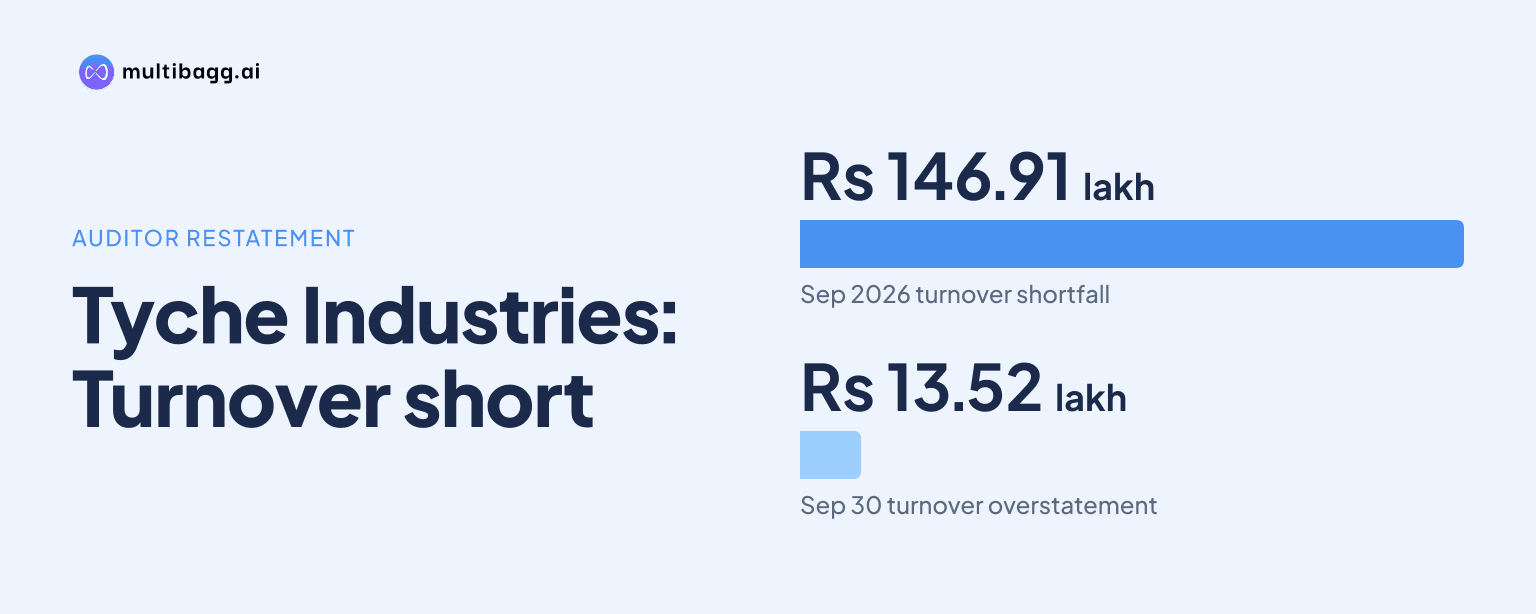
Tyche Industries Limited’s qualified limited review for the quarter ended September 30, 2026 found that turnover was understated by Rs 146.91 lakh and net profit after tax by Rs 41.40 lakh after sales were recognised before control of dispatched goods passed to customers.
Know Tyche Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Tyche Industries receive a qualified review conclusion?
Tyche Industries received the qualification because certain sales made on or before September 30, 2026 were recognised even though control of the dispatched goods had not passed to the respective customers. The auditors said dispatch had occurred by that date, but the treatment did not comply with Indian Accounting Standard 115, or Ind AS 115, on income recognition.
The independent auditors’ limited review report dated November 13, 2026 covered the quarter and half year ended September 30, 2026. It said the review was performed under Standard on Review Engagements 2410 and was substantially narrower in scope than an audit under the Companies Act, 2013, so the auditors did not express an audit opinion.
Tyche Industries’ board approved the unaudited results on November 13, 2026 under Regulation 33 of the Securities and Exchange Board of India, or SEBI, Listing Obligations and Disclosure Requirements Regulations, 2015. Tyche Industries operates in one reportable business segment, active pharmaceutical ingredients, or APIs, and the filing does not split the affected sales between other segments.
How much did the issue affect Tyche Industries' quarterly results?
For the quarter ended September 30, 2026, the auditors quantified a Rs 146.91 lakh understatement of turnover and a Rs 41.40 lakh understatement of net profit after tax. The Rs 41.40 lakh effect also applied to reserves in the balance sheet at quarter-end, after considering what the report described as the quid-pro-quo effect of the earlier quarter.
The report identifies recognition before control passed to customers, while its stated quarter-end figures are net impacts after earlier-quarter offsets. Tyche Industries did not provide a transaction-level reconciliation, identify the customers involved, state the number of affected dispatches, or disclose the gross amount of sales initially recognised before those offsets.
The corresponding quantified impact for the quarter ended September 30, 2025 was nil, according to the auditors. The comparison means the filing identifies the timing issue in the September 2026 quarter but does not record a comparable quantified effect for the quarter a year earlier.
Got a follow-up? Ask IRIS
What changed in Tyche Industries' half-year measurement?
For the half year ended September 30, 2026, the direction of the net effect changed: turnover was overstated by Rs 13.52 lakh, while net profit after tax and reserves were each overstated by Rs 7.25 lakh. The auditors attributed the half-year figures to the quid-pro-quo effect of the earlier half year rather than describing them as the gross value of sales for which control had not transferred.
The Rs 146.91 lakh quarterly turnover understatement and the Rs 13.52 lakh half-year turnover overstatement therefore cannot be treated as interchangeable measures. The difference reflects the earlier-period offsets expressly cited by the auditors in the September 30, 2026 limited review report.
For the comparable half year ended September 30, 2025, the report recorded nil impact on turnover, net profit after tax and reserves. The auditors did not say that the September 2026 matter had been corrected in the published unaudited results, and their review conclusion remained qualified in respect of the issue.
What did the auditors conclude on the remaining September results?
Subject to the qualification, the auditors said nothing had come to their attention that caused them to believe the September 30, 2026 financial statement failed to disclose information required by Regulation 33 or contained a material misstatement. That conclusion applied to a limited review of the quarterly and half-year results, not a full statutory audit.
Tyche Industries’ management was responsible for preparing the statement under Ind AS 34, Interim Financial Reporting, and other accounting principles generally accepted in India. The board approved the September 2026 unaudited results, while the auditors identified the exception to revenue recognition under Ind AS 115.
The November 13, 2026 filing gives no management explanation for why control had not passed despite dispatches having occurred on or before September 30, 2026. It also contains no disclosed remediation plan, revised revenue-recognition process, restatement proposal or timetable for resolving the sales-control issue.
Conclusion
The qualification identifies a defined revenue-recognition issue in Tyche Industries’ September 2026 results: dispatch by September 30 did not itself establish that control had transferred to customers. After prior-period offsets, the auditors put the quarterly impact at Rs 146.91 lakh on turnover and Rs 41.40 lakh on net profit after tax and reserves, while the half-year net effects were smaller and in the opposite direction.
What to watch next is whether the unresolved recognition matter remains in later financial disclosures. The report dated November 13, 2026 disclosed no remediation target, restatement timetable or scheduled correction, leaving subsequent Tyche Industries results as the relevant company disclosures for an update.