










Usha Martin Education H1 profit falls 28% to Rs 6.54 lakh
Key highlights
- Usha Martin Education reported H1 2026 consolidated net profit of Rs 6.54 lakh, down from Rs 9.11 lakh a year earlier.
- Usha Martin Education revenue from operations fell to Rs 29 lakh in H1 2026 from Rs 35.50 lakh in H1 2025.
- Usha Martin Education used Rs 4.06 lakh in operating activities and received Rs 34.44 lakh from sale of investments.
- Usha Martin Education cash and cash equivalents rose to Rs 10.17 lakh at 30 September 2026 from Rs 2.39 lakh at 31 March 2026.
powered by IRIS
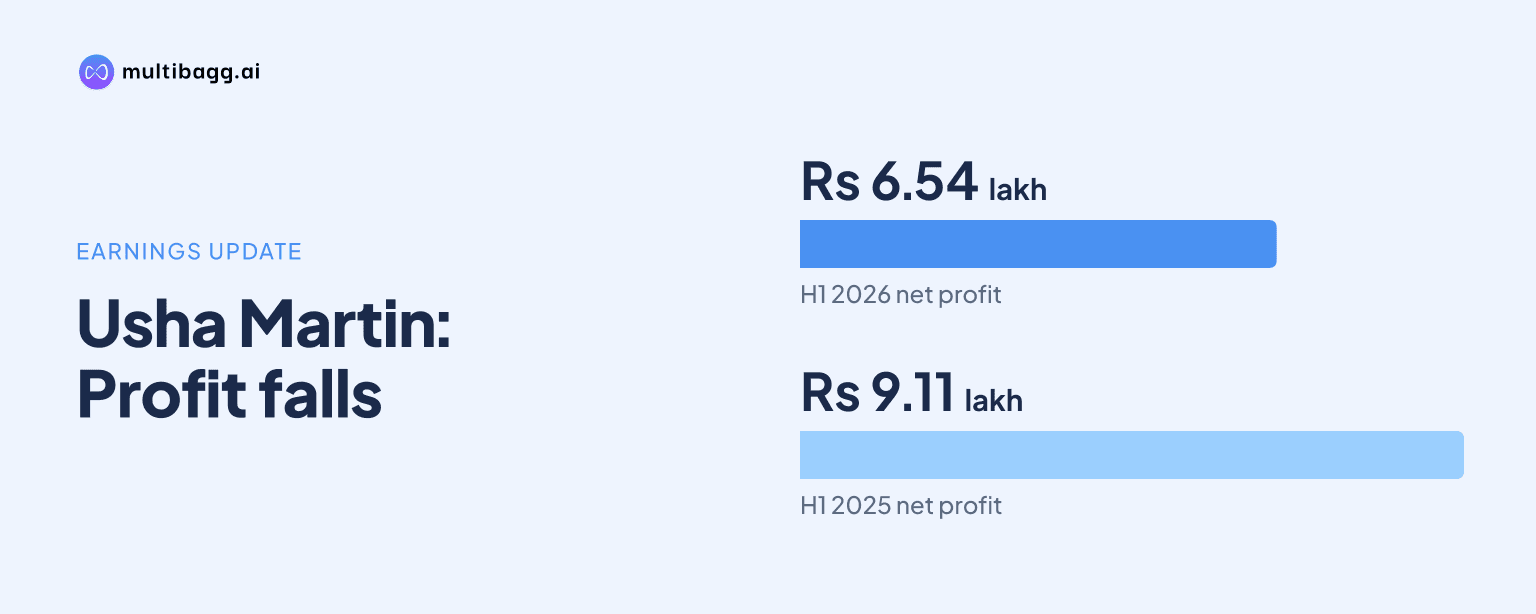
Usha Martin Education & Solutions Limited reported consolidated net profit of Rs 6.54 lakh for the half-year ended 30 September 2026, down 28% from Rs 9.11 lakh a year earlier, after revenue from operations declined to Rs 29 lakh from Rs 35.50 lakh and operating activities used Rs 4.06 lakh of cash.
Know Usha Martin Education & Solutions inside out
Results, valuation, peers and who's buying, in one view.
Why did Usha Martin Education H1 profit fall?
Usha Martin Education's H1 profit fell because the Rs 6.50 lakh decline in revenue from operations was larger than the Rs 3.50 lakh reduction in total expenses. Revenue from operations was Rs 29 lakh in the half-year ended 30 September 2026, compared with Rs 35.50 lakh in the corresponding prior-year half, while total expenses were Rs 22.39 lakh against Rs 25.89 lakh.
Profit before tax was Rs 6.61 lakh, down from Rs 11.79 lakh in H1 2025. The group recorded tax expense of Rs 0.07 lakh in H1 2026, compared with Rs 0.24 lakh a year earlier, resulting in a Rs 6.54 lakh net profit rather than Rs 9.11 lakh. Basic and diluted earnings per share, not annualised, were Rs 0.02, versus Rs 0.03 in the prior-year half.
Usha Martin Education's second quarter accounted for more than half of the first-half profit. The September 2026 quarter produced net profit of Rs 4.56 lakh on revenue from operations of Rs 17 lakh, compared with Rs 1.98 lakh profit and Rs 12 lakh revenue in the June 2026 quarter. Quarterly profit before tax rose to Rs 4.59 lakh from Rs 2.02 lakh over those two quarters.
Which costs changed for Usha Martin Education in H1?
Usha Martin Education reduced purchases of traded goods, employee benefits and other expenses in H1 2026, but those reductions did not match the revenue decline. Purchases of traded goods were Rs 10.95 lakh, down from Rs 11.74 lakh, employee benefits expense was Rs 1.33 lakh against Rs 2.97 lakh, and other expenses were Rs 10.01 lakh compared with Rs 11 lakh.
Finance costs declined to Rs 0.10 lakh from Rs 0.18 lakh, while depreciation and amortisation increased marginally to Rs 0.10 lakh from Rs 0.09 lakh. The cost movements reduced total expenses by about 14% year on year, whereas revenue from operations fell by about 18%, leaving profit before tax lower by Rs 5.18 lakh.
Usha Martin Education identifies only one reportable segment under Indian Accounting Standard 108, or Ind AS 108. The consolidated filing therefore does not disclose revenue, expenses or profit separately by business line. Its paid-up equity share capital was unchanged at Rs 2.64 crore at 30 September 2026.
What happened to Usha Martin Education operating cash flow?
Usha Martin Education used Rs 4.06 lakh in operating activities in the period ended 30 September 2026, despite reporting Rs 6.61 lakh of profit before tax. Operating profit before working-capital changes was Rs 7.91 lakh, but an increase in current assets used Rs 7.72 lakh and a decrease in current liabilities used a further Rs 1.13 lakh, leaving cash generated from operations negative at Rs 0.94 lakh before taxes.
Direct taxes paid, net, were Rs 3.12 lakh, taking net operating cash flow to negative Rs 4.06 lakh. This separates accounting profit from cash generated in the period: the reported profit before tax was positive, while working-capital movements and tax payments resulted in an operating cash outflow.
Usha Martin Education received Rs 34.44 lakh from sale of investments, producing net cash from investing activities of Rs 34.44 lakh. Payments to acquire property, plant and equipment and interest received were reported below the company's rounding-off norm. The investing inflow was the stated source that exceeded both the operating outflow and the Rs 22.60 lakh used in financing activities.
Financing activities included Rs 22.50 lakh of repayments of loans from related parties and Rs 0.10 lakh of finance costs. After the Rs 34.44 lakh investment-sale inflow, the Rs 4.06 lakh operating outflow and the Rs 22.60 lakh financing outflow, cash and cash equivalents increased by Rs 7.78 lakh to Rs 10.17 lakh at 30 September 2026 from Rs 2.39 lakh at 31 March 2026.
Got a follow-up? Ask IRIS
What does Usha Martin Education balance sheet show?
Usha Martin Education's consolidated assets were Rs 3.03 crore at 30 September 2026, down from Rs 3.19 crore at 31 March 2026. Non-current investments fell to Rs 2.62 crore from Rs 2.96 crore, a Rs 34.44 lakh movement that corresponds with the cash-flow statement's sale-of-investments inflow.
Current assets rose to Rs 40.48 lakh from Rs 22.13 lakh. Cash and cash equivalents rose to Rs 10.17 lakh from Rs 2.39 lakh, while current tax assets increased to Rs 11.64 lakh from Rs 8.58 lakh and other current assets rose to Rs 10.87 lakh from Rs 3.15 lakh.
Total equity increased to Rs 2.52 crore from Rs 2.45 crore over the same period. Other equity improved to negative Rs 12.44 lakh from negative Rs 18.98 lakh, a Rs 6.54 lakh change matching the consolidated H1 net profit. Total current liabilities declined to Rs 51.20 lakh from Rs 73.93 lakh, and current borrowings were Rs 1.59 lakh at the September reporting date compared with Rs 22.50 lakh at 31 March 2026.
How was Usha Martin Education H1 result reviewed?
Usha Martin Education's board approved the unaudited consolidated financial results on 13 November 2026 after review by its audit committee. BCAG & Associates performed a limited review under Standard on Review Engagement 2410, which the auditor said provides moderate assurance through enquiries and analytical procedures rather than an audit opinion.
The consolidated results include Usha Martin Education Private Limited. Before consolidation adjustments, the subsidiary reported total assets of Rs 1.30 crore, total income of Rs 0.75 lakh, net profit after tax of Rs 0.21 lakh and net cash outflow of Rs 1.11 lakh at 30 September 2026. BCAG & Associates said its conclusion on the subsidiary's figures relied on the report of the subsidiary's auditor.
Usha Martin Education also said it had unabsorbed depreciation available for set-off under the Income Tax Act, 1961. Management did not recognise a deferred tax asset because it could not assess the extent of future taxable income against which the asset might be adjusted. The results note says the statutory auditors provided an unmodified opinion on the financial results.
Conclusion
Usha Martin Education ended H1 2026 with lower revenue and lower profit than a year earlier, while positive accounting earnings did not translate into operating cash generation. The Rs 6.54 lakh net profit was Rs 2.57 lakh below the prior-year result, and the Rs 34.44 lakh proceeds from investment sales, rather than operations, supported the increase in cash and cash equivalents to Rs 10.17 lakh.
The next reported results will show whether the September quarter's Rs 17 lakh revenue from operations can be sustained and whether working-capital movements reverse after the Rs 4.06 lakh H1 operating cash outflow. The unresolved deferred-tax asset position also remains relevant because management said the availability of future taxable income could not be assessed at 30 September 2026.